


The worst umbrella companies aren't defined by one bad review. They're identified by repeated patterns, such as unclear deductions, weak compliance controls, poor payroll support, restrictive contracts or financial instability. A provider can advertise a competitive margin and still create problems if you can't understand your payslip, confirm how PAYE is handled or leave without an unreasonable penalty.
This guide explains the seven warning signs that deserve the closest attention. For each one, we'll show you what to ask for, what evidence to check and when to walk away. We'll also explain how upcoming supply-chain rules change who may carry tax risk when an umbrella company gets PAYE wrong.
Accreditation should be checked, not assumed. Transparent PAYE processes, a genuine employment contract and an understandable payslip matter more than polished marketing. UmbrellaCompany.com can help you compare providers by your role, pay rate and whether you need support with inside-IR35 work.
1. Hidden Margin Operators
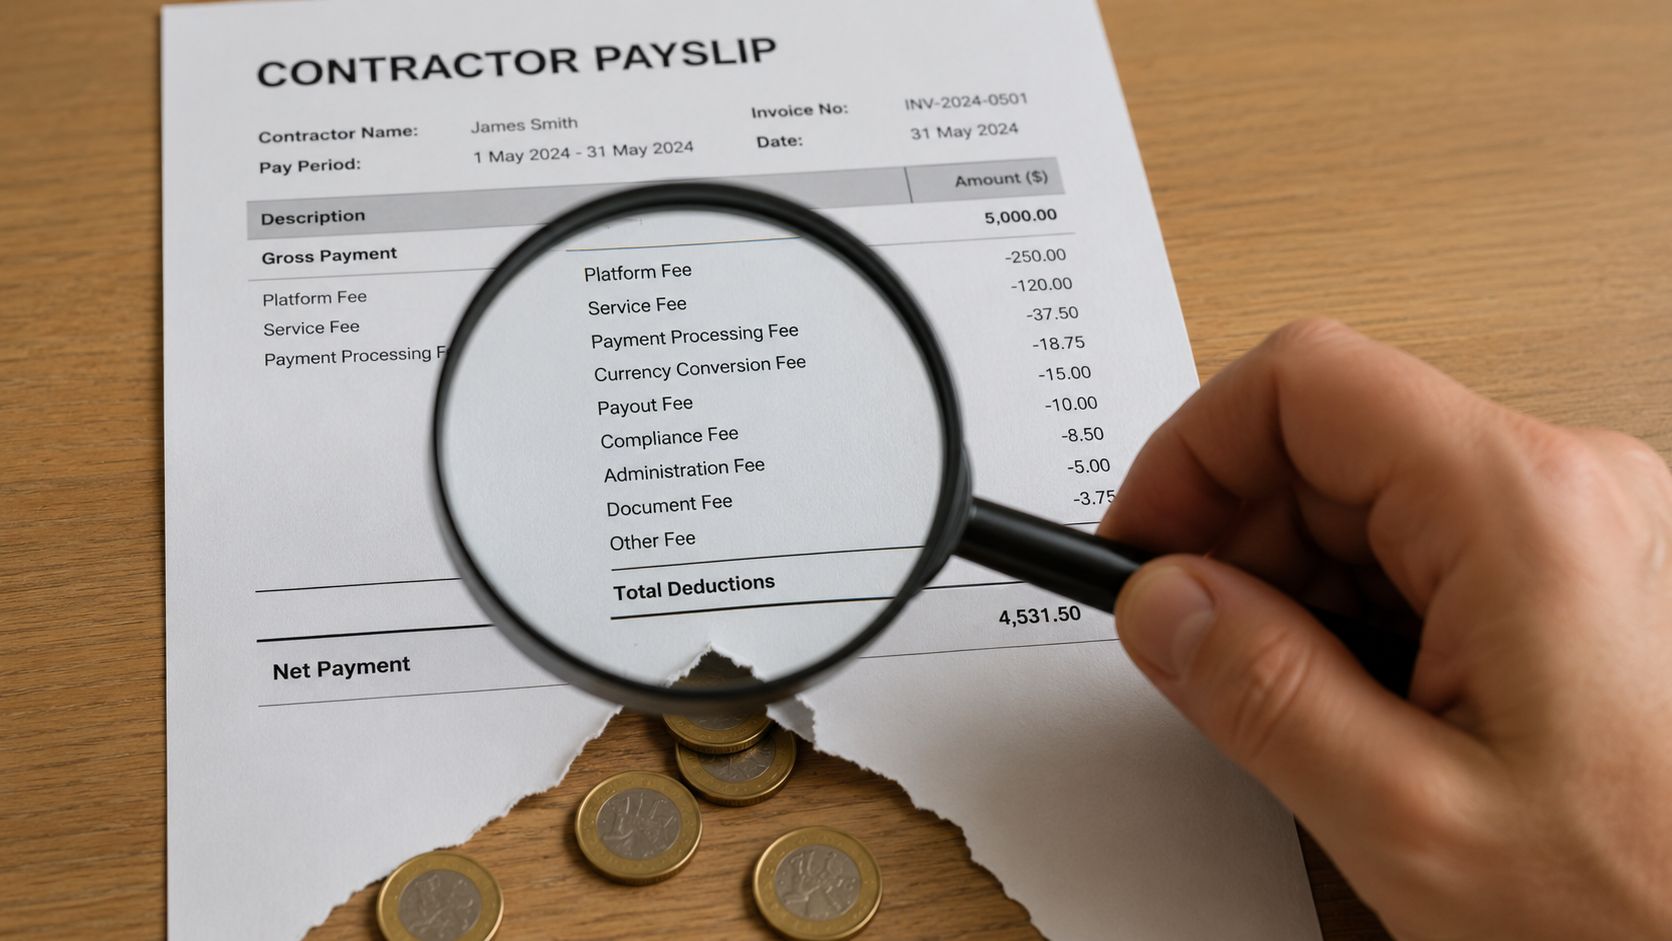
A low headline margin doesn't automatically mean you'll receive the best take-home pay. Some providers make their charges difficult to identify by spreading them across processing, compliance, software or administration lines. You may understand the advertised fee but still struggle to calculate the full cost of employment.
That creates a straightforward test. Ask the provider to show every charge before you sign, then compare the total employment cost against your expected invoiced rate. Don't compare margin percentages alone, because two providers can present their pricing differently while producing different net pay.
HMRC explains that an umbrella payslip may show operating costs, employer National Insurance, employer workplace pension contributions, holiday pay and the Apprenticeship Levy where applicable. It also lists deductions such as Income Tax, employee National Insurance, employee pension contributions, student loan repayments and other agreed or legally required deductions. You can use HMRC's guide to understanding an umbrella payslip to check whether the figures and labels make sense.
What to request before joining
- A complete fee schedule: Ask for the operating margin and every additional charge in writing.
- A sample payslip: Request an example based on your expected rate and working arrangement.
- A take-home calculation: Check the invoiced rate, employment costs, statutory deductions and final net pay.
- A written explanation: Ask who pays each employer liability and how it appears in the calculation.
Practical rule: If a provider can't explain its deductions before you join, it won't become clearer after your first payday.
A contractor comparing two offers should focus on the final calculation, not the most attractive advertising line. Unclear pricing is one of the clearest patterns associated with a poor umbrella experience.
2. Non-Compliant IR35 Facilitators
An umbrella company should process your employment through PAYE. It shouldn't promise a tax structure that turns every assignment into a low-tax arrangement, or suggest that a document labelled “IR35 insurance” removes the need for a proper status assessment.
Be especially careful where a provider offers a flat-rate tax outcome regardless of your circumstances. A compliant provider should understand the assignment, explain the relevant employment model and keep its payroll treatment consistent with the work being performed. It shouldn't encourage you, an agency or an end client to misrepresent the role.
HMRC states that it doesn't approve or endorse umbrella companies or tax avoidance schemes. Workers remain responsible for checking that the correct tax and National Insurance have been paid, so treating a provider's sales explanation as a guarantee is unsafe. FCSA accreditation information can help you understand what accredited membership is intended to cover, while FCSA says its members must follow its Charter and Codes of Compliance and pass independent audits by accountancy and legal professionals.
Questions that expose weak processes
Ask these questions before accepting an offer:
- Who determines the employment model: Is the provider acting as your employer, and is that status clear in the contract?
- What documents are reviewed: Does the provider request the assignment details rather than applying a generic answer?
- What happens inside IR35: Can it explain PAYE treatment without promising artificial tax savings?
- Who gives tax advice: Does it distinguish payroll guidance from regulated, individual tax advice?
A sound process may feel less exciting than a scheme promising unusually high take-home pay. That's a positive sign. Straightforward PAYE, clear documentation and an evidence-based approach protect you better than aggressive claims.
The same discipline applies to outsourced payroll more broadly. A useful payroll compliance checklist can help agencies and payroll teams assess whether controls are documented and repeatable.
3. Unregulated Payroll Providers Masquerading as Umbrella Companies
A payroll processor isn't automatically a compliant umbrella employer. The key question is whether the organisation employs you properly, operates an appropriate PAYE scheme and accepts the responsibilities that come with employment.
Start with the legal identity. Check the provider's Companies House record, the identity of the contracting entity and the employment contract you'll sign. The name on the contract, payslip and payment should be consistent, or the provider should give you a clear explanation for any difference.
Evidence to check
- Companies House details: Confirm the registered company name, directors and filing history.
- PAYE arrangements: Ask how the provider operates PAYE and who remains responsible for payroll submissions.
- Insurance evidence: Request confirmation of employer's liability and professional indemnity cover.
- Employment status: Check that the contract describes your employment relationship and statutory rights clearly.
- Payroll accountability: Ask where you raise errors and who corrects missed payments or deductions.
Don't accept a vague answer such as “we process payments for the agency”. A genuine umbrella arrangement should explain who employs you, who pays you and how statutory employment obligations are managed.
HMRC's guidance on umbrella company due diligence provides a useful starting point for checking a provider before you share personal or banking information. You can also compare the model with contractor of record services, although the legal arrangements and responsibilities may differ by provider and jurisdiction.
A contractor who discovers that the organisation handling payroll isn't the organisation named in the contract should pause the switch. Resolve the discrepancy in writing before starting an assignment.
4. Restrictive Contract Lock-In Providers
A low umbrella margin is not a saving if the contract makes switching costly. Lock-in risk usually appears through exit fees, lengthy notice periods, automatic renewals or exclusivity clauses. These terms can restrict your options when an assignment ends, your agency changes its approved supplier or another provider offers clearer conditions.
Read the complete agreement before accepting payment. Concentrate on termination, notice, deductions, holiday pay, pension arrangements, complaints and outstanding invoices. Sales assurances do not override written terms.
Check the exit route first
Ask these questions before signing:
- Exit fees: What triggers the charge, how is it calculated and can it be removed?
- Exclusivity: Does the clause restrict you from using another umbrella for a separate assignment?
- Automatic renewal: What confirms renewal, and how can you decline it?
- Notice periods: Can you leave without delaying your next placement?
- Changing agencies: What happens if your recruitment agency appoints another approved provider?
A fair agreement gives you a practical way to leave without disproportionate financial consequences. Agency recommendation is not a reason to accept unclear terms. Compare the written contract with the provider's explanation, and ask for any promised change in writing.
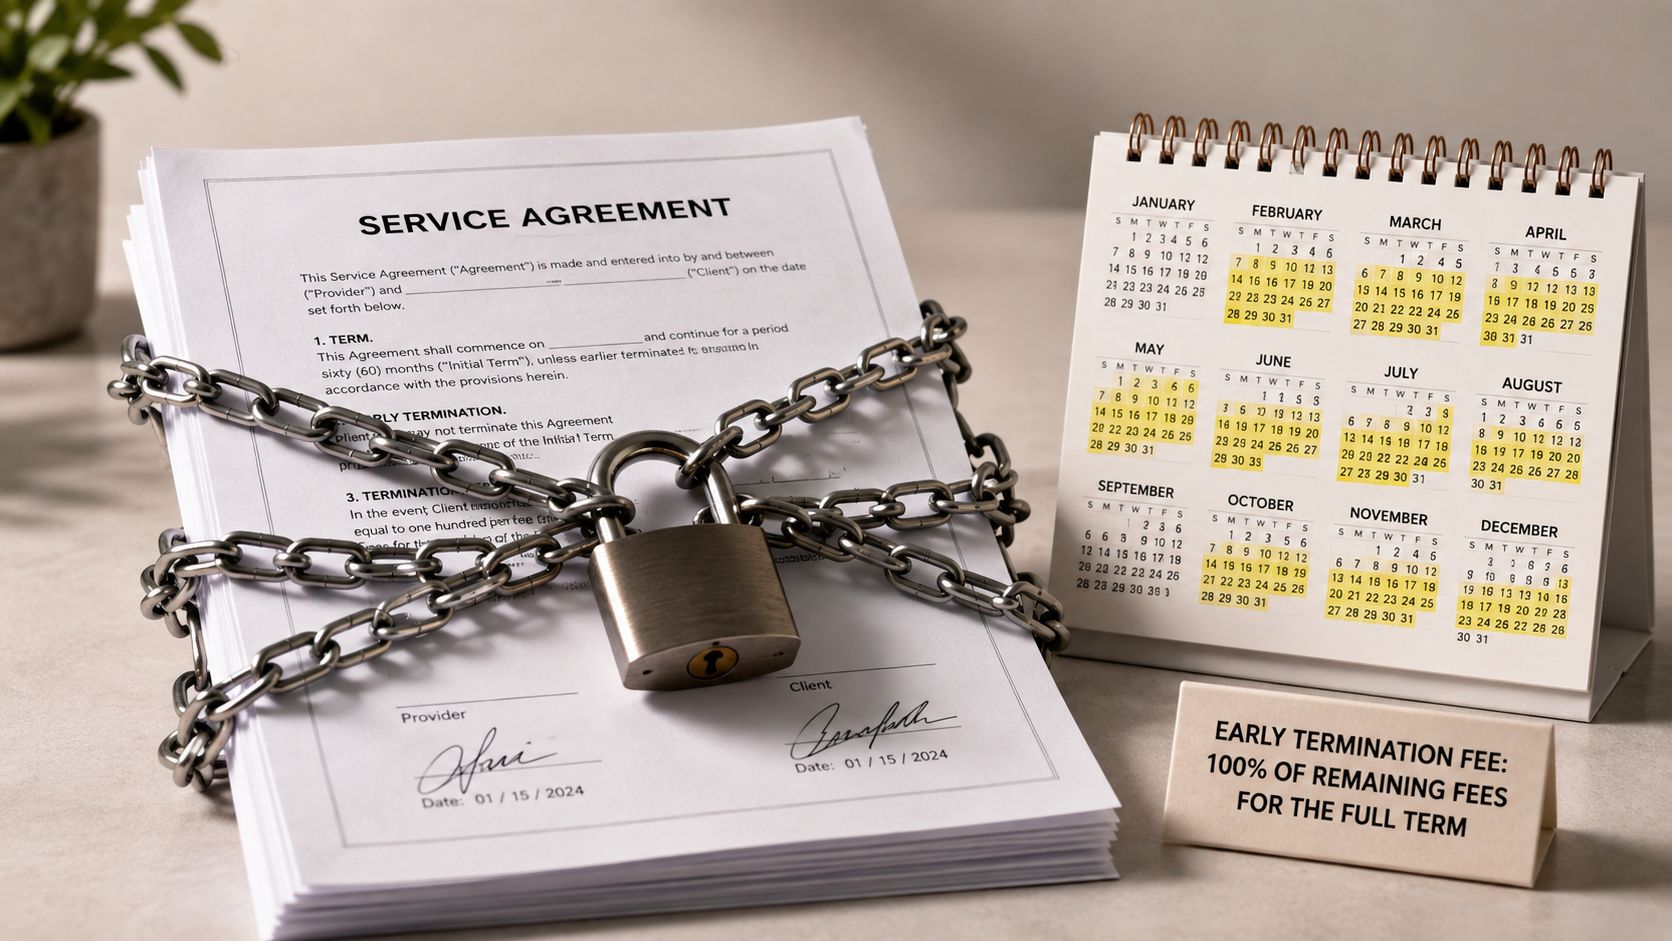
Request the full agreement, not only a welcome email or summary sheet. Give yourself time to review it, check how outstanding pay is handled after termination and keep a copy. If the provider refuses to share the terms or pressures you to sign immediately, choose another option.
5. Poor Service and Unresponsive Support Providers
A payroll problem needs a clear owner. If payslips are late, deductions look wrong, pension details are missing or questions receive no answer, your budgeting can suffer even when the cause is administrative.
Use a practical test before joining. Send a specific question about your rate, holiday pay or an expected deduction. The reply should explain the point accurately, in plain language, and show that the adviser understands umbrella payroll. A quick template response is a warning sign if it avoids the question.
Check how problems are handled
Ask the provider to explain its process for a correction, missed payment or disputed deduction. Record who replies, how long they take and whether they give a useful next step. Check these points:
- Contact routes: Confirm whether phone, email and online support are available.
- Escalation: Ask how an urgent payroll query reaches someone who can resolve it.
- Ownership: Find out whether you receive a named contact or enter a general queue.
- Correction handling: Ask what happens after an incorrect payslip or missed payment.
- Benefits support: Confirm who answers questions about pensions, statutory payments and holiday pay.
Online reviews can expose repeated service problems, but read them for patterns rather than isolated complaints. Similar reports about unanswered payroll queries, unexplained deductions or recurring delays deserve closer scrutiny. Ask the provider to address those concerns directly before you switch.
Ask for an explanation of your expected payslip, then judge the accuracy and usefulness of the answer, not its friendliness.
An agency's approved-provider list may narrow your options, but it does not test support on your behalf. You still need to understand the payslip and know who will act when payment is due. Choose a provider that gives clear answers, records queries and explains how it corrects mistakes.
6. Operators with Weak Financial Controls or Insolvency Risk
A polished brand does not prove that an umbrella company can protect payroll funds. The provider handles money linked to your work, calculates deductions and passes payments to you, HMRC and other relevant parties. Weak controls can lead to uncertainty when the business cannot meet its obligations.
Start with the legal entity named in your contract. Search its filings at Companies House, check its directors and ownership, and look for changes that may affect payroll operations. Ask how it separates money due for wages, tax, pensions and other liabilities from ordinary operating funds. Clear, consistent answers matter more than the provider's age or marketing.
Use this written-check list before switching:
- Filed accounts: Review available accounts for cash, liabilities and any going-concern comments.
- Entity and ownership: Confirm which organisation employs you and whether recent ownership or director changes alter that arrangement.
- Payroll controls: Ask how funds for wages, tax, pensions and other liabilities are managed and reconciled.
- Insurance: Check what professional indemnity or other cover exists, and which risks it responds to.
- Management stability: Look for a coherent explanation of the company structure and its payroll responsibilities.
You do not need confidential internal records, but you should receive enough information to assess financial resilience. Refusal, changing explanations or several unexplained entities should carry more weight than a glossy website.
Use this guide to financial risk when choosing an umbrella company to organise your questions. If the provider will not explain its controls, choose a clearer alternative.
7. Overly Complex or Niche Scheme Providers
Complexity isn't proof of sophistication. A structure involving several entities, offshore arrangements, dividends or investment features may create more administration and scrutiny without giving you a genuine employment benefit.
For most contractors seeking an umbrella arrangement, straightforward PAYE should be easy to explain. You should know who employs you, how the agency or client pays the chain, which deductions apply and when you'll receive your wages. If the provider can't describe the structure in plain English, don't sign it.
Compare the structure with ordinary PAYE
Ask the provider to explain:
- The legal entities involved: Identify every organisation in the arrangement and its role.
- The payment route: Confirm who invoices whom and who ultimately pays your wages.
- The tax treatment: Check whether the arrangement follows ordinary PAYE or relies on a special structure.
- The claimed advantage: Ask what specific benefit justifies the added complexity.
- The independent view: Obtain advice from an appropriately qualified tax adviser before proceeding.
Be cautious of promises that sound universal, such as guaranteed higher net pay regardless of assignment, location or personal circumstances. A legitimate provider should explain limits and responsibilities, not present a complex scheme as a risk-free shortcut.
HMRC says workers must check they pay the right tax and National Insurance, and it advises reviewing the hourly rate, hours worked, gross pay, net pay and deductions on each payslip. That makes a transparent, ordinary payroll route easier to test than an arrangement built around unexplained tax features.
7-Point Comparison of Risky Umbrella Providers
| Provider Type | Implementation Complexity | Resource Requirements (to assess / mitigate) | Expected Outcomes (risks) | Ideal Use Cases | Key Red Flags |
|---|---|---|---|---|---|
| Hidden Margin Operators | Low, simple fee layering and opaque billing | Moderate, requires payslip review and cost benchmarking | Reduced take‑home pay, budgeting uncertainty, eroded trust | None legitimate; may attract price‑sensitive contractors unaware of deductions | Vague fee explanations; payslip discrepancies; changing fees |
| Non‑Compliant IR35 Facilitators | Medium–High, engineered documentation and tax schemes | High, needs legal/tax verification and accreditation checks | HMRC investigations, back taxes, penalties, reputational/legal exposure | None legitimate; risky for contractors seeking short‑term tax saves | Claims IR35 doesn't apply without assessment; no accreditation; pressure to accept status |
| Unregulated Payroll Providers Masquerading as Umbrellas | Low–Moderate, basic payroll processing without employer safeguards | High, verify Companies House, PAYE registration, insurance | No statutory rights, liability for unpaid taxes if provider fails, no recourse for errors | None appropriate; may lure contractors seeking very low fees | No Companies House/PAYE presence, no insurance, unclear employment status |
| Restrictive Contract Lock‑In Providers | Low, onerous contract drafting and automatic renewals | Moderate, requires contract legal review to avoid penalties | Difficulty switching, steep exit costs, reduced service quality over time | None for contractors; favors provider retention strategies | Long minimum terms, high exit fees, automatic renewals, vague clauses |
| Poor Service / Unresponsive Support Providers | Low, minimal support infrastructure | Low–Moderate, test support responsiveness and review feedback | Unresolved payroll errors, delayed payslips, financial stress for contractors | None desirable; may suit very low‑cost seekers willing to accept risk | No phone/live support, long response times, repeated payroll errors in reviews |
| Operators with Weak Financial Controls / Insolvency Risk | Moderate, weak governance and poor cash controls | High, request accounts, confirm fund segregation and insurance | Risk of unpaid wages/taxes, lost pension contributions, lengthy insolvency claims | None unless independently proven financially stable | No published accounts, rapid ownership changes, no fund segregation |
| Overly Complex / Niche Scheme Providers | High, multi‑entity structures and bespoke tax arrangements | High, requires independent tax advice and full disclosure | Higher fees, audit risk, administrative burden, potential HMRC challenge | Limited, may suit very specific niche cases after independent advice | Difficulty explaining structure, "tax optimisation" claims, pressure to accept scheme |
Choose Transparency Before a Low Headline Margin
Choosing among umbrella companies shouldn't start with the lowest advertised fee. Start with evidence. A provider that explains its charges, PAYE process, employment contract and support arrangements gives you a stronger basis for comparing take-home pay and service quality.
Use this decision sequence before you switch:
- Request the complete fee breakdown: Ask for every operating charge, employer cost and agreed deduction in writing.
- Check a sample payslip: Compare the expected rate with gross pay, statutory deductions and net pay.
- Verify the employer and PAYE details: Match the legal entity on the contract, payslip and payment documentation.
- Review IR35 handling: Ask how the provider treats inside-IR35 assignments and whether its process is documented.
- Check relevant accreditation: FCSA says accredited members follow its Charter and Codes of Compliance and undergo independent audits. Treat accreditation as evidence to verify, not a substitute for reading the contract.
- Read exit terms: Look for notice periods, termination fees, exclusivity and automatic renewals.
- Test customer support: Send a detailed query and check whether the answer is accurate and useful.
- Review available financial information: Examine Companies House filings and ask how the provider controls payroll funds.
The regulatory context makes these checks more important. HMRC reported that umbrella companies were used to engage at least 700,000 workers in the UK in 2022 to 2023, and that at least 275,000 workers had at some point been engaged by umbrellas that failed to comply with their tax obligations. HMRC also said around £500 million was lost to disguised remuneration tax avoidance schemes in that year, almost all facilitated by umbrella companies. You can read the government response on tackling non-compliance in the umbrella market for the underlying analysis.
The rules also change who carries the risk. From 6 April 2026, HMRC can pursue the recruitment agency, or the end client where no agency exists, for PAYE shortfalls caused by an umbrella company in the labour supply chain. The PAYE rules for labour supply chains explain this joint-and-several-liability model.
That means agencies and end clients need stronger supplier controls, while contractors should ask who stands behind the payroll arrangement. If you work through one agency, several agencies or directly with an end client, the party carrying recovery risk may differ. Confirm the chain in writing before you start.
One negative review isn't conclusive. Repeated complaints about unexplained deductions, missed payments, weak support or difficult exits are different, especially when the provider can't answer them. Choose transparency over a low headline margin, and use UmbrellaCompany.com's comparison portal to compare providers according to your role, pay rate and inside-IR35 requirements.
UmbrellaCompany.com helps contractors and freelancers compare umbrella providers by role, pay rate and working arrangement, with guidance on IR35 and compliance. Visit Umbrella Company to compare clearer options and check the practical details before you move your payroll.


