


You've just received a contract offer with an attractive day rate, and the recruiter has asked which umbrella company you'd like to use. The figure in the advert looks promising, but it isn't necessarily the amount that will reach your bank account. An umbrella company take-home pay calculator helps translate the assignment rate into a more realistic view of your pay after employment costs and PAYE deductions.
The result depends on more than your day rate. You'll need to consider your working pattern, tax code, pension choice, location, student loan position, and the umbrella company's margin. A reliable estimate should show gross pay, taxable pay, deductions, and net take-home pay, rather than presenting one unexplained figure.
By the end of this guide, you'll know which details to enter, how the deductions are applied, why an estimate may differ from your payslip, and why a single-role calculator may not suit contractors managing several engagements. If you're also exploring flexible ways to supplement contract income, a practical guide to find your side hustle app options may help you compare possibilities without confusing side income with your PAYE contract earnings. You can also read our explanation of the benefits of working through an umbrella company before choosing your next arrangement.
Why Contractors Use a Take-Home Pay Calculator
A recruiter's quoted rate is often an assignment rate, not your salary. The UK government's umbrella pay guidance says workers and employment businesses can use its calculator to estimate gross and net pay from an umbrella company for a single role, and it makes clear that the user needs to know the assignment rate. The guidance describes this as the uplifted rate, umbrella rate, day rate, or hourly rate. You can read the official UK government umbrella pay guidance for the current tax-year approach.
That distinction matters because the umbrella company receives the assignment payment and uses it to meet employer costs, apply its margin, and calculate your PAYE earnings. Your taxable salary is therefore not just your day rate multiplied by the number of days worked.
Start with the information you actually have
Before opening a calculator, gather the details below:
- Assignment rate: Confirm whether the agency quoted a daily or hourly rate and whether it's the uplifted umbrella rate.
- Working pattern: Note your expected hours, days, and pay frequency.
- Tax code: Use the code on your payslip or HMRC correspondence.
- Pension choice: Check whether contributions are being made and whether salary sacrifice applies.
- Umbrella margin: Find the provider's fee in its written terms or fee schedule.
- UK location: Confirm whether Scottish tax treatment applies.
The calculator then separates the result into four useful stages. It estimates the amount paid to the umbrella, the pay available for your employment calculation, the deductions taken through payroll, and the net amount you can expect to receive.
Practical rule: Treat the result as a planning estimate, not a promise of an identical payslip.
This tool is particularly useful when comparing two contract offers, checking whether a proposed rate supports your household budget, or deciding whether an umbrella arrangement is suitable for a role inside IR35. It won't produce one universal answer because your circumstances and the inputs can change the result.
Every Input the Calculator Needs From You
The accuracy of an umbrella estimate starts before you press “calculate”. If one field is wrong, the output may look precise while describing a different pay situation from yours.
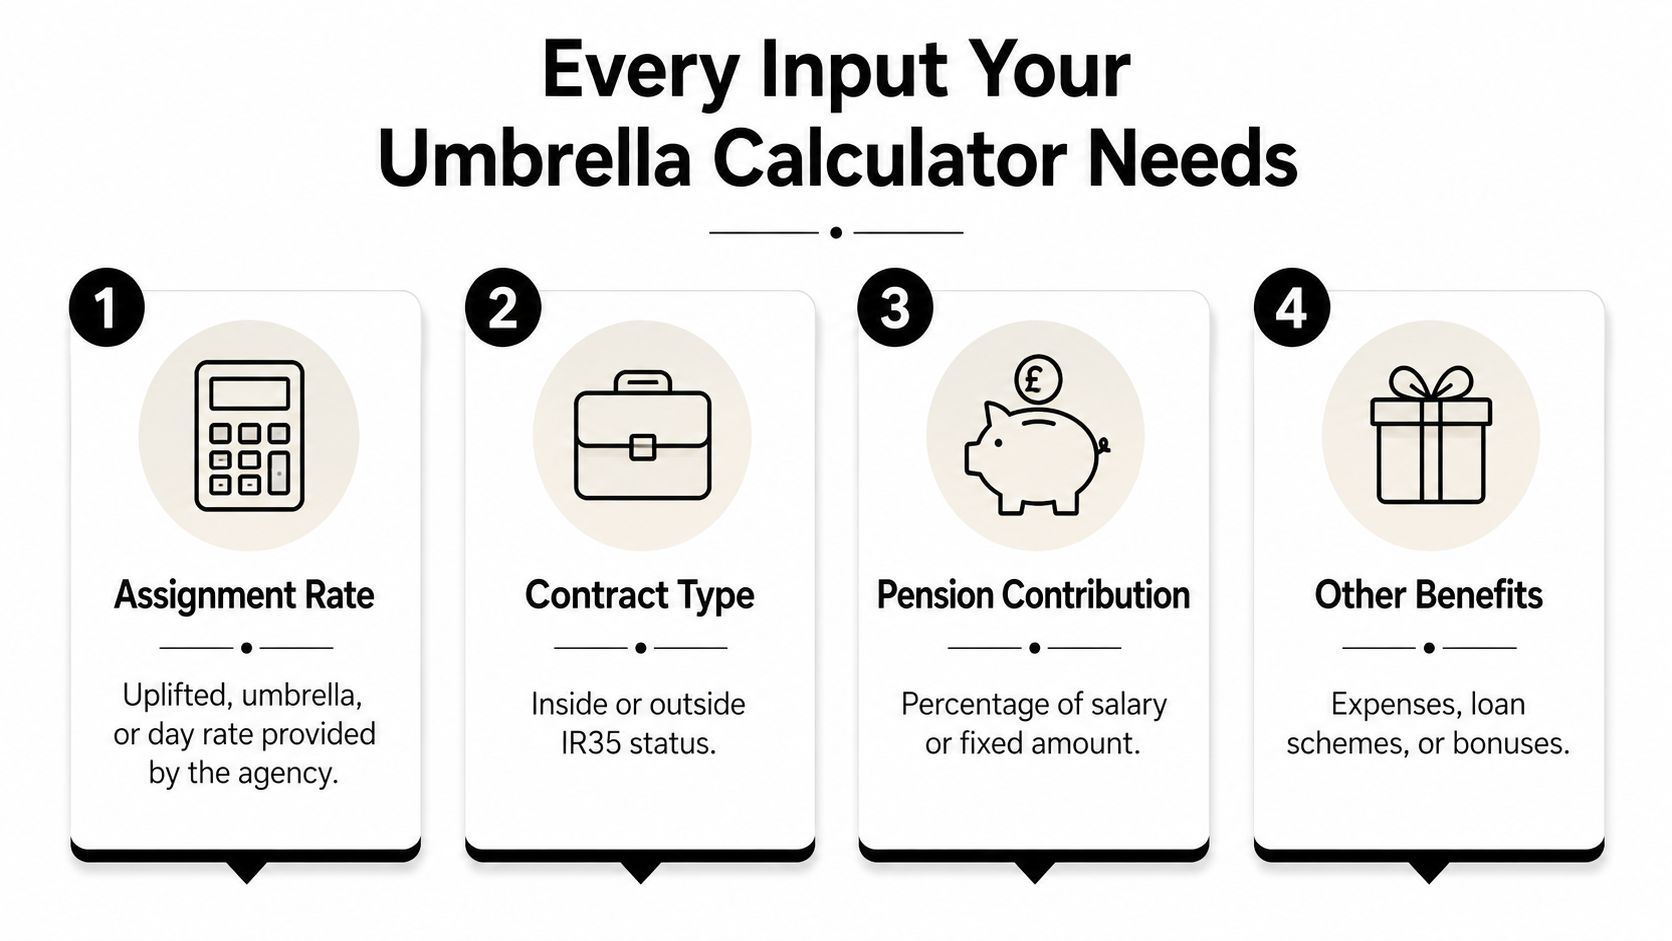
Begin with the assignment rate
The assignment rate is the amount agreed between the agency and the umbrella company for your work. It may appear in your contract paperwork as the uplifted rate, umbrella rate, day rate, or hourly rate. Don't assume that a rate described casually as “your pay” is your taxable salary. Ask the agency to confirm exactly what the quoted figure represents.
Your working pattern comes next. Enter the number of hours or days you expect to work and select the relevant pay frequency. A day rate spread across a regular week produces a different payroll result from an hourly role with variable shifts, even if the headline rate appears similar.
Check tax, location, and deductions
Your tax code tells payroll how to apply your personal tax position. Find it on your latest payslip or an HMRC letter, and don't automatically accept the default shown by a generic calculator if you've recently changed jobs.
Your location also matters. A calculator that doesn't distinguish Scotland from the rest of the UK may not reflect the correct Income Tax treatment. The government tool asks for the UK location as part of its calculation inputs, so this field shouldn't be treated as optional.
Pension and student loan fields need equal care:
- Pension contribution: Select the correct contribution method and percentage or fixed amount shown in your employment terms.
- Student loan plan: Choose the plan that applies to you, if any. The wrong selection can make the estimate materially different from payroll.
- Umbrella margin: Use the fee stated by the provider. Check whether it's deducted per pay period and whether another employment business fee appears in the paperwork.
You can learn how PAYE deductions fit together in our guide to how PAYE works. The key habit is simple, save a copy of the inputs you used. That gives you something concrete to compare with the eventual payslip.
How the Calculator Turns Your Rate Into Net Pay
The calculation follows a layered structure. The assignment rate enters first, but it doesn't become your salary immediately.
A 2026/27 UK umbrella calculator example explains the sequence as the umbrella margin being subtracted first, followed by employer National Insurance and the apprenticeship levy, before PAYE deductions are applied. You can review the 2026/27 umbrella calculator breakdown for the stated thresholds and calculation method.
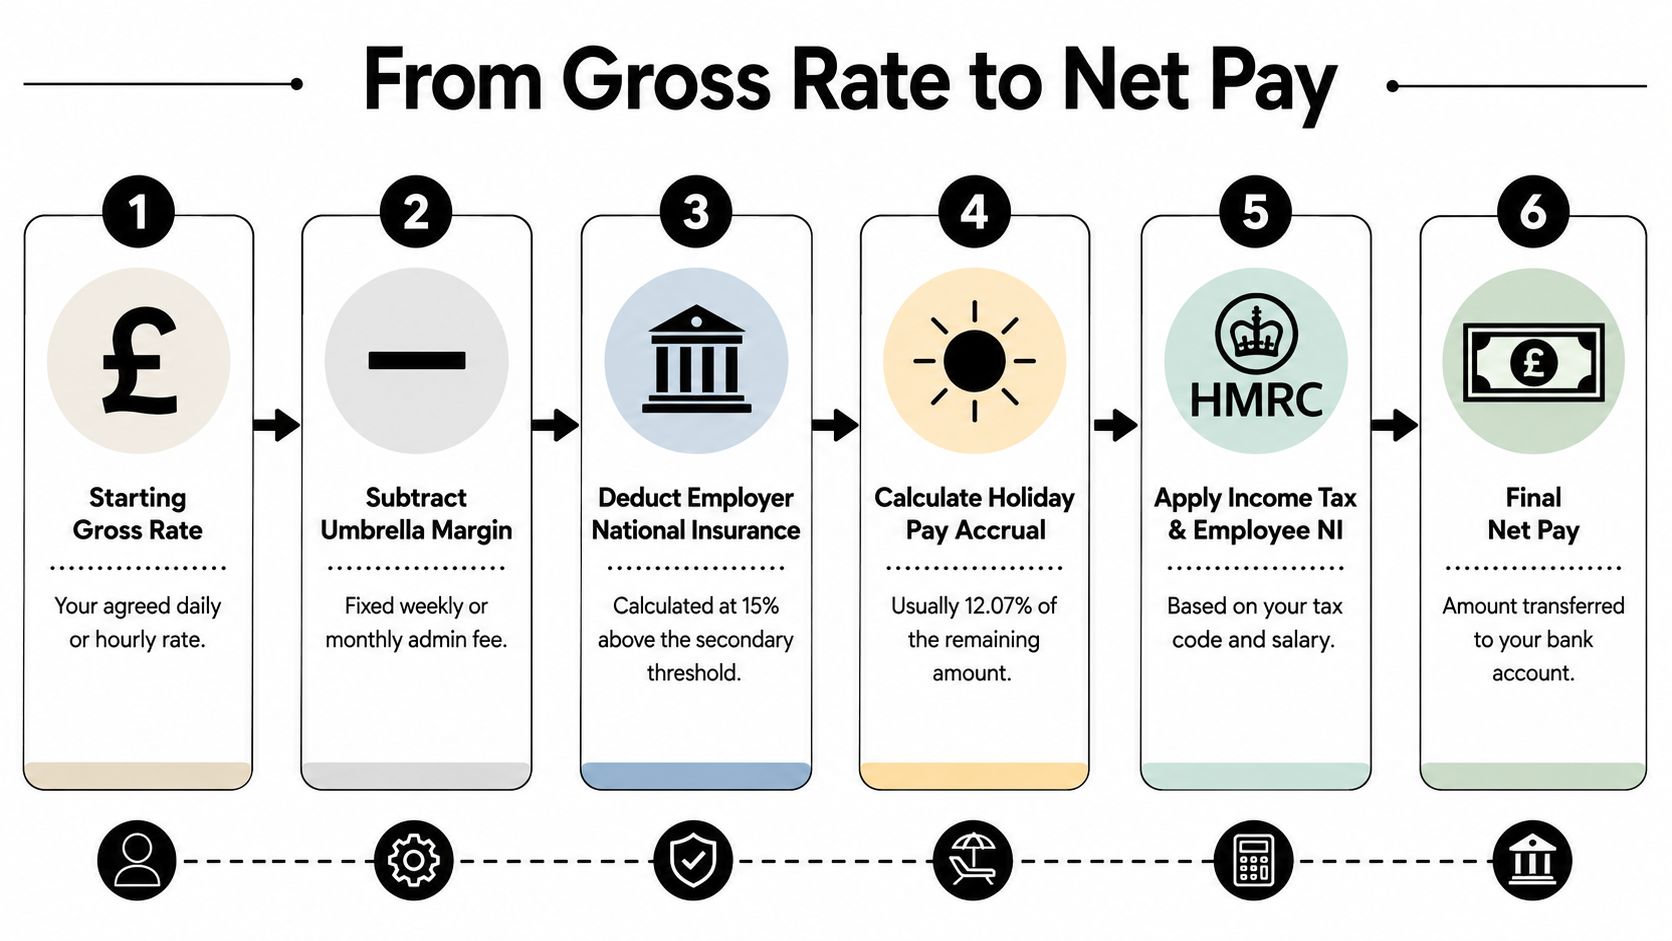
The employer-cost layer
First, the calculator removes the umbrella margin. This is the provider's charge for employing you, operating payroll, and administering the assignment. The amount should be clear in the provider's fee information.
Next comes employer National Insurance. For the cited 2026/27 example, employer NI is calculated at 15% above £5,000 per year. The apprenticeship levy is shown at 0.5% where it applies. These are employer-side costs, but they're commonly allowed for within the assignment rate, which means they reduce the amount available to calculate your gross taxable pay.
HMRC's employment status manual states that employer NICs are deducted from the payment the umbrella receives from the recruitment agency, not from the worker's gross pay. It also explains that employers, including umbrella companies, can't lawfully deduct employer NICs from the worker's gross pay. The HMRC explanation of employer National Insurance deductions is useful when checking a confusing illustration.
The employee PAYE layer
Once the employer costs and margin have been accounted for, payroll applies Income Tax and employee National Insurance to your taxable earnings. The cited 2026/27 example shows:
- Personal allowance: £12,570.
- Basic-rate Income Tax: 20% up to £37,700.
- Higher-rate Income Tax: 40% up to £125,140.
- Additional-rate Income Tax: 45% above that threshold.
- Employee National Insurance: 8% between £12,570 and £50,270, then 2% above that threshold.
Your tax code determines how these rules are applied to your circumstances. Pension contributions, student loan deductions, and other payroll items may then reduce the amount transferred to you.
The distinction between an assignment rate and your pay rate causes many misunderstandings. A plain-language explanation of how those figures differ is available in this guide to compare bill rate and pay rate. For a further explanation of the final calculation, see our guide on how to determine take-home pay after taxes.
Two Worked Examples That Show the Practical Difference
A £500 daily rate can produce different outcomes depending on how the engagement is structured. For an inside-IR35 contract paid through an umbrella, the assignment rate feeds into employer costs, the umbrella margin, and PAYE deductions. For an outside-IR35 engagement through a limited company, the company's tax position and income-extraction choices also shape the final bank payment.
The comparison below uses the required £500 daily rate. It shows how a calculator frames the two routes, not what every payslip will show. This contractor umbrella calculator guidance also explains why employer NIC assumptions and pension salary sacrifice can shift an estimate.
| Input | Inside IR35 via umbrella | Outside IR35 via limited company |
|---|---|---|
| Quoted rate | £500 per day | £500 per day |
| Tax treatment | PAYE employment calculation | Limited company extraction method |
| Employer costs | Employer NI and apprenticeship levy considered within the assignment-rate calculation | Company costs and tax treatment considered separately |
| Personal deductions | Income Tax, employee NI, pension, and possible student loan deductions | Salary and dividend decisions, plus company and personal tax obligations |
| Take-home outcome | Often falls around 55% to 65% of gross contract value, depending on inputs | No single reliable percentage can be stated without full company and personal details |
| Main administrative burden | Umbrella handles payroll and PAYE | Contractor manages or pays for company administration |
Inside IR35 through an umbrella
The umbrella example begins with the £500 assignment rate, rather than treating it as your taxable salary. Employer costs and the umbrella margin are accounted for first. PAYE deductions then apply to the taxable pay that reaches payroll.
The expected result generally sits within the 55% to 65% benchmark, although your tax code, pension settings, pay frequency, and other deductions can move it. The figure is a planning range, not a promise of a particular payslip.
That distinction is easy to miss. The £500 is the amount associated with the assignment, while your payslip shows the result after the umbrella calculation and payroll deductions. It works like a funnel: the quoted rate enters at the top, and several costs and deductions narrow the amount that reaches your bank account.
Outside IR35 through a limited company
The outside-IR35 example keeps the same headline rate but changes the route through which income reaches you. A limited company may pay a director's salary and dividends, yet the available amount depends on company taxation, expenses, accounting costs, and your chosen extraction method.
A precise net figure would therefore require those details. Giving one without them would make the comparison look clearer than it is.
The useful comparison is structure and assumptions, not a guarantee that one route always produces more money. Contractors considering a company route also need to allow for its compliance and administration before comparing the final payment. For a separate illustration of higher-income calculations, see this guide to take-home pay on £100k.
Where Calculators Get It Wrong
A calculator can perform the maths correctly and still give you the wrong planning answer if the inputs don't match your contract. The most persistent problem is the single-role limitation. HMRC's tool is designed for a single role, so it won't automatically model overlapping engagements, irregular hours, or several changing assignment rates.
That limitation matters for contractors who move between clients or combine a main contract with another assignment. Entering one blended rate may create a tidy estimate, but it can't represent how each engagement is taxed and paid in practice.
Inputs that quietly change the answer
- Scottish tax treatment: A generic calculator may assume the rest of the UK. Confirm the location setting before relying on the result.
- Tax code: A temporary or incorrect code can make the first payslip differ from a later settled position.
- Pension treatment: Salary sacrifice and other pension settings affect taxable pay and net pay differently. Confirm the option selected.
- Student loan plan: The correct plan must be selected if deductions apply. A generic default may not reflect your payroll record.
- Benefits and expenses: Taxable benefits, such as a car or accommodation, may change the payroll position if the tool doesn't include them.
- Tax year: The government guidance says its calculator works for the current tax year only. Thresholds should be checked again when the tax year changes.
A payslip may also differ because the calculator assumes consistent work while your actual period includes unpaid leave, a changed rate, a late timesheet, or a different pension instruction. Use the estimate as a planning anchor, then ask the umbrella provider to explain each variance rather than focusing only on the final net figure.
Using Your Results With Confidence
A useful result should show more than a large take-home number. Check that it identifies the assignment rate, explains the gross or taxable pay calculation, lists deductions by category, and gives the net amount separately.
Use these checks before making a contract decision:
- Compare recent payslips: Look for recurring differences between the estimate and your last three payslips.
- Confirm payroll details: Check the tax code, pension contribution, student loan setting, working pattern, and UK location.
- Request written information: For a longer assignment, ask the umbrella provider for a written illustration based on your contract details.
- Recalculate after changes: Run the figures again when the tax year changes, your rate changes, or you switch provider.
The calculator should help you ask better questions. It shouldn't replace the payslip, employment contract, or a clear explanation of how employer costs are funded from the assignment rate.
You can also compare providers using a portal that places margins, accreditation, and IR35 support alongside one another. That makes it easier to check whether a lower quoted margin comes with the payroll support you need.
Umbrella Company helps contractors compare umbrella providers and understand how different margins, IR35 arrangements, and payroll assumptions affect take-home pay. Use the Umbrella Company comparison service to review your options, check the details behind each estimate, and choose a provider with greater confidence.


