


If you're a freelancer or contractor, you have probably heard the term 'umbrella company' mentioned. But what exactly is one, and why might you need it? This guide explains everything you need to know.
Think of an umbrella company as an administrative partner. It acts as an employer for independent contractors like you, handling all the tricky payroll and tax matters so you do not have to.
This arrangement is a huge help, especially when you're working on contracts that fall ‘inside IR35’. Instead of juggling invoices and setting money aside for HMRC, the umbrella company sorts it all out for you through a standard PAYE (Pay As You Earn) system.
It is a straightforward way to get paid while maintaining your contracting freedom.
Core Umbrella Company Services at a Glance
So, what do you get for your money? We find that most umbrella companies offer a core set of services designed to make your life easier. Here is a quick breakdown of what you can expect:
| Service Provided | What This Means For You |
|---|---|
| PAYE Payroll | Your income tax and National Insurance are calculated and paid directly to HMRC. No more self-assessment headaches for your contract income. |
| Invoicing & Payments | They raise invoices to your client or agency and chase payments on your behalf, ensuring you get paid on time. |
| Employment Status | You become a formal employee of the umbrella company, giving you a continuous employment record for things like mortgages or loans. |
| Statutory Benefits | You're entitled to statutory sick pay, maternity/paternity pay, and holiday pay, just like a regular employee. |
| Pensions & Insurance | They will auto-enrol you into a workplace pension and provide the necessary business insurances (like Public Liability and Professional Indemnity). |
Ultimately, an umbrella company provides a compliant, hassle-free payroll solution. It bridges the gap between freelancing and traditional employment, offering the best of both worlds for many contractors.
For a deeper dive, check out our full definition of an umbrella company.
How You Get Paid Through an Umbrella Company
So, how does the money get from your client to your bank account? When you work with an umbrella company for freelancers, the entire payment process is sorted for you. It is a simple, structured system designed to take care of all the fiddly admin, leaving you to get on with your work.
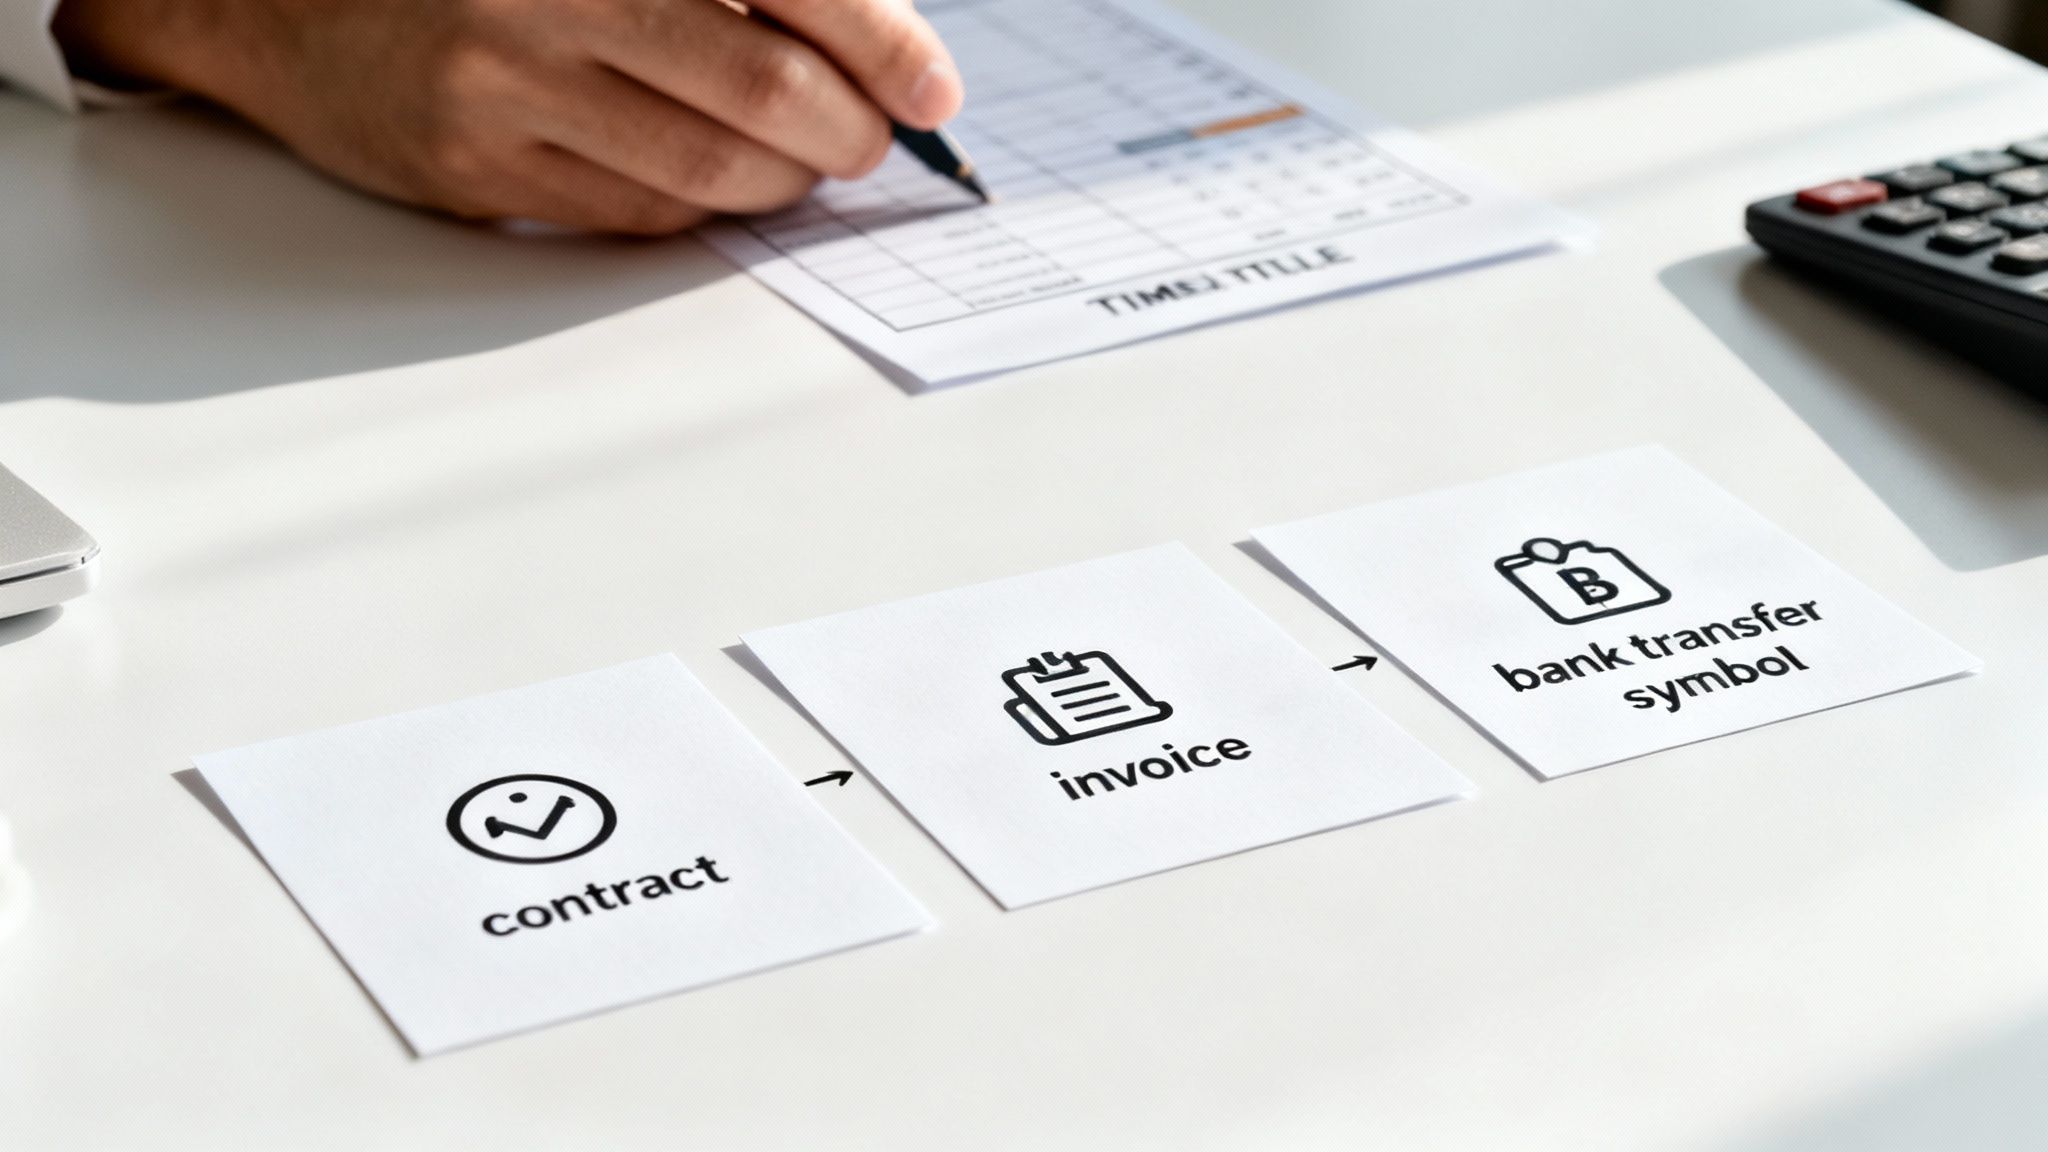
Let's walk through the payment journey step-by-step. Seeing it broken down like this makes the whole thing feel much less daunting, from the moment you sign up to the day your pay lands in your account.
Your Payment Journey Explained
The entire process follows a logical sequence, making sure everyone meets their legal and financial obligations. Think of it as a well-oiled machine, managed entirely on your behalf. Here is how it works in practice.
Join and Onboard: Your first move is to choose a compliant umbrella company and get registered. This usually means providing some ID, your National Insurance number, and your bank details.
Sign Your Employment Contract: Once you're all set up, you'll sign a contract of employment with the umbrella company. This is a key step, it officially makes you their employee, which means you get access to statutory rights like holiday and sick pay.
Submit Your Timesheets: After you have completed the work for your end client, you just need to submit an approved timesheet to your umbrella company. This document confirms the hours you have worked and kicks off the payment cycle.
Invoicing the Client: The umbrella company then raises an invoice to your recruitment agency or the end client, all based on your timesheet. They handle everything from here, including chasing the payment if it is late.
This part alone lifts a huge administrative weight off your shoulders. You can forget about creating and sending invoices yourself, which is a massive time-saver for any busy freelancer.
From Gross Invoice to Net Pay
As soon as the umbrella company receives the money from your client, they get to work on processing your pay. This is where their core payroll function kicks in, making sure all your tax obligations are met correctly and compliantly.
The main job of a compliant umbrella company is to process your earnings through PAYE (Pay As You Earn). This guarantees that the right amount of Income Tax and National Insurance is deducted and paid directly to HMRC for you.
The final steps are just as clear and transparent.
Processing Your Payment: The umbrella company calculates and deducts everything necessary from the gross invoice amount. This includes Income Tax, National Insurance, any pension contributions, and their own margin for the service.
Receiving Your Net Pay: The amount left over, your net pay, is then transferred straight into your personal bank account. You'll also get a detailed payslip that breaks down every single deduction, so you can see exactly where your money has gone.
This streamlined system means you get paid correctly and on time, without the headache of running your own limited company accounts. It provides real peace of mind, knowing your tax affairs are being handled by professionals.
Want an idea of what you could earn? Have a go with our handy UK payroll calculator for a quick estimate.
Weighing Up the Pros and Cons
Figuring out the best way to manage your contracting income is a huge decision, so it pays to look at the full picture. For many, an umbrella company is a brilliant solution, but just like any other service, it has its upsides and its downsides.
To help you figure out if it is the right fit for your career and financial situation, we have laid out a balanced, honest look at what is involved. This should give you the clarity you need to make a choice that truly works for you.
Key Benefits for Freelancers
One of the biggest attractions of using an umbrella company is just how simple it makes everything. They handle all the payroll admin, which means you can get on with your client work without losing sleep over complex tax returns or chasing late payments. It is a massive weight off the shoulders for anyone who would rather avoid the paperwork that comes with running a limited company.
Another major plus is guaranteed compliance. With tricky rules like IR35 catching people out, an umbrella company gives you total peace of mind. They make sure your tax and National Insurance are calculated correctly and paid directly to HMRC through the PAYE system, protecting you from any nasty surprises down the line.
But it is not just about less paperwork. You also get proper statutory employment rights, which can be a real game-changer for freelancers.
- Holiday Pay: Just like a permanent employee, you'll accrue paid time off, so you can take a break without watching your income disappear.
- Sick Pay: If you are too ill to work, you are covered by Statutory Sick Pay (SSP).
- Workplace Pension: You will be automatically enrolled into a government-approved pension scheme, helping you build a pot for the future.
- Continuous Employment: Having a single employer on record provides a consistent employment history, which is a huge help when you are applying for a mortgage or a loan.
These perks provide a safety net that is often missing when you are a freelancer, blending the security of employment with the freedom of contracting.
Potential Drawbacks to Consider
Of course, we need to be straight about the potential downsides, too. For most contractors, the biggest consideration is the cost and what it means for your take-home pay. All compliant umbrella companies keep a slice of your invoice value to cover their costs as your employer.
This is made up of two key parts: their margin and the employer’s statutory costs.
The umbrella company margin is the straightforward fee they charge for doing all the admin. It is usually a fixed weekly or monthly amount and should always be made crystal clear before you sign anything. Here at UmbrellaCompany.com, we help you compare these margins to find a fair price.
The second part, and the one that often causes confusion, is Employer’s National Insurance Contributions (NICs). Because the umbrella is legally your employer, they have to pay this tax. This cost, along with the Apprenticeship Levy, is taken from the money they receive from your client before your own gross pay is worked out.
It is vital to understand that these are not 'hidden fees'. They are legitimate employment costs that have to be paid by someone. Ideally, the gross rate you agree with your agency or client should be uplifted to cover them.
This structure means your take-home pay will be lower than the headline rate invoiced to the client. While that can feel like a negative, it is the trade-off for full compliance and all the employment benefits you get back. For many, that simplicity and security is well worth it.
To help you weigh your options, here is a quick comparison of how an umbrella stacks up against running your own limited company.
Umbrella Company vs Limited Company: A Quick Comparison
The choice often comes down to how much administrative control you want versus how much simplicity you need. This table breaks down the main differences at a glance.
| Feature | Umbrella Company | Limited Company |
|---|---|---|
| Administration | Minimal. Submit your timesheets, and the rest is handled for you. | High. You are responsible for all invoicing, bookkeeping, and tax returns. |
| Tax Compliance | Managed for you through PAYE. Very low risk. | Your responsibility. Higher risk and requires careful management or an accountant. |
| IR35 | A fully compliant solution for contracts inside IR35. | Can be used for inside or outside IR35 contracts, but the director carries the liability. |
| Statutory Rights | Yes. Includes holiday pay, sick pay, and pension. | No. You do not receive these benefits as a company director. |
| Costs | A weekly/monthly margin plus employer’s NICs deducted from the contract rate. | Accountancy fees, company formation costs, and business insurance. |
Ultimately, there is no single "best" answer, it is about what is right for your specific circumstances, your attitude to risk, and how much time you want to spend on admin.
Understanding Your Payslip and Take-Home Pay
It is the question every contractor asks: "what will I actually take home?" It is a fair question, and thankfully, the answer is not a mystery. Getting to grips with your umbrella company payslip is all you need to do to forecast your earnings with confidence.
Once you understand the numbers, you can see exactly how your gross contract rate becomes the net pay that lands in your bank. More importantly, it helps you tell the difference between a compliant, trustworthy umbrella and a shady scheme promising returns that are simply too good to be true.
From Gross Rate to Net Pay
The journey from your total invoice value to your take-home pay involves several standard, legal deductions. This is not unusual; it is the exact same process a permanent employee goes through on a typical PAYE payroll. A compliant umbrella company is just managing this for you.
Your payslip will start with the ‘assignment rate’ or ‘contract rate’. This is the gross amount your umbrella invoices the agency or client for your work. From there, all the necessary employment costs and statutory deductions are taken care of before your net pay is calculated.
Breaking Down the Key Deductions
A proper payslip gives you a transparent, line-by-line breakdown of every single deduction. The layout might look a bit different from one provider to the next, but the core elements will always be there. Knowing what these are is essential.
Here are the main deductions you should expect to see:
- Employer’s National Insurance: As your official employer, the umbrella has to pay Employer’s NICs to HMRC. This is a statutory employment cost, so it is deducted from the gross contract funds.
- Apprenticeship Levy: This is another employer cost. It is a UK tax on larger employers that helps fund apprenticeship training, and it also comes out of the gross funds.
- The Umbrella Margin: This is simply the fee the umbrella company charges for running your payroll and handling the admin. It should always be a clear, fixed amount, either weekly or monthly.
- Employee's National Insurance: This is your personal NI contribution. It is calculated on your gross pay (after the employer costs and margin are deducted) and paid to HMRC on your behalf.
- Income Tax (PAYE): This is the income tax on your earnings, worked out using your personal tax code. Again, the umbrella company pays this directly to HMRC for you.
Once all these deductions have been made, the figure that is left is your net take-home pay.
A Quick Example
To make this a bit clearer, let us walk through a simplified example. Imagine your weekly contract rate is £2,000. The calculation would look something like this:
- Start with the Assignment Rate: £2,000.00
- Deduct Employment Costs: This covers Employer’s NI and the Apprenticeship Levy. Let's say this comes to £230.
- Deduct the Umbrella Margin: We will use a typical margin of £25. This leaves a gross taxable pay of £1,745.
- Calculate PAYE and Employee's NI: Based on that £1,745, your Income Tax and personal NI are worked out. Let's estimate these at £450 and £100.
- Determine Your Net Pay: £1,745 – £450 – £100 = £1,195.
That final £1,195 is what gets transferred to your bank account. Of course, the exact numbers will vary based on your tax code and NI category, but the process is always the same.
A compliant umbrella will always give you a full reconciliation on your payslip, showing every deduction clearly. If your payslip is confusing or key employment costs are missing, it is a massive red flag. It could well be a non-compliant tax avoidance scheme.
For a more personalised estimate, you can explore our detailed guide and tools to calculate your take-home pay for contractors. This will help you get a much clearer picture of your potential earnings on any given contract.
Choosing a Compliant and Trustworthy Umbrella Company
Picking the right umbrella company is one of the most critical decisions you'll make as a contractor. It is not just about your take-home pay; it is about your legal and tax compliance. A solid, trustworthy provider gives you peace of mind, whereas a non-compliant one can land you in serious trouble with HMRC down the road.
This guide will walk you through how to spot a reliable and fully compliant partner. We will cover the key accreditations to look for, why transparent fees are non-negotiable, and the major red flags that should have you running in the other direction.
Look for Official Accreditations
The easiest way to start your search is to check for accreditation from respected UK industry bodies. Organisations like the FCSA (The Freelancer & Contractor Services Association) and Professional Passport conduct intensive audits to make sure their members are hitting the highest standards of compliance.
When you see an FCSA or Professional Passport logo, it is a strong signal that the umbrella company is serious about operating ethically and within UK tax law. It means they have been independently vetted and are committed to protecting the contractors they employ. Do not just take their word for it, though, always double-check their membership on the official FCSA or Professional Passport websites.
Insist on Transparent Fee Structures
Any compliant umbrella company will be completely upfront about its charges. The industry standard is a fixed margin, a set amount deducted from your earnings, either weekly or monthly. It is simple, transparent, and makes it easy to budget.
Be very suspicious of providers that charge a percentage-based fee. This can get unnecessarily expensive on higher-paying contracts and often makes things less clear. A fixed margin means you know exactly what you are paying for, with no hidden costs or nasty surprises on your payslip.
This chart shows how your contract rate is broken down into various deductions before you get your final net pay.
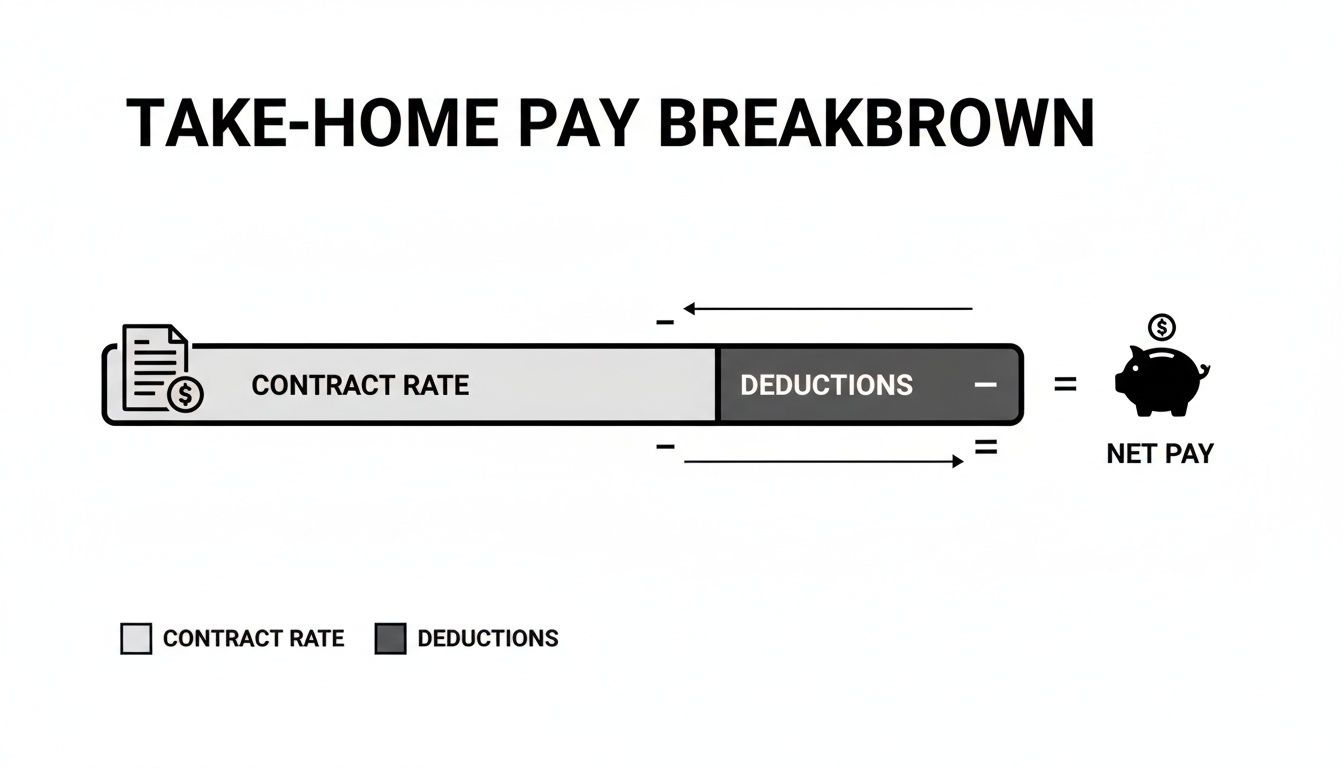
Understanding this flow is crucial for spotting providers whose figures just do not add up.
Red Flags to Avoid
Unfortunately, the market has its share of non-compliant schemes that try to lure freelancers with unrealistic promises. HMRC is actively cracking down on these arrangements, and getting involved, even accidentally, can leave you with a massive future tax bill.
Here are the critical warning signs to watch out for:
- Promises of ridiculously high take-home pay: Any company advertising that you can keep 85-90% of your contract income is almost certainly a tax avoidance scheme. Once compliant PAYE deductions are made, a realistic take-home figure is usually around 60-75%.
- Complex payment arrangements: Be wary of any structure involving loans, annuities, or payments being routed through offshore accounts in places like the Isle of Man or Jersey. Your income should be paid as a straightforward salary.
- Confusing or incomplete payslips: Your payslip must clearly show every deduction, including employer’s and employee’s National Insurance, PAYE tax, and the umbrella’s margin.
- Lack of accreditation: A company that refuses to join or fails audits from bodies like the FCSA is a huge concern.
Using a trusted comparison tool, like ours here at UmbrellaCompany.com, makes this whole process much simpler. We only list accredited and vetted providers, so you can compare your options with confidence. For even more detail, check out our guide on what makes a good umbrella company.
Your Top Questions Answered
To help you decide if an umbrella company is the right move, we have pulled together the questions our team receives most often. Let's get you some straight, practical answers so you know exactly where you stand.
We'll tackle the big ones: what the deal is with expenses, why umbrellas are the go-to for 'inside IR35' contracts, and just how fast you can get up and running.
Can I Claim Expenses Through an Umbrella Company?
This is a big one, and the short answer is: probably not for your daily commute. The rules around expenses got much tighter with the introduction of the 'Supervision, Direction, or Control' (SDC) legislation.
In simple terms, SDC is a test to see if your client has control over how, where, and when you do your work. If they do, HMRC sees you as being in a similar position to a permanent employee. That means your daily travel to the office and your lunch are not tax-deductible, just as they would not be for a regular staff member. Any compliant umbrella company will carry out an SDC assessment to keep everything above board.
Why Is an Umbrella Good for Inside IR35 Contracts?
For any contract that falls 'inside IR35', an umbrella company is almost always the simplest and safest path. The IR35 rules themselves demand that for that specific job, you must be taxed just like an employee. An umbrella company is set up to do exactly that by processing all your earnings through PAYE.
This creates a neat, compliant solution that protects you, your recruitment agency, and the end client. It takes the headache and risk of a wrong IR35 decision off the table, providing a secure and legally sound way to get on with the job.
How Quickly Can I Get Set Up?
One of the best things about using an umbrella is the speed. The sign-up process is incredibly quick, meaning you can say "yes" to a contract today and be ready to start tomorrow without any fuss. Some providers can have you fully registered and ready to go in under an hour.
It is this efficiency that makes umbrellas so popular, especially as agencies are increasingly limiting their list of approved suppliers to manage their own risks. Research into UK contracting trends backs this up, showing that contractors really value this rapid setup and the employment protections that come with it. You can dig deeper into the UK market trends on 6wresearch.com.
At its core, using an umbrella company for freelancers gives you the best of both worlds: a lightning-fast start combined with the security blanket of being an employee. It strips away the admin and ensures you are paid properly from day one.
In the fast-moving world of contracting, being able to accept a role and start almost immediately is a massive advantage.
Ready to find the right partner for your next contract? At UmbrellaCompany.com, we make it easy to compare accredited, compliant providers in just a minute.


