


Picking the right type of business structure is one of the most significant decisions you will make when starting out. It is not just a box-ticking exercise; this decision affects everything you do, from how much tax you pay to whether your personal assets are on the line. It fundamentally shapes your business's journey from day one.
In this guide, we will walk you through the main options to help you understand which structure best suits your professional goals.
Why Your Business Structure Matters
Think of your business structure as the vehicle you choose for your professional journey. A scooter is great for nipping around the city (quick, cheap, and easy). That’s your sole trader setup. But if you are planning on hauling heavy goods across the country, you will need a lorry. That’s your limited company, a robust framework built for growth and protection.
Your choice lays the legal and financial foundation for everything ahead. It dictates how you are taxed, how much paperwork you will have, and crucially, who pays the bill if things go wrong. Getting this right from the start can save you a world of headaches and costly changes later on.
Understanding the UK Business Landscape
The UK private sector is built on the back of small and medium-sized businesses (SMEs). They are the lifeblood of the economy. In fact, official figures show that 99.8% of the 5.5 million firms in the UK are SMEs, with sole traders and limited companies leading the way. This demonstrates how accessible it is to get started.
This guide will walk you through the main options, including:
- Sole Trader: The most straightforward path, where you and your business are one and the same in the eyes of the law.
- Limited Company: A separate legal entity that shields your personal assets from business debts.
- Partnership: The classic setup for two or more people going into business together.
- Umbrella Company: A popular employment model for contractors who want simplicity and peace of mind.
The Impact on Your Finances and Liability
Each structure has a completely different impact on your finances. As a sole trader, you pay Income Tax on your profits. Simple. A limited company, however, pays Corporation Tax on its profits, and you then decide how to pay yourself through a mix of salary and dividends. This also changes how you calculate your turnover, which is important when you are nearing the VAT registration threshold in the UK.
Choosing a business structure is a balancing act between risk and reward. Being a sole trader is incredibly easy to manage, but it leaves your personal finances exposed. A limited company protects you, but it comes with a heavier admin burden.
Our goal here is to give you a crystal-clear picture of these trade-offs. By exploring each type of business structure, we will help you pick the one that truly fits your ambition, your appetite for risk, and your vision for the future.
Operating as a Sole Trader
For many people starting out on their own in the UK, becoming a sole trader is the quickest and most straightforward way to get up and running. Think of it this way: your business is simply an extension of you. Legally, there is no separation between you and the business, which makes getting started incredibly simple.
There's a good reason this is the UK's most popular business structure. Sole traders make up a massive 56% of all businesses, with over 3 million people taking this route. The vast majority of these (around 2.88 million) do not have any employees, which highlights how well-suited it is for solo freelancers and contractors.
Because the setup is so simple, you avoid all the incorporation paperwork that comes with other structures. You are your own boss in the truest sense, with total control over every decision and, of course, all the profits.
Your Legal and Tax Responsibilities
To start trading as a sole trader, your main legal task is to register for Self Assessment with HMRC. This is the system you will use to report your income and expenses each year. Once that is done, it is up to you to keep a clear and accurate record of your finances.
Your tax duties are also fairly direct. You will be paying:
- Income Tax on all of your business profits.
- National Insurance Contributions (NICs), which are specifically Class 2 and Class 4 for the self-employed, funding things like your State Pension.
Keeping on top of this means filing a tax return every year. Staying organised and knowing the key dates is crucial if you want to avoid any penalties. We have put together a guide to help you get to grips with the self-employed tax return deadlines.
The Critical Concept of Unlimited Liability
So, what's the catch? The biggest trade-off for all this simplicity is something called unlimited liability. Since you and your business are one and the same in the eyes of the law, you are personally responsible for any debts the business accumulates. This means your personal assets, like your house or your savings, could be at risk if the business cannot pay its bills.
This is the single most important point to understand. While being a sole trader gives you maximum freedom with minimum fuss, it also comes with the highest level of personal financial risk. It's often a great fit for low-risk ventures where the chances of getting into significant debt are slim.
A freelance writer or graphic designer, for example, probably does not face much financial risk. But if you are running a business that needs expensive equipment or has to rent a workshop, that lack of protection might become a serious worry.
Is Being a Sole Trader Right for You?
Ultimately, deciding whether to be a sole trader is a balancing act between simplicity and risk. It is an excellent choice if you are just starting out, testing a new business idea, or working in an industry with very low overheads.
The admin is light, and you get to keep all the profits once the taxman has had his share. But as your business grows, or if you start taking on bigger, riskier contracts, that unlimited liability could become a major drawback. You need to weigh that personal risk carefully against the undeniable ease of getting your venture off the ground.
Setting Up a Limited Company
When you are serious about growth, credibility, and building a business for the long haul, forming a limited company is often the smartest route. Think of it as giving your business its own legal personality, completely separate from you. It is this legal wall that provides the structure’s biggest perk: limited liability.
What does that really mean? It means your personal finances are shielded from your business's debts. If the company hits a rough patch financially, your home, car, and personal savings are kept safe. This protection is a massive draw, and it is a huge reason why this is such a popular type of business structure in the UK.
In fact, private limited companies are the undisputed favourite, making up over 95% of all corporate bodies on the Companies House register. That number alone shows just how much founders value robust liability protection without the headaches of a publicly-traded firm.
The Incorporation Process
Setting up, or ‘incorporating’, a limited company means officially registering your business with Companies House, the UK’s official registrar. This is the step that makes your business a distinct legal entity.
To get incorporated, you will need to have a few key details ready:
- A unique company name: It cannot be the same as, or too close to, an existing company name on the register.
- A registered office address: This is your company's official address and will be public information.
- At least one director: This is the person responsible for running the company.
- At least one shareholder: This is an owner of the company, holding shares.
For most contractors and small business owners running a Personal Service Company (PSC), the director and shareholder are the same person. Once Companies House approves your application, it will issue your Certificate of Incorporation, and your business is officially born.
Directors and Shareholders Explained
It is crucial to get your head around the roles within a limited company. As a director, you are legally responsible for the company's management. Your duties include making sure the company follows the law, filing annual accounts, and always acting in the company’s best interests.
A shareholder owns the company through their shares. They have a right to a slice of the profits, usually paid out as dividends. In a small limited company, it is completely normal for the director to own 100% of the shares, making them both the manager and the sole owner.
The separation of these roles, even if one person holds both, is what underpins the whole limited company structure. It creates a formal framework that instantly boosts your credibility with clients, suppliers, and banks.
Navigating Tax as a Limited Company
The tax situation for a limited company is very different from being a sole trader. The company itself pays Corporation Tax on its annual profits. HMRC sets the rate, and this tax is paid before any money is distributed to the owners.
Once the company has paid its tax bill, the owners can pay themselves. This usually happens with a savvy mix of two things:
- A small salary: Often set at a tax-efficient level, this is a business expense and is subject to PAYE tax and National Insurance.
- Dividends: These are payments made to shareholders out of the company’s after-tax profits.
This salary-and-dividend split is the go-to strategy for tax efficiency. If you want to understand the details, our guide on how to pay yourself dividends has all the practical advice you will need. This approach gives you far more flexibility in your financial planning, but it comes with a trade-off: you have to be disciplined with your record-keeping and stay on top of your obligations to HMRC.
Comparing Your Business Structure Options

Trying to pick the right type of business structure can feel complex. Each one comes with its own level of risk, tax quirks, and admin headaches, so it is crucial to understand how your main options stack up against each other.
This comparison will focus on the three most common routes for UK contractors and freelancers: the sole trader, the limited company (often called a Personal Service Company or PSC), and the umbrella company. Laying out the key differences side-by-side should help you see which one genuinely fits your work style and financial goals.
UK Business Structure Comparison: Sole Trader vs Limited Company vs Umbrella Company
Let's break down the three main choices for contractors and freelancers. This table gives you a quick, at-a-glance view of how they compare on the things that matter most: liability, tax, admin, and take-home pay potential.
| Feature | Sole Trader | Limited Company (PSC) | Umbrella Company |
|---|---|---|---|
| Legal Status | You and the business are legally the same. | A separate legal entity from you, the owner. | You become an employee of the umbrella company. |
| Liability | Unlimited. Your personal assets (home, car) are at risk from business debts. | Limited. Your personal assets are protected from business debts. | No personal business liability. The umbrella company carries all the financial risk. |
| Admin & Paperwork | Low. Just an annual Self Assessment tax return. | High. Requires annual accounts, corporation tax return, confirmation statement, and director duties. | Very Low. The umbrella handles all invoicing, payroll, tax, and NI contributions for you. |
| Tax Efficiency | Moderate. You pay Income Tax and Class 2 & 4 National Insurance. | Potentially High. Can be very tax-efficient through a mix of salary and dividends (if outside IR35). | Lower. You are taxed as an employee (PAYE), which is less efficient than a PSC outside IR35. |
| IR35 | Less common but the same employment status principles apply. | Crucial. The structure is most beneficial when working 'outside IR35'. | Ideal for 'inside IR35' work. It's the simplest and most compliant option for inside IR35 contracts. |
| Best For | Low-risk freelance work, side hustles, or those just starting out. | Career contractors with long-term, 'outside IR35' contracts looking to maximise their income. | Contractors on short-term or 'inside IR35' contracts who want minimal admin and full compliance. |
As you can see, there is no single "best" option; it all depends on your individual circumstances. A limited company might offer the highest take-home pay, but it comes with a heavy admin burden and significant IR35 risk. On the other hand, an umbrella company provides peace of mind and simplicity, but at the cost of some tax efficiency.
Liability and Personal Risk
Your personal liability is probably the biggest and most important difference between these structures. It all comes down to where responsibility lies if the business gets into debt.
- Sole Trader: You have unlimited liability. This is the critical point to understand. There is no legal wall between you and your business, which puts your personal assets (like your home or savings) at risk if things go wrong.
- Limited Company: Here, the company is a completely separate legal entity. This gives you limited liability, a core benefit that shields your personal finances from any business debts.
- Umbrella Company: As an employee of the umbrella company, you carry no personal business liability whatsoever. The umbrella organisation takes on all financial risks and responsibilities.
This factor alone is often what pushes people towards a structure with more personal protection, especially if they are working in higher-risk sectors or signing big-money contracts.
Tax and Administrative Workload
The amount of paperwork and the way you handle your taxes varies massively. You can choose simplicity, but it might cost you in tax efficiency, while more complex setups can open up better tax planning opportunities.
A sole trader has the lightest admin load by far, just needing to file an annual Self Assessment tax return. A limited company director, however, has a much bigger job on their hands. You are looking at filing annual accounts with Companies House and a company tax return with HMRC, among other duties. Our detailed comparison of an umbrella company vs limited company explores these admin differences in more detail.
Picking a business structure is often a trade-off. Are you prepared to take on more admin for potentially higher earnings, or would you rather have a hands-off approach that lets you just focus on the job?
Working through an umbrella company offers the ultimate simplicity. You are their employee, so they handle all your tax and National Insurance through PAYE, taking the entire administrative headache off your plate.
IR35 and Compliance Considerations
For any contractor, the off-payroll working rules (IR35) are a massive factor in this decision. These rules are designed to determine if you are a genuine independent business or a ‘disguised employee’ for tax purposes.
If your contract falls inside IR35, running it through a limited company suddenly becomes a lot less tax-efficient, because you have to pay tax and NICs much like a regular employee. In this situation, an umbrella company is almost always the most straightforward and compliant path. It ensures the right tax is paid without you getting bogged down in complex payroll calculations.
If you are confident your work is consistently outside IR35, a limited company can offer real tax advantages. The catch? The responsibility for proving your status rests firmly on your shoulders if HMRC ever investigates. The sole trader route is less common for contracts that get assessed under IR35, but the same rules around employment status still apply. This makes understanding your IR35 position a vital first step.
Not Just a One-Person Show: Exploring Partnerships and Other Structures
While going it alone as a sole trader or setting up a limited company are by far the most common routes, they are not the only options. The UK business landscape offers a range of choices designed for different ambitions, especially if you are teaming up with others or have a social mission at your core.
Before you make a decision, it pays to look beyond the obvious choices. Let's look at a few of the other powerful frameworks you can use.
The Ordinary Partnership
Want to go into business with someone else? The simplest, most straightforward way is to form an Ordinary Partnership. Think of it as the sole trader model, but built for two or more people. In short, all the partners get to share in the profits. The catch? They also share all the liabilities.
This is where you need to be careful. Just like a sole trader, every partner in an ordinary partnership has unlimited liability. This is a big deal. It means you are not just responsible for your share of the business's debts, you are personally liable for all of them. If your partner makes a serious mistake, your own personal assets could be on the line to cover the fallout.
Here is the breakdown of an ordinary partnership:
- Shared Profits: The earnings are split between all the partners.
- Joint Responsibility: Everyone is jointly responsible for the business's decisions and its debts.
- Self-Employed Status: Each partner has to register as self-employed with HMRC and file their own Self Assessment tax return.
This structure can work well when trust is rock-solid and the financial risks are low. But that unlimited liability is a major drawback, pushing many collaborators to look for something with more protection.
Limited Liability Partnerships (LLPs)
For professionals who want the best of both worlds (the flexibility of a partnership without the personal risk) the Limited Liability Partnership (LLP) is a brilliant hybrid. It gives you the operational freedom of a classic partnership but with the protective armour of a limited company.
An LLP is its own separate legal entity. This means the business itself is responsible for its debts, not the individual partners. It is a hugely popular choice for professional service firms like accountants, solicitors, and architects, where the threat of a major professional negligence claim is always present.
An LLP creates a vital safety net. It shields each partner's personal wealth from the business's financial problems and, crucially, from the consequences of another partner's actions. It makes collaborative ventures much more secure.
Of course, this extra protection comes with more paperwork. Unlike an ordinary partnership, an LLP must be registered at Companies House. You will also need to file annual accounts, which means your financial details will be on the public record.
Thinking Outside the Box: Specialised Structures
Beyond partnerships, the UK also offers a few specialised structures for very specific missions. The most prominent is the Community Interest Company (CIC). A CIC is a special type of limited company built for social enterprises: businesses that want to pour their profits and assets back into doing good.
While a CIC aims to be profitable, its primary goal is to benefit the community, not to enrich shareholders. It's the perfect fit for an organisation with a clear social purpose that wants to legally lock in its assets for the public good. They are even overseen by the CIC Regulator to ensure they stick to their social mission. Exploring these niche options is the key to finding a structure that not just works for your business, but truly reflects its values.
Making the Right Choice for Your Business
We have walked through the different business structures, so now it is time to pull it all together. Choosing the right setup is not about copying what someone else did; it is about what fits your goals, your financial situation, and how much paperwork you are willing to manage.
Think of it as finding the sweet spot between risk, reward, and responsibility. To get this right, you need to ask yourself a few honest questions about where you are headed. Answering them now will give you the clarity you need to build a solid foundation from day one.
Key Questions to Guide Your Decision
Before you register anything, take a moment to think about your plans. Your answers will steer you towards the best option, whether you are a freelance creative, a seasoned contractor, or just starting out on your own.
Start by considering these critical points:
- What are your expected earnings? If your income is likely to be modest or variable, the simplicity of being a sole trader is hard to beat. But for higher earners, the tax planning opportunities of a limited company become very appealing.
- What is your industry's risk level? If there is any chance your work could lead to financial disputes or professional negligence claims, limited liability is essential. This makes a limited company or an LLP a much safer bet than being a sole trader.
- Do you have growth ambitions? A limited company is practically built for growth. It projects a more professional image, which can be a real help when trying to land bigger clients. Plus, its structure makes it far easier to bring in investors or shareholders later on.
- How much admin can you handle? Be realistic about the time you can dedicate to paperwork. If you would rather have a completely hands-off approach, an umbrella company takes care of all that for you. A limited company, on the other hand, demands diligent record-keeping and official filings.
The Impact of IR35 on Contractors
For contractors, the IR35 off-payroll working rules add another important consideration. These regulations exist to determine if you are genuinely self-employed or, for tax purposes, a ‘disguised employee’. Your IR35 status has a huge say in which business structure is the most sensible and compliant choice.
If your contracts are likely to fall inside IR35, you will be taxed just like an employee. In this situation, using an umbrella company is by far the most straightforward, risk-free option. It guarantees you are fully compliant with HMRC, removing any personal tax risk and the administrative headache that comes with it.
Choosing an umbrella company for inside IR35 work provides complete peace of mind. It lets you focus purely on your contract, safe in the knowledge that all your tax and National Insurance are being handled correctly.
On the flip side, if you are confident your work will consistently fall outside IR35, a limited company (often called a PSC) is still a very tax-efficient way to operate. It gives you more control over your finances, letting you draw income as a mix of salary and dividends. The catch? The responsibility for proving your IR35 status lands squarely on your shoulders, which means careful contract reviews and staying on top of your compliance.
Your Next Steps
At the end of the day, the best type of business structure is the one that supports your ambitions while shielding you from unnecessary risk. A sole trader offers simplicity, a limited company provides protection and a path to growth, and an umbrella company delivers hassle-free compliance for contractors.
Take your time to weigh these factors. If you are a contractor looking for a simple, compliant solution, it is well worth exploring your options. Making an informed choice now sets your business on the right track for a secure and successful future.
Still Have Questions?
Choosing the right business structure can feel like a maze. Let's tackle some of the most common questions that arise, giving you clear, straightforward answers to help you find your way.
If you're a visual thinker, this flowchart can help. It maps out the decision based on what matters most to you: growth, admin, or risk.
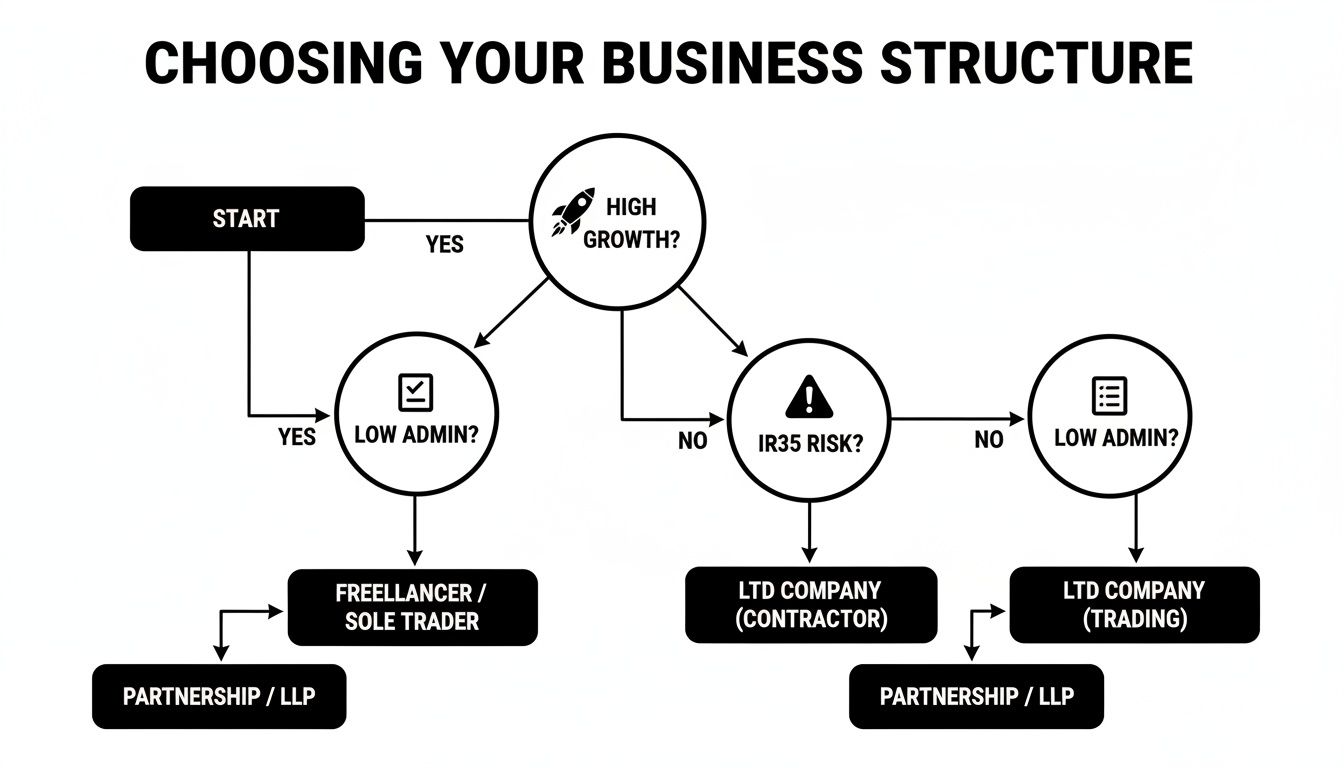
As you can see, if ambitious growth is your main goal, a limited company is usually the best path. On the other hand, if you just want to keep admin to a minimum, a sole trader setup or an umbrella company makes a lot more sense.
Can I Change My Business Structure Later On?
Yes, absolutely. Your business is not set in stone, and neither is its structure. It is incredibly common for a business to evolve over time.
Many people start out as a sole trader. It is simple, cheap, and lets you test the waters with minimal fuss. But as profits climb and the business finds its feet, switching to a limited company often becomes the logical next step. This move, called 'incorporation', introduces limited liability and opens up smarter ways to manage your tax.
Just remember, while you can always change, it is a formal legal process. It is best to get it right from the start for your immediate needs.
What Is IR35 and How Does It Affect My Choice?
IR35 is a major consideration for contractors. Officially known as the 'off-payroll working rules', it is tax legislation designed to identify contractors who are essentially employees in all but name.
If your contract is judged to be ‘inside IR35’, you have to pay tax and National Insurance much like a permanent employee would.
This completely changes the situation. For contracts that fall inside IR35, running your own limited company suddenly becomes far less tax-efficient. This is precisely why so many contractors in this position choose to work through an umbrella company. It is the most compliant and headache-free way to handle your tax obligations.
For contractors, your IR35 status is often the single biggest factor in this decision. An umbrella company takes the compliance burden off your shoulders for inside IR35 work, while a limited company is better suited for projects that are genuinely outside IR35.
Is an Umbrella Company a Business Structure?
This is a really common point of confusion, so let's clear it up. An umbrella company is not a type of business structure that you set up and own, like a limited company. Think of it more as a model of employment.
When you join one, you become an employee of that umbrella company. They handle everything: signing contracts with your agency or client, processing your payroll, and sorting all the tax deductions. You just do the work and submit your timesheets.
In return for a small margin, you get the flexibility of contracting with the simplicity of being an employee. For many UK contractors, it's the perfect hassle-free option.
At UmbrellaCompany.com, we specialise in helping you find a reliable, FCSA-accredited umbrella company that fits your needs. Use our comparison tool to find a compliant partner in minutes. Find your ideal match at https://umbrellacompany.com.


