


Salary sacrifice is a smart, HMRC-compliant way to structure your pay. In simple terms, you agree to take a slightly lower gross salary in exchange for your employer paying for a non-cash benefit on your behalf, most often, increased pension contributions.
The real win? This simple switch lowers your taxable income, which means you pay less tax and National Insurance. Your umbrella company saves money too, and a good one will pass those savings straight back to you. This guide will explain how it works, the benefits, and what you need to know.
How Salary Sacrifice Works for UK Contractors
Think of salary sacrifice as a powerful financial planning tool, especially if you’re a contractor working inside IR35. Instead of getting your full day rate paid as cash (and then paying for things like your pension out of your taxed income), you formally agree to a lower contractual salary.
In return, your employer, in this case, your umbrella company, pays the difference directly into something else for you.
For contractors, the most common and effective use of a salary sacrifice UK scheme is to boost your pension. It’s a completely legitimate way to make your money work much harder for your retirement.
The process is straightforward: you accept a reduced salary, and the amount you've "sacrificed" goes directly into your pension pot before any tax is taken off.
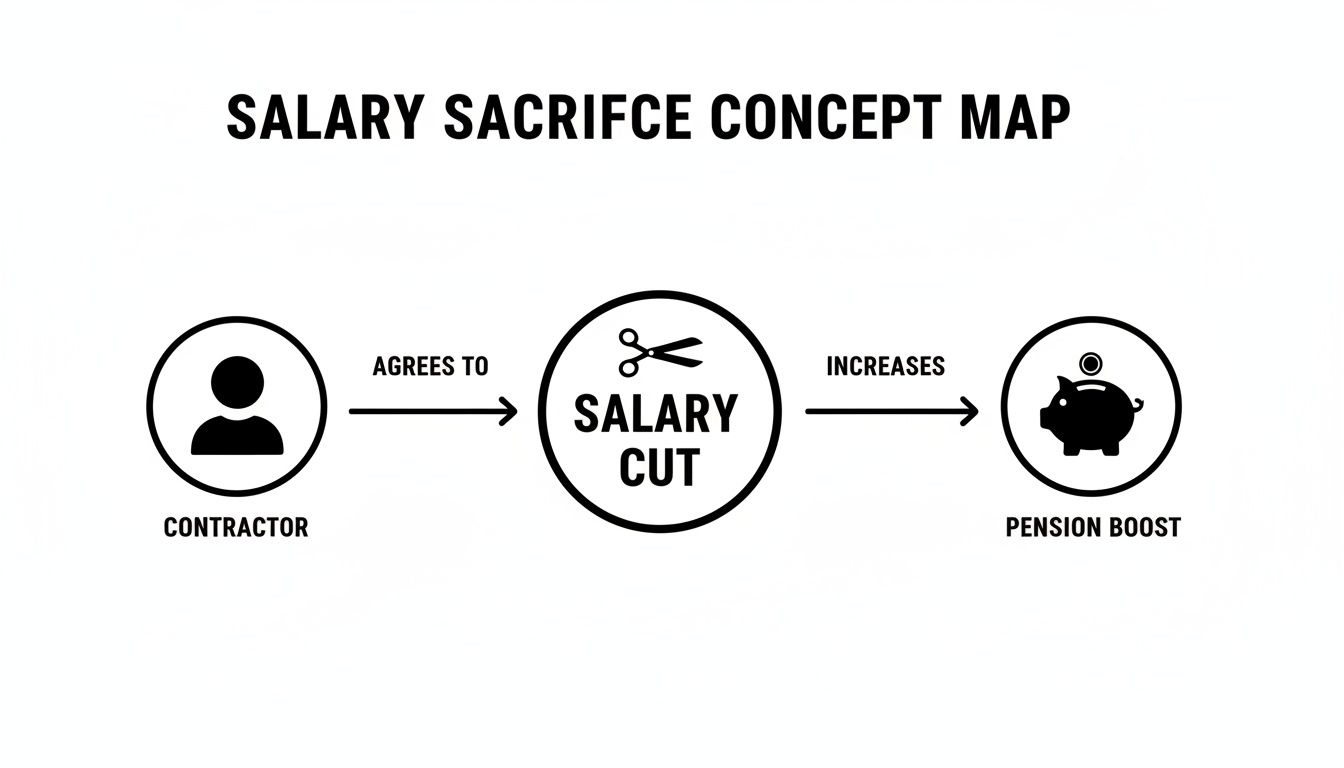
As you can see, it's a direct swap of salary for a pension top-up. That's the key to unlocking the tax savings.
To give you a quick overview, here are the core components of a salary sacrifice arrangement for contractors.
Salary Sacrifice at a Glance
| Aspect | Description |
|---|---|
| The Agreement | You formally agree to a lower gross salary. This must be a change to your employment contract. |
| The Benefit | In exchange, your umbrella company provides a non-cash benefit, typically pension contributions. |
| Tax Impact | Your taxable income is reduced, so you pay less Income Tax and employee National Insurance. |
| Employer Savings | The umbrella company saves on employer's National Insurance contributions (NICs). |
| The Pass-Back | A compliant umbrella passes their NICs savings back to you, adding it to your pension contribution. |
This setup is what makes salary sacrifice so much more efficient than just making personal pension payments from your bank account.
A Practical Example
Let's walk through the numbers. Say you’re a contractor and your assignment rate generates a gross income of £5,000 for the month.
- You decide to sacrifice £1,000 of that into your pension.
- Your official, taxable salary immediately becomes £4,000.
- This means you only pay Income Tax and employee NICs on £4,000, not the full £5,000.
- That £1,000 goes straight into your pension pot, completely untouched by tax.
- Now for the clever part. Your umbrella company also saves on its employer's NICs bill. It would have paid 13.8% on that sacrificed £1,000, which works out to £138.
A fair and transparent provider will then add that £138 saving directly into your pension.
So, for a £1,000 reduction in your gross pay, your pension pot actually gets a total boost of £1,138. This is how you can rapidly accelerate your retirement savings in a way that’s simply not possible through standard post-tax contributions.
This whole process is handled through the standard PAYE system, keeping everything above board with HMRC and giving you total peace of mind. To understand the underlying mechanics better, you can read our detailed guide on how PAYE works for contractors.
The Financial Benefits of a Salary Sacrifice Scheme
The main reason to look at a salary sacrifice arrangement is the financial upside. By cleverly restructuring your pay, you can legally reduce your tax bill and give your long-term savings, especially your pension, a serious boost.
The core benefit of a salary sacrifice UK scheme is the savings on National Insurance Contributions (NICs) for both you and your employer. When you sacrifice part of your salary, your gross pay is lower, meaning you pay less in employee's NICs. At the same time, your umbrella company saves on the employer’s NICs it would have paid on that sacrificed amount.
A compliant umbrella company will pass this employer NIC saving directly on to you. This is usually added straight into your pension pot, creating a substantial uplift you simply don't get with standard pension contributions made from your post-tax income.
Maximising Your Pension Contributions
Let's run through a real-world example. Imagine you’re a contractor on a contract rate that generates a gross taxable income of £60,000 a year. You decide to sacrifice £500 per month (£6,000 per year) into your pension.
Without Salary Sacrifice: If you made a personal contribution of £500 from your net pay, it would get tax relief, but you’d still have paid full NICs on your entire £60,000 salary. The total going into your pension is just the £500.
With Salary Sacrifice: Your taxable salary drops to £54,000. This saves you employee's NICs on the £6,000 you sacrificed. More importantly, the umbrella company saves employer's NICs (currently 13.8%) on that same £6,000, which works out to £828 for the year.
A good umbrella adds this £828 directly into your pension. So, a £6,000 salary sacrifice actually results in a total pension contribution of £6,828. That’s an instant 13.8% bonus that powerfully accelerates your retirement savings. It's a key part of finding a tax-efficient way to pay yourself in the UK.
Widespread Adoption in UK Organisations
Salary sacrifice has become a go-to for pension planning, and recent tax changes have made it even more attractive for contractors. Its popularity is no secret; a recent survey found that 77% of organisations are now using salary sacrifice arrangements. This is especially relevant for contractors working through umbrella companies, who are often inside IR35 and looking for ways to optimise their earnings.
While exploring your options, it's also worth understanding the advantages of being a limited company, as many contractors use this structure for tax efficiency. For those inside IR35, however, salary sacrifice through an umbrella is often the most effective route.
Beyond Pensions: Other Salary Sacrifice Benefits
While pensions usually offer the biggest win for contractors, the salary sacrifice mechanism can be used for other approved benefits, which also come with tax and NIC savings.
Salary sacrifice allows you to pay for certain benefits from your pre-tax income. This makes items more affordable by reducing the amount of your salary that is subject to tax and National Insurance.
Some other popular options include:
- Cycle to Work Schemes: You can get a brand-new bike and accessories for your commute, paying for it from your gross salary and saving up to 42% on the retail price.
- Ultra-Low Emission Vehicles (ULEVs): Often called an EV scheme, this lets you lease a new electric car through your gross pay, taking advantage of very low Benefit-in-Kind (BIK) tax rates.
- Workplace Nurseries: If your umbrella provides access, you can pay for childcare with pre-tax income, which can lead to significant savings.
For most UK contractors, though, especially those focused on building long-term wealth, pension salary sacrifice remains the most powerful and accessible choice. It directly turns tax savings into investment growth, giving you a secure and compliant path to a healthier financial future.
Understanding the Risks and Potential Downsides
While a salary sacrifice UK scheme offers some brilliant tax efficiencies, it’s not a one-way street. It's a formal change to your employment terms, and agreeing to a lower contractual salary can have knock-on effects elsewhere in your financial life.
Our aim isn't to put you off, but to give you a clear, balanced view. Once you understand the potential trade-offs, you can make a smart decision that works for both your immediate needs and your long-term goals.
Impact on Borrowing and Mortgages
One of the biggest points to consider is how a reduced salary looks to lenders. Mortgage providers, especially, base their lending decisions on the gross income shown on your payslips and P60.
When you use salary sacrifice, your official contractual salary is lower. For instance, if your assignment rate brings in £60,000 but you sacrifice £10,000 into your pension, your P60 will show a salary of £50,000. This is the figure most lenders will plug into their affordability calculator.
It's vital to be proactive here. If you're planning to apply for a mortgage or remortgage soon, we always recommend speaking to a contractor-friendly mortgage adviser before you commit to a salary sacrifice arrangement. They know the market and can point you to lenders who understand how contractor pay works and might look at your gross assignment rate instead.
Effects on Statutory Payments
Another key area affected is your entitlement to statutory payments. These are government-mandated benefits calculated from your average earnings over a set period. Because salary sacrifice lowers your official earnings, it can also reduce what you receive.
Key statutory payments to be mindful of are:
- Statutory Sick Pay (SSP): If you're off work ill for a long time, SSP is calculated from your average weekly earnings. A lower, sacrificed salary could mean a smaller weekly payment.
- Statutory Maternity, Paternity, or Adoption Pay: These are also calculated from your average earnings. A salary sacrifice scheme active during the qualifying period will reduce the amount you get during your leave.
- Redundancy Pay: In the unlikely event of a statutory redundancy, your payment is based on your final weekly contractual salary. A sacrificed salary would lead to a smaller redundancy pay-out.
Other Financial Considerations
Beyond big-ticket items like mortgages, a lower contractual salary can also affect other financial products. Many contractors hold life insurance or critical illness cover to protect their families.
These policies are often based on a multiple of your annual salary. A policy that offers cover of '4x salary', for example, would provide a smaller lump sum if your contractual salary is reduced through sacrifice. It's always a good idea to check the terms of any insurance policies you have to see how they might be affected.
Making the right choice means weighing the powerful long-term pension benefits against these potential short-term impacts. With some careful planning and professional advice, you can usually manage these risks and make sure a salary sacrifice UK scheme works for your specific situation.
How Salary Sacrifice and IR35 Rules Fit Together
For contractors, the words IR35 and tax efficiency are part of daily life. So, when salary sacrifice enters the conversation, a common question pops up: how does it work with IR35? The relationship is actually very straightforward.
Salary sacrifice is a fully compliant and legitimate option, but it's available only to contractors working ‘inside IR35’ through an umbrella company. This is a critical point to grasp from the outset.
When your contract falls inside IR35, HMRC views you as an employee for tax purposes. This means your income is handled through the PAYE system, just like any permanent staff member. It’s this very status that makes you eligible for PAYE-based benefits, including salary sacrifice.
The Clear Line Between Inside and Outside IR35
Your IR35 status is the starting block for everything. The rules and opportunities are completely different depending on which side of the line you fall.
Inside IR35: You're taxed at source, just like an employee. This is why salary sacrifice (especially for pensions) becomes one of the only HMRC-approved tools you have left to improve your tax efficiency. It allows you to legally reduce the amount of income that gets taxed.
Outside IR35: If you're working outside IR35, you're running a genuine business, usually through your own limited company (a Personal Service Company, or PSC). In this setup, you typically pay yourself a small salary and take the rest as dividends. Salary sacrifice isn't used here; instead, you manage tax efficiency through things like company pension contributions and careful dividend planning.
If you need to get to grips with the details, our guide explaining IR35 for contractors breaks it all down.
Why Salary Sacrifice Is a Lifeline for Inside IR35 Contractors
The off-payroll working rules changed the game. Before the reforms, more contractors could work outside IR35, giving them greater control over their tax affairs via their limited company. Now, many find their contracts are automatically deemed inside IR35, pushing them onto a standard payroll and stripping away most tax planning options.
For contractors working inside IR35, salary sacrifice isn't just a perk; it's a vital financial tool. It's one of the most effective and compliant ways to keep more of your earnings by turning part of your gross pay into tax-free pension contributions before HMRC even sees it.
This is exactly where we come in. At UmbrellaCompany.com, we help contractors navigate these rules correctly. We make sure any salary sacrifice UK arrangement is set up properly within the PAYE framework, giving you a powerful, compliant way to build your long-term savings.
A Practical Scenario for an Inside IR35 Contractor
Let’s look at a real-world example. A contractor named Alex finds out his new project is inside IR35, so he has to use an umbrella company. His day rate works out to a gross monthly income of £5,500.
Without salary sacrifice, that entire £5,500 is hit by PAYE, meaning Income Tax and National Insurance are deducted from the full amount.
But Alex is smart. He uses a salary sacrifice scheme through his umbrella and chooses to put £1,200 a month into his pension. Instantly, his taxable income drops to £4,300. Not only does this lower his immediate tax and NICs bill, but it also creates an employer NICs saving of £165.60 (13.8% of £1,200). As a compliant umbrella, we add that saving directly to his pension pot.
The outcome? For a £1,200 reduction in his gross pay, Alex’s pension gets a total top-up of £1,365.60. This shows that even when working inside IR35, you can still take meaningful steps to make your money work harder for you.
Choosing a Compliant Umbrella Company for Salary Sacrifice
Making your salary sacrifice UK strategy a success really comes down to choosing the right partner. A compliant, transparent umbrella company will make sure you get the maximum benefit safely and legally. A non-compliant one, on the other hand, can expose you to serious financial and legal headaches.
But navigating this choice doesn't need to be difficult. Understanding the basics of choosing the best payroll service gives you the foundation you need. It helps you ask the right questions and spot potential red flags right from the start.
Key Questions for Any Potential Provider
To protect yourself and ensure your pension gets the boost it deserves, you have to vet any potential umbrella company properly. Think of it as an interview; you are hiring them to manage your money correctly.
Here’s a simple checklist of questions to ask before you sign on the dotted line:
- Do you pass back 100% of the employer's National Insurance savings? This is non-negotiable. The answer must be a clear and simple “yes,” as this is where the main financial benefit of pension salary sacrifice comes from.
- Are there any hidden fees or margins taken from the NICs savings? Some providers might say they pass back the savings but then skim a percentage off the top. You need total transparency on how the saving is calculated and paid into your pension.
- Are you accredited by a recognised professional body? Look for accreditation from organisations like the FCSA (The Freelancer & Contractor Services Association) or Professional Passport. This shows the provider has been independently audited and meets high compliance standards. You can read our guide on why using an FCSA accredited umbrella company is so important.
- Can you provide a full pay illustration showing the salary sacrifice? A trustworthy provider will have no problem giving you a detailed breakdown. It should clearly show your original gross pay, the sacrificed amount, your new taxable pay, and the total contribution (including the employer NICs saving) landing in your pension.
The answers you get will tell you a lot about a provider’s ethics and how they operate.
Spotting the Red Flags of Non-Compliance
While most providers operate above board, some promote schemes that are non-compliant and can land you in serious trouble with HMRC. It’s vital you can identify the warning signs of a dodgy arrangement.
Forecasts from the Office for Budget Responsibility (OBR) explain the enduring popularity of salary sacrifice. They show a basic rate taxpayer saves 8% on their own NI, while the scheme also saves up to 13.8% in employer NI on pension contributions. While other benefits were reformed, pensions were protected due to their importance. This highlights why you should only work with providers offering IR35-compliant options that pass back these valuable savings. You can read the full OBR analysis on salary sacrifice for more detail.
Be wary of any provider that:
- Promises take-home pay that seems too good to be true. If a company suggests you can take home 80%, 85%, or even 90% of your contract value, it is almost certainly a disguised remuneration scheme. These are aggressive, non-compliant models that HMRC actively pursues.
- Uses confusing jargon or mentions loans. Be extremely cautious if you hear terms like "annuities," "bonuses," or "loans" as part of the payment structure. Your pay should be straightforward PAYE income.
- Pressures you into a quick decision. A reputable provider will give you time and all the information you need to make an informed choice. High-pressure sales tactics are a massive red flag.
- Operates outside standard PAYE rules. Your payslip should look familiar, detailing Income Tax and National Insurance deductions on your post-sacrifice salary. Anything else is a cause for concern.
At UmbrellaCompany.com, we are committed to transparency and compliance. We believe a salary sacrifice UK arrangement should be simple, effective, and secure, giving you a powerful tool to build your pension without the worry.
Your Salary Sacrifice Questions Answered
To make sure you’re going in with your eyes wide open, let's run through some of the most common questions contractors have about salary sacrifice UK schemes. These are the practical, real-world queries that often come up, and having clear answers is key to making the right choice.
Can I Sacrifice My Entire Salary into My Pension?
In a word, no. You absolutely cannot sacrifice your entire salary, and UK employment law is crystal clear on this point.
Your earnings after the sacrifice must not drop below the National Minimum Wage or National Living Wage for the hours you’ve worked. Your umbrella company is legally on the hook to enforce this.
If any provider suggests you can sacrifice your whole salary, run a mile. It's a massive red flag for a non-compliant tax avoidance scheme.
How Does Salary Sacrifice Affect My Student Loan Repayments?
This is a good point, and yes, a salary sacrifice arrangement will likely affect your student loan repayments. In the UK, these repayments are calculated from your income that’s subject to National Insurance.
Because salary sacrifice reduces your gross pay, it also reduces the amount you repay on your student loan each month. This gives you a little extra in your pocket right now, but you need to think about the long-term picture. Paying less each month means it will probably take you longer to clear the loan, which could mean paying more interest overall.
What Happens to My Pension if I Change Umbrella Companies?
This is a common worry for contractors who switch between different assignments and umbrella providers. The key thing to remember is that the pension pot belongs to you, not the umbrella company.
If you move on from your current umbrella, that pension pot is still your asset. You’ve got a few options:
- Keep contributing: You can often carry on making personal contributions to the same pot, though you'll miss out on the National Insurance savings that come with salary sacrifice.
- Transfer the pension: You can usually move your existing funds into a new pension scheme set up by your next umbrella company.
- Leave it be: You can just let the funds stay put, invested and hopefully growing, until you’re ready to retire.
It's always smart to have a quick chat with a financial adviser to figure out the best move for your specific situation.
Can I Change My Mind About a Salary Sacrifice Arrangement?
A salary sacrifice agreement is a formal change to your employment contract, so it’s not something you can dip in and out of whenever you feel like it. The agreement is typically for a fixed term, usually 12 months. This is an HMRC requirement to ensure it’s a genuine change to your employment terms, not just a temporary tax dodge.
That said, you can usually opt out or change your contribution if you have a major 'lifestyle event'. These normally include things like:
- Getting married or entering a civil partnership
- Divorce or separation
- Having a baby or adopting a child
- A major change in your partner's job
Most compliant umbrella companies, like those we partner with, also have an annual review window where you can adjust your arrangement for the year ahead. Always read the fine print of your contract before you sign so you know exactly how much flexibility you have.
Is Salary Sacrifice Better Than Making a Personal Pension Contribution?
For most contractors working inside IR35 via an umbrella, the answer is a resounding yes. It all comes down to National Insurance contributions.
When you make a personal pension contribution, the money comes out of your net pay, which is your salary after tax and National Insurance have been taken. You can claim back the income tax from HMRC, but the National Insurance is gone for good. With salary sacrifice, the contribution comes from your gross pay. You get instant tax relief and, crucially, you save on National Insurance too.
When a compliant umbrella also passes on their employer's NICs saving to you, the benefit is even greater. This double-dip on NI savings makes salary sacrifice UK schemes the most efficient way for umbrella contractors to build their retirement fund.
What Other Benefits Can I Get Through Salary Sacrifice?
Pensions are by far the most popular and financially impactful benefit, but the same mechanism can be used for other things. One of the biggest at the moment is an EV (Electric Vehicle) salary sacrifice scheme.
This lets you lease a new electric car, with the monthly cost, insurance, and maintenance all paid from your gross salary. The tax savings can make driving an EV much cheaper than a personal lease. Some providers might also offer Cycle to Work schemes or ways to buy tech. For pure financial clout and long-term wealth, though, pension contributions are still the number one choice for contractors.
At UmbrellaCompany.com, our entire focus is on connecting you with a compliant, reputable umbrella company that offers a transparent and effective salary sacrifice pension. We help you find a provider that will pass back 100% of the employer's NICs, putting more money into your retirement pot.
Find your perfect umbrella company today at https://umbrellacompany.com.


