


A new contract rate can feel exciting right up until you ask the obvious question, what will land in your bank account.
That's where many contractors pause. You might know your day rate or hourly rate, but payslips under an umbrella arrangement can still feel opaque at first glance. A PayStream calculator, or any similar umbrella pay tool, helps turn that uncertainty into a practical estimate you can work with.
Used properly, a calculator gives you a useful preview of your likely deductions and net pay. Used blindly, it can give you false confidence. The difference usually comes down to the assumptions hiding behind the numbers.
Introduction to Contractor Pay Calculators
Most contractors meet a pay calculator at a very specific moment. You've accepted a role, the recruiter has confirmed the rate, and now you're trying to work out whether the contract still makes sense once tax, National Insurance, pension and umbrella costs are taken into account.
That first estimate matters because it shapes real decisions. You might be comparing two contracts, deciding whether to increase pension contributions, or checking whether an inside IR35 role still fits your monthly budget. A calculator gives you a fast starting point, but it only helps if you know what it's showing you.
PayStream is one of the recognised names in this space. It's described as a compliant UK umbrella company that holds FCSA accreditation and follows PAYE rules, pays the correct National Insurance contributions, and has directors listed on Companies House with no offshore connections, according to guidance on compliant umbrella companies.
That compliance point matters because a calculator isn't just a convenience tool. It reflects how a compliant umbrella arrangement is supposed to process pay.
Why contractors use these tools
A good pay calculator helps you answer questions like these:
- Can I afford this contract: Your quoted rate may look strong until deductions are applied.
- How much will pension contributions change things: Even small adjustments can shift monthly take-home pay.
- Is my IR35 position affecting the result: The structure you work through changes the numbers significantly.
- Do I need a second opinion: If one estimate looks unusually generous, that's often a cue to dig deeper.
Practical rule: Treat a calculator result as a draft payslip, not a promise.
If you're still deciding how your role should be classified in the first place, this guide to determining employee or contractor status is a helpful companion read. And if you want a broader benchmark before comparing providers, our own guide to UK take-home pay can help you sense-check the figures.
What Is a Paystream Calculator and How Does It Work
A PayStream calculator works like a financial simulator for contract income. You enter a few details about your rate and working pattern, and the tool models what a compliant payroll process could do to that income before it reaches you as net pay.
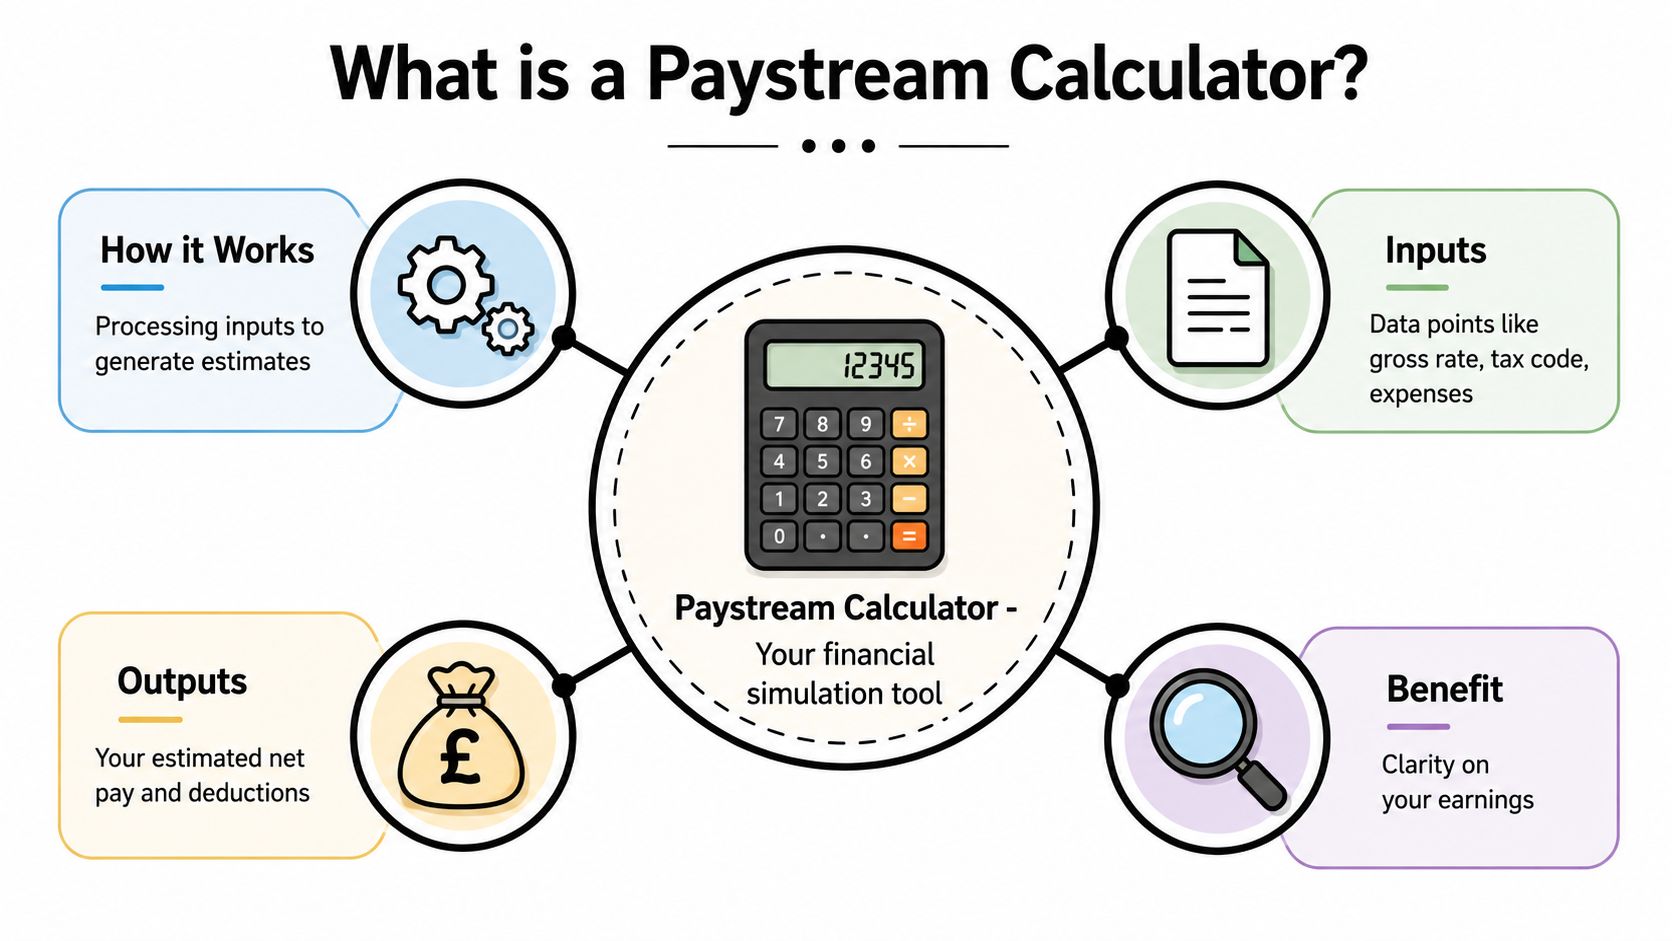
The basic flow from gross to net
At a high level, the calculator starts with your gross contract income. It then works down through the deductions that apply when you're paid through an umbrella company under PAYE.
That usually includes the umbrella margin, employment costs that sit within the assignment income, and then the personal deductions that appear on your payslip. The final number is your estimated take-home pay.
The tax bands used in these calculations matter. For the 2026/27 tax year, the personal allowance is £12,570, earnings from £12,571 to £50,270 are taxed at 20%, and earnings from £50,271 to £125,140 are taxed at 40%, based on umbrella worker tax guidance.
Why the result can feel lower than expected
The surprise for new contractors is that the quoted contract rate is not the same as gross salary in the normal employee sense.
Under an umbrella setup, the assignment rate funds the whole employment cost chain. So the calculator does more than apply income tax to your headline rate. It's modelling the route from contract revenue to taxable pay.
A simple way to think about it is this:
- You enter your rate and work pattern
- The tool estimates the employment costs within that amount
- It applies tax and employee deductions
- It outputs an estimated net figure
A realistic calculator doesn't make your pay smaller for no reason. It makes the hidden layers visible.
What the calculator is really useful for
The most practical use of a PayStream calculator is comparison. You can test different rates, contract lengths, pension choices or structures and see how your estimated pay changes.
That's especially useful when a recruiter quotes an hourly rate that sounds attractive, but you need to know what that means after payroll. If you want to run those scenarios yourself, our payroll calculator for take-home pay is a straightforward place to start.
Understanding the Key Inputs of a Payroll Calculator
A calculator is only as good as the details you put into it. If your inputs are rough guesses, your output will be a rough guess too. That's why the most useful contractors treat calculator fields less like a form and more like a checklist.
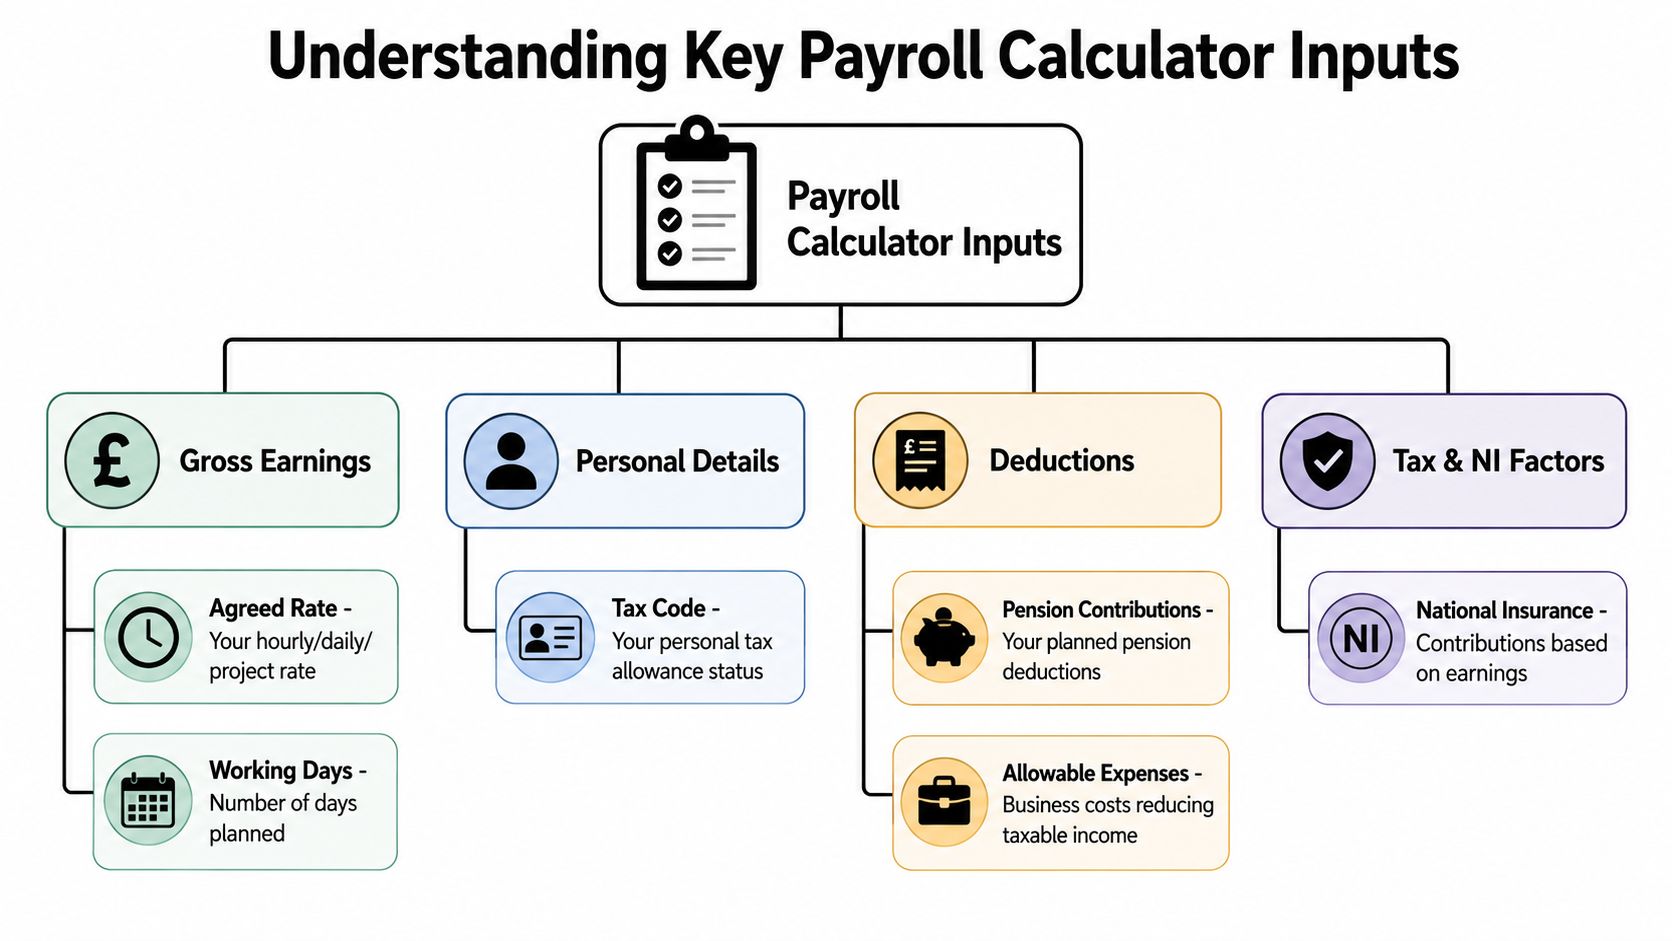
Start with your earnings details
The first fields usually cover your agreed rate and how often you'll work. If you're paid hourly, enter the true hourly figure and realistic weekly hours. If your contract is discussed in day rates, convert carefully and don't assume every month contains the same billable pattern.
New contractors often overestimate income by using a full month of ideal working days, even when the contract start date, gaps between assignments, or unpaid leave will reduce what's invoiced.
Personal details shape tax outcomes
Tax code is one of the most important fields on any pay calculator, but many users skip over it because the default looks familiar.
Your tax code affects how much income is treated as tax free before PAYE kicks in. If the code shown on the calculator doesn't match the code likely to be used in payroll, the estimate can drift away from reality.
Don't ignore pension and other deductions
Pension choices can change your take-home figure in a meaningful way. Some calculators ask whether you contribute, how much, and whether the arrangement uses salary sacrifice or a standard deduction model. If the tool doesn't explain this clearly, assume the estimate may be simplified.
Other personal deductions can matter too, such as student loan repayments. A calculator may include these options, but it still relies on you entering the right details.
Check the assumptions before trusting the output. A missing pension setting or wrong tax code can matter more than a small difference in rate.
The umbrella margin is not a tax
This point causes a lot of confusion. A compliant umbrella company does not charge a separate “umbrella company tax”. Instead, it deducts a small administrative margin per payroll payment to cover day-to-day operating costs, and that margin is only applied when the worker is paid, as explained in this overview of umbrella company tax.
That means you should read the margin as a service fee, not a government deduction.
A useful way to review your inputs is to ask:
- Rate entered correctly: Hourly, daily or monthly figures need to match the contract wording.
- Work pattern realistic: Planned time off and start dates can reduce paid periods.
- Tax code checked: Don't accept the default if you know your payroll code differs.
- Pension settings understood: Employer and employee contributions may affect the estimate differently.
- Other deductions included: Student loans and similar items can alter net pay.
- Margin identified clearly: If a provider can't explain its fee clearly, that's a warning sign.
Worked Examples Inside and Outside IR35
Examples make calculators easier to trust because you can see the trade-off rather than just reading about it.
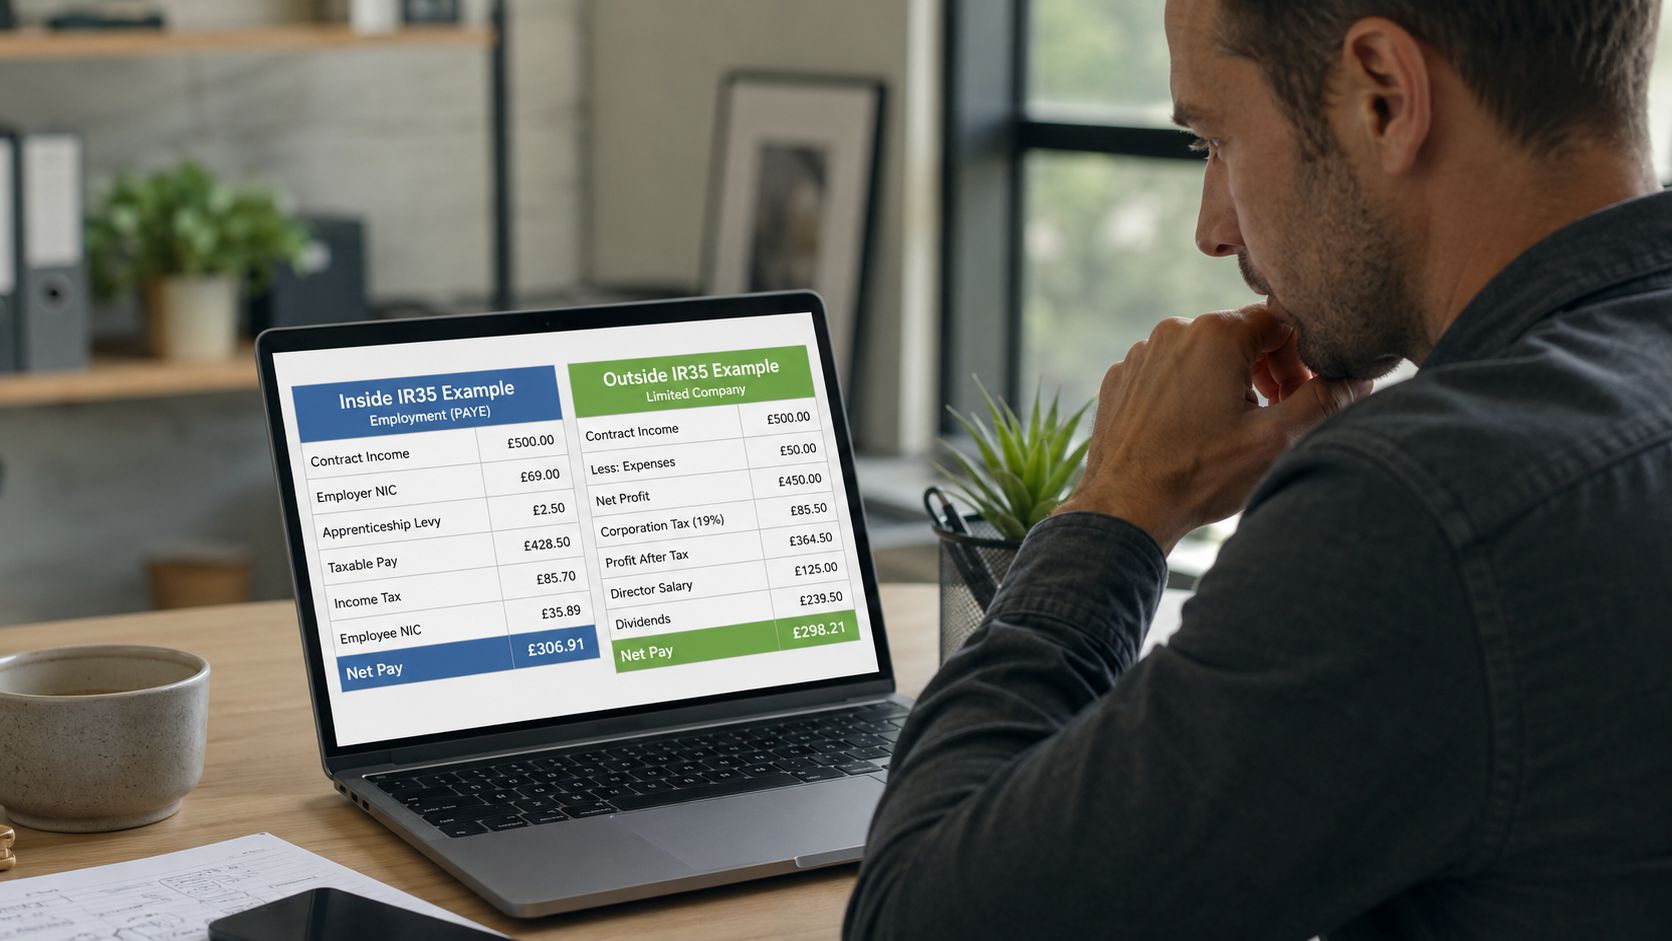
One useful benchmark comes from PayStream's Contractor Salary Calculator. For a contractor earning £50/hour over 40 hours/week, it shows an umbrella route netting £1,720/month versus a limited company route of £1,890/month, according to the PayStream contractor salary calculator.
That doesn't mean the umbrella route is wrong or poor value. It reflects a different trade-off. A limited company can retain higher net pay in this example, while the umbrella route offers simpler compliance and less administration.
Umbrella vs limited company take-home pay example
| Structure | IR35 Status | Gross Monthly Income | Estimated Net Monthly Pay |
|---|---|---|---|
| Umbrella company | Inside IR35 | Based on £50/hour over 40 hours/week | £1,720/month |
| Limited company | Outside IR35 style comparison used by calculator | Based on £50/hour over 40 hours/week | £1,890/month |
How to read this comparison properly
The first thing to notice is that the calculator is comparing structures, not just tax rates.
Under an umbrella arrangement, payroll is simpler. PAYE is handled for you, statutory employment rights are part of the setup, and there's less ongoing admin. Under a limited company structure, the administration burden is heavier, but the calculator example shows why some contractors still prefer it when that route is available and appropriate.
Where contractors often get confused
Many people look at a table like this and ask, “Why wouldn't everyone just use a limited company?” The answer is that the structure has to fit the engagement and the compliance position.
If the role is inside IR35, your route is more constrained. The cleaner compliance path often matters more than chasing the highest theoretical net figure. That's why contractors should use a calculator as a planning tool, not a shortcut to deciding status.
A few practical lessons come from this example:
- Higher net pay isn't the only goal: Admin, risk and compliance all affect the actual value of a setup.
- Structure changes the result: The same working pattern can produce different outcomes.
- Comparisons need context: A headline net figure is only useful when you understand the employment arrangement behind it.
When you compare calculator outputs, compare the compliance burden too. The cheapest-looking option on paper isn't always the safest or simplest in real life.
If you want to test similar scenarios with your own rate and IR35 position, an IR35 calculator can help you model the difference before you accept a role.
Common Mistakes and Calculator Limitations
The biggest mistake contractors make with a pay calculator is assuming the result is personalised just because they typed in a few details.
It usually isn't. Most tools rely on defaults, standard assumptions and simplified payroll logic. That doesn't make them useless. It means you need to read them critically.
The tax code trap
One of the clearest examples is the default 1257L tax code. Standard calculators often use it automatically, but that can be misleading for higher earners because it ignores the gradual reduction of the tax-free allowance above £100k, which can create a misleading “60% tax trap” in estimates. Users in a ContractorUK discussion noted that entering a more specific tax code can produce a more realistic result, as discussed in this calculator estimate thread on Reddit.
If your income, other employment, benefits, or prior payroll history affect your tax code, the default may be too blunt to rely on.
Other hidden assumptions
Calculators also make assumptions about work patterns, deductions and payroll timing. Some assume a standard working week. Others may present pension settings without making the treatment especially clear.
That matters because small assumptions can stack up. A result can look precise to the penny while still being based on inputs that don't reflect your actual circumstances.
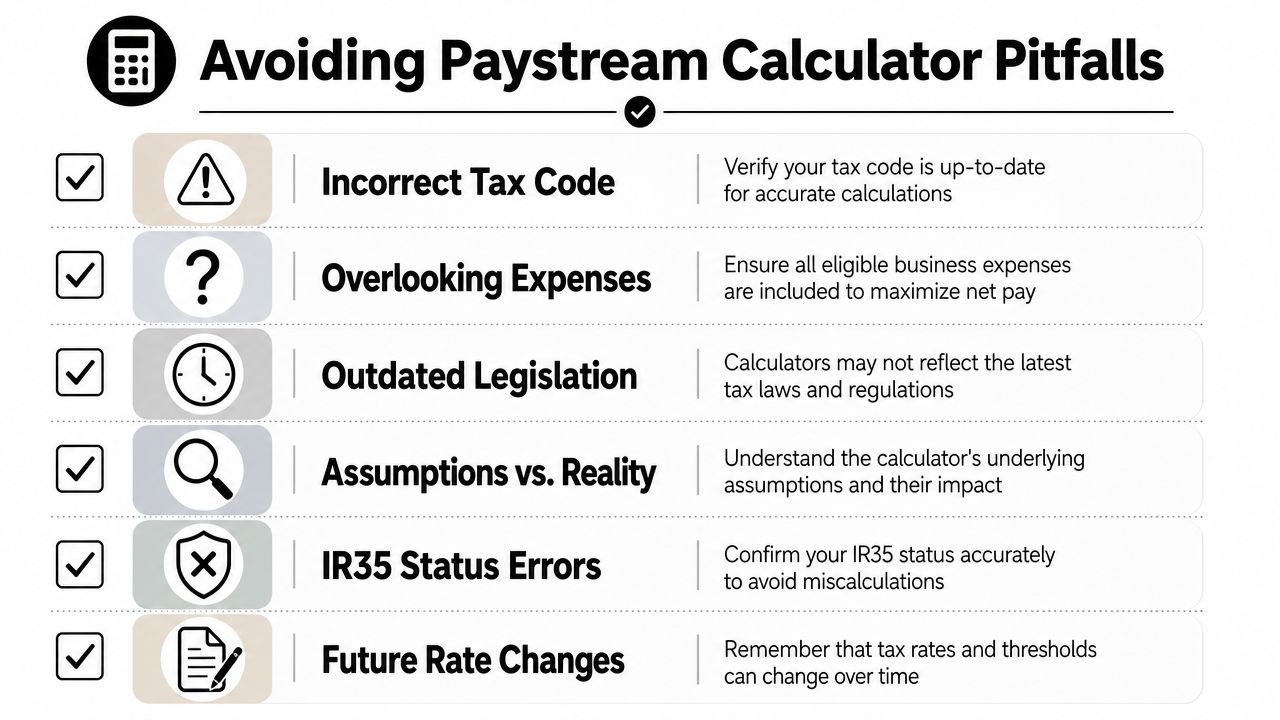
Here are some common pitfalls to watch for:
- Default tax code left unchanged: This is one of the fastest ways to get a flattering but inaccurate estimate.
- Pension treatment misunderstood: Salary sacrifice and standard deductions don't always produce the same outcome.
- Incomplete personal deductions: Student loans or other payroll deductions can be left out.
- Contract pattern overstated: People often assume every week will be fully billable.
- Status entered incorrectly: An IR35 mismatch can make the whole estimate irrelevant.
Reality check: The more your circumstances differ from the calculator default, the less you should trust the first number it gives you.
Use the estimate for planning, not certainty
A calculator is best used as a planning tool for ranges and decisions. It helps you compare contract offers, test contribution levels and spot whether a quoted rate feels viable.
It's also wise to build your budget around a cautious figure rather than the most optimistic one. If your monthly income can move around with contracts, gaps, and payroll timing, this guide on how to manage finances with irregular income offers sensible budgeting ideas that fit contractor life.
From Estimate to Reality Finding the Right Umbrella Company
Once you understand how a PayStream calculator works, the key lesson is simple. The result is only as reliable as the assumptions underneath it.
A useful estimate starts with the right rate, the right tax settings, and a realistic view of deductions. It also depends on working with a provider that follows compliant payroll practices rather than advertising unrealistic take-home promises.
That's why the calculator stage and the umbrella selection stage belong together. The estimate tells you what might happen. The provider tells you how that pay process will be handled in practice.
If you're comparing options, it helps to look at more than just margin. Service quality, payroll clarity, responsiveness, accreditation and contractor experience all matter. For readers thinking beyond the next payslip, broader financial habits matter too, and this Step-by-step guide to financial independence offers a useful long-view perspective on building resilience with income that changes over time.
If you specifically want to review this provider in more detail, our page on PayStream umbrella is a practical next stop.
Ready to compare your options with more confidence? Umbrella Company helps contractors and freelancers review trusted umbrella companies, compare key features, and choose a setup that fits their rate, role and IR35 position.


