


Trying to work out your take-home pay from a contract day rate can feel like solving a puzzle with half the pieces missing. A good payroll calculator gives you those missing pieces, turning your gross contract value into the real number that actually hits your bank account. It is an essential tool if you want to plan your finances with any real accuracy.
What Actually Decides Your Contractor Take-Home Pay?
Getting a solid handle on what you will bank at the end of the week or month is the primary goal for any contractor. Here at UmbrellaCompany.com, we want to help you get beyond those back-of-the-envelope guesses and show you how to confidently calculate your true take-home pay.
This guide will walk you through the journey from your gross day rate to your final net pay. We will break down all the essential deductions every contractor has to deal with, including:
- Income Tax (PAYE)
- National Insurance Contributions (NICs)
- Umbrella Company Costs and Margin
- Pension Contributions
The Core Deductions Explained
Your gross earnings are just the starting point; a few statutory deductions will take a slice before the money is yours. In the UK, the main ones are Income Tax and National Insurance.
For the 2025/26 tax year, the basic income tax rate is 20% for earnings between £12,571 and £50,270, with higher rates kicking in for bigger incomes. As an example, someone earning £40,000 a year would pay a combined £5,486 in tax and NI. That leaves them with around 71% of their gross salary.
These are the fundamental calculations that any decent payroll calculator take home pay estimate is built on.
Your final net pay is shaped by more than just your day rate. Things like your personal tax code, any student loan repayments you might have, and your pension choices all have a direct impact on the final figure you receive.
Once you understand how these bits and pieces fit together, you can get a much clearer, more practical view of your payslip. It gives you the confidence to plan your finances properly.
Of course, it is also vital to see which payroll solution gives the highest take-home pay for your specific circumstances. By the end of this guide, you will know exactly how to do that.
Getting Your Figures Straight Before You Start
Before you even touch a payroll calculator, you need to get your head around the numbers on your payslip. It is a common trap for contractors to just punch in their day rate and hope for the best, but the reality is a bit more involved. The key is understanding how you get from the client’s assignment rate to your actual taxable salary.
Let's start with your Gross Pay. This is not just your day rate multiplied by the days you have worked. When you are with an umbrella company, the 'gross pay' is the full assignment rate your client pays for your services. From that starting pot, a few costs have to be deducted before your personal tax is even on the table. This is where a lot of confusion comes from.
What Comes Off Before Tax?
The first things to come off the assignment rate are the costs of your employment. These are not your personal taxes; they are the statutory costs that the umbrella company, as your official employer, has to pay by law.
These employment costs include:
- Employer’s National Insurance Contributions (NI): A mandatory payment based on your earnings.
- The Apprenticeship Levy: A UK tax on employers which helps fund apprentice training programmes.
- The Umbrella Company Margin: This is the flat fee the umbrella company charges for running your payroll and handling all the admin.
It is only after these employment costs have been sorted that your personal gross salary is worked out. That is the figure HMRC is interested in for calculating your Income Tax and employee NI contributions.
Here is a simple way to visualise the flow from your day rate down to what you actually take home.
As the chart shows, your take-home pay is what is left in your pocket after every single one of these necessary deductions has been processed.
From Day Rate to Taxable Income: A Real-World Example
To bring this to life, let’s imagine you are on a £500 per day contract. At UmbrellaCompany.com, we are all about total transparency, so here is exactly how that initial sum gets broken down before personal tax even enters the picture.
The £500 is the starting point. The umbrella first deducts its margin and then calculates and pays the Employer’s NI and Apprenticeship Levy from what is left. This ensures all the legal boxes are ticked.
Let's break it down in a table.
| Item | Description | Example Amount (£500 Day Rate) |
|---|---|---|
| Assignment Rate | The full amount paid by the end client for your services. | £500.00 |
| Employment Costs | Deductions for Employer’s NI and the Apprenticeship Levy. | – £56.03 |
| Umbrella Margin | The fee charged by the umbrella for their payroll service. | – £25.00 (weekly equivalent) |
| Gross Pay for Tax | The remaining amount that is considered your taxable income. | £418.97 |
The final figure, £418.97 in this case, becomes your gross taxable pay. This is the amount that will then have standard Pay As You Earn (PAYE) deductions applied to it.
The crucial takeaway is that employment costs are subtracted from the client's rate before your personal salary is calculated. This is standard, compliant practice for all umbrella companies.
You can learn more about how we handle PAYE tax and NI contributions on our dedicated page. Nailing this initial breakdown is the absolute foundation for getting an accurate take-home pay calculation every single time.
Getting to Grips With a Payroll Calculator
Theory is one thing, but let's get practical. We are going to walk you through a proper, hands-on example of using an online payroll calculator, specifically for a contractor working through an umbrella company. Once you have got the hang of this, you can move past rough estimates and start planning your finances with real confidence.
The aim here is to show you exactly how each bit of information you plug in (your day rate, your tax code, your pension) nudges that final take-home figure. It is a vital skill, not just for a one-off check, but for keeping your finances on track as your contracts and circumstances change.
A Practical Walkthrough
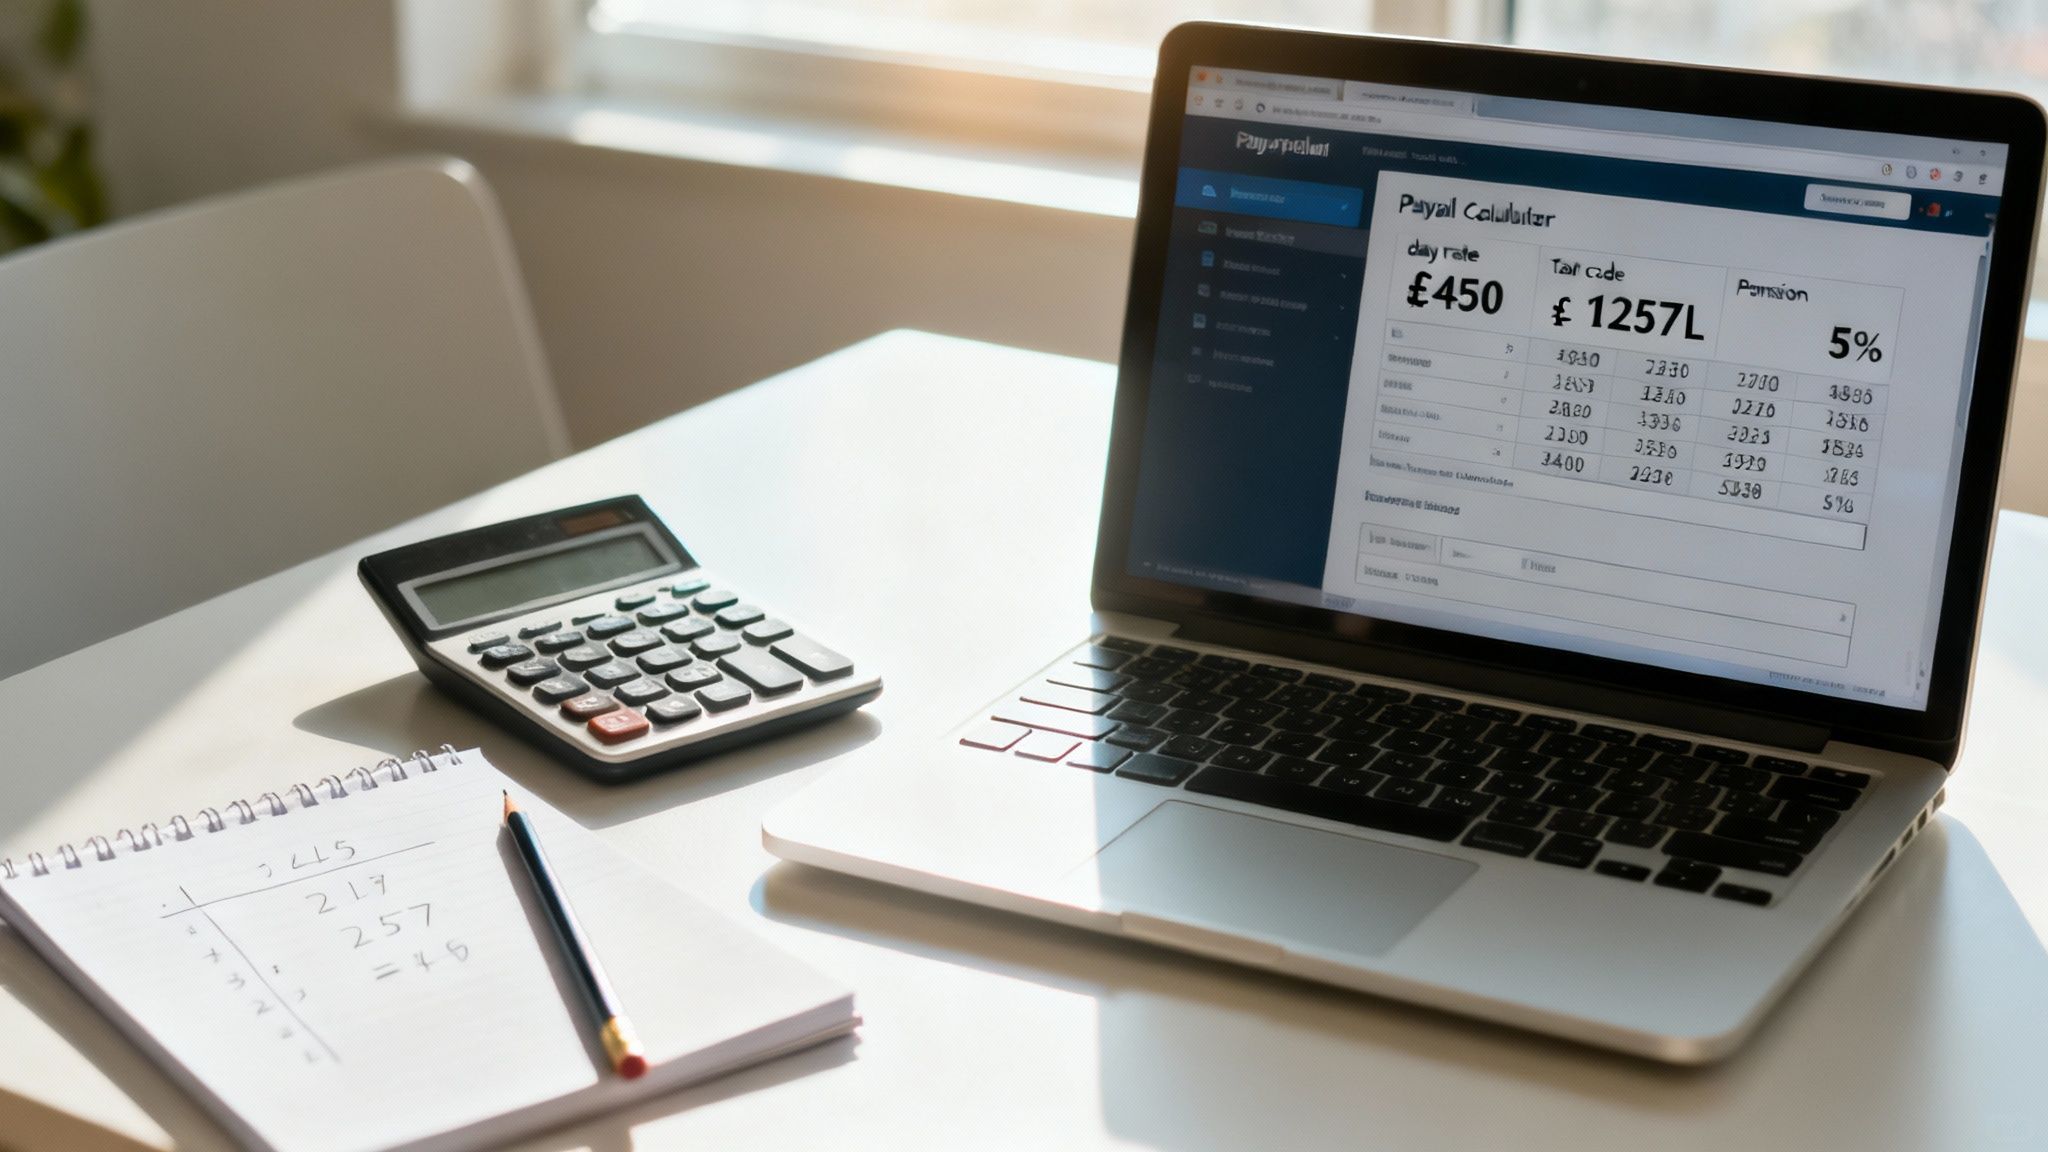
Let's use a common scenario. Say you are a contractor earning a day rate of £450. You are on a standard 1257L tax code and you have decided to put 5% of your salary into your pension. These are the core details you will need to get started.
Here is how you would punch those numbers into a typical calculator:
- Your Rate: Enter £450 and make sure you set the period to 'Per Day'.
- Tax Code: Put in 1257L. If yours is different, you absolutely must use the one from your latest payslip or a recent letter from HMRC. No guessing!
- Pension: Input 5%. If you have the option, ensure it is set as a pre-tax deduction (often called salary sacrifice) to see the true tax benefit.
- Student Loan: This is a big one. If you have a student loan, select the correct plan. Forgetting this is a classic mistake that will give you a falsely optimistic take-home pay estimate.
Making Sense of the Numbers
Once you hit ‘calculate’, the tool will do its thing, breaking down your gross pay into all the various deductions and, finally, showing your net pay. You should see clear, itemised lines for things like Income Tax (PAYE), your National Insurance contribution, and your pension payment.
The crucial part is to give the results a quick sanity check. Does it all look about right for what you are earning? If your take-home pay seems unusually high, go back and double-check you have included everything, especially things like a student loan or a non-standard tax code.
One of the biggest pitfalls for contractors is forgetting to account for umbrella-specific costs. Most generic online calculators simply do not have fields for the umbrella's margin or crucial employment costs like Employer's NI. This almost always leads to a misleadingly high estimate.
For a calculation that actually understands how the umbrella model works, you really need a purpose-built tool. Here at UmbrellaCompany.com, we have a reliable umbrella company calculator designed to give you a much more accurate picture.
Using a specialist calculator like ours means you are seeing a realistic view of your take-home pay, which is exactly what you need to manage your money properly.
How Your IR35 Status Shapes Your Pay
When you are a contractor, your IR35 status is probably the single biggest factor that dictates how you get paid and what you actually take home. It is essential to get your head around the difference between working 'inside IR35' and 'outside IR35' before you even think about plugging numbers into a payroll calculator take home pay tool.
If your contract lands you inside IR35, HMRC essentially sees you as an employee for tax purposes. This means your income has to go through a proper PAYE payroll system. For most contractors, this makes joining a compliant umbrella company the most straightforward option, as they will handle all the Income Tax and National Insurance deductions for you.
Inside vs Outside IR35: A Practical Comparison
Now, if you are lucky enough to secure a contract deemed outside IR35, you are in a different ballpark. You have much more control. You will operate through your own limited company, manage your own tax affairs, and often achieve a higher net income by drawing a mix of salary and dividends.
The gap in take-home pay between these two scenarios can be huge, even when the day rate is identical.
Let's imagine two contractors, both charging a day rate of £500:
- Contractor A (Inside IR35): They are working via an umbrella company. Their pay is hit with PAYE tax, plus both employee's and the dreaded employer's NI.
- Contractor B (Outside IR35): This contractor works through their own limited company. They pay themselves a small, tax-efficient salary and take the rest as dividends, paying Corporation Tax first.
When the dust settles, Contractor B will almost always have more money in their pocket. But that financial gain comes with a trade-off: they are responsible for running their company, filing accounts, sorting tax returns, and staying on the right side of IR35.
You can play around with the numbers yourself using our inside vs outside IR35 calculator to see the real-world difference.
It really boils down to this: you can have potentially higher earnings outside IR35, but with all the admin that comes with it. Or, you can have the simplicity and statutory rights of an inside IR35 role managed by an umbrella company.
The Broader Economic Context
It is also worth seeing where contractor pay fits into the wider UK economy. Data from the three years leading up to March 2021 showed that 45% of UK households earned less than £600 a week before tax. At the other end of the scale, only about 7% brought in over £2,000.
These gross figures paint a picture of a broad income spectrum. Once you factor in all the statutory deductions, the differences in net pay become even more stark, highlighting just how much tax status can impact your final earnings.
Working Smart and Staying Compliant
https://www.youtube.com/embed/UiPIXZISvEk
Knowing how your take-home pay is calculated is the first big hurdle. The next is learning how to protect it and, where possible, legally maximise it. It is not just about the day rate you command, but how smartly you manage that income while keeping everything above board with HMRC.
Here at UmbrellaCompany.com, we want to give you the tools and knowledge to make great financial decisions. That means going beyond just using a payroll calculator take home pay tool for a quick forecast. It is about understanding the compliant strategies that can genuinely improve what you take home.
Making Your Pension Work Harder
One of the most effective and straightforward ways to boost your net pay is through a salary sacrifice pension scheme. When you contribute to your pension this way, the money comes out of your gross earnings before any tax or National Insurance is deducted.
This simple move lowers your overall taxable income, which means you pay less in statutory deductions. The result? You are building your retirement pot while at the same time increasing the amount that actually lands in your bank account. It is a completely legitimate and highly effective strategy that savvy contractors have used for years.
Maximising your take-home pay is not about finding dodgy loopholes. It is about using approved, compliant methods like salary sacrifice to your advantage. A small adjustment to your pension contribution can make a surprisingly big difference to your net income over time.
Spotting the Red Flags of Non-Compliance
While smart strategies can improve your earnings, you must be vigilant against non-compliant payroll schemes. If an offer looks too good to be true, you can bet it is. The biggest red flag is any provider promising an unrealistically high take-home pay, often quoting figures of 85% or even higher.
These schemes usually involve complex and questionable arrangements, sometimes disguised as loans or other payment structures, all designed to sidestep paying the correct tax. Getting involved with these outfits, even if you do not realise what they are doing, can have severe consequences. We are talking large retrospective tax bills and hefty penalties from HMRC. It is just not worth the risk.
The Importance of Accreditation
So, how do you protect yourself? The single most important thing you can do is work only with a fully accredited umbrella company. Look for providers who are members of respected, independent professional bodies like the FCSA (The Freelancer & Contractor Services Association) or Professional Passport.
Accreditation from these organisations is not just a fancy badge; it is your guarantee. It means the provider has been through rigorous, independent audits confirming their processes are fully compliant with UK tax law and government regulations.
Choosing an accredited partner, like the ones we feature at UmbrellaCompany.com, is non-negotiable for your financial safety. Our commitment is to total transparency and compliance, ensuring you get paid correctly, on time, and without any risk. This leaves you free to focus on your contract work with complete peace of mind, knowing your finances are in safe hands.
Frequently Asked Questions
Here are some of the most common questions we get from contractors trying to get to grips with their pay. It is totally understandable, navigating contractor payroll for the first time can feel a bit like learning a new language. Let’s break down a few of the queries we hear all the time.
Why Does My Calculator Estimate Not Match My Payslip Exactly?
This is probably the number one question we are asked. You have run the numbers through a payroll calculator take home pay tool, and when your first payslip lands, the figures are slightly off. Do not panic, this is actually quite normal.
Most online calculators give you a solid estimate based on a standard 1257L tax code. The reality is, your personal tax code might be different if HMRC has adjusted it for things like underpaid tax from a previous year or other benefits.
Plus, a calculator cannot predict the unique variables of your specific pay period. Things that often cause a difference include:
- Expense claims you have submitted.
- Holiday pay you have decided to take.
- A one-off correction or adjustment from your last payslip.
The best way to get a close estimate is to be meticulous with the details you enter, especially your exact tax code. If there is still a big gap you cannot account for, just have a chat with your umbrella company. They should be able to walk you through your payslip line by line.
How Do Pension Contributions Affect My Take-Home Pay?
Smart question. Thinking about your pension is one of the most financially savvy things you can do as a contractor. When you pay into a pension via a salary sacrifice scheme with an umbrella company, the money comes out of your gross pay.
What does that mean in simple terms? It is taken before the tax and National Insurance calculations are done. This lowers your taxable income, which means you pay less tax and NI. It is a win-win: you are saving for your future while also boosting your take-home pay today compared to making a post-tax contribution. Any good payroll calculator will have an option for this, so you can see the difference it makes in black and white.
What’s the Difference Between Employment Costs and My Deductions?
Getting your head around this is the key to understanding any umbrella company payslip.
Employment Costs are the costs of employing you. Think of them as the employer's bill. This includes things like Employer's National Insurance and the Apprenticeship Levy, which your umbrella company is legally required to pay to HMRC. These are deducted from the assignment rate (the pot of money your client pays for your services) before your own salary is worked out.
Your Deductions, on the other hand, are your personal contributions. These are the taxes taken from your gross salary, which includes your employee's National Insurance and PAYE Income Tax.
The distinction between employment costs and your personal deductions is crucial. A compliant provider will always show these two sets of deductions separately on your payslip, offering complete transparency.
A final word of warning: while there are lots of calculators online, stick to one from a source you trust. Many generic tools do not account for umbrella-specific details like the company's margin or those all-important employment costs. This can leave you with a misleadingly high figure. Always treat a calculator as a guide, and the official pay illustration from your chosen provider as the most accurate forecast.
Ready for a clear, accurate, and compliant payroll experience? At UmbrellaCompany.com, we help you compare and choose the best FCSA-accredited umbrella companies to ensure you are paid correctly every time. Find your perfect umbrella company with us today.


