


Have you ever wondered how your taxes just get paid? For most people in the UK, the answer is a system called Pay As You Earn, or PAYE. This guide explains what the system is, how it affects you, and what you need to know as an employee or contractor.
Think of it like a pay-as-you-go mobile plan for your taxes. Instead of facing a massive, daunting tax bill once a year, your contributions are handled in manageable chunks every time you get paid. It's a system designed to make life simpler for everyone.
Understanding The PAYE System

At its heart, Pay As You Earn is all about efficiency. It shifts the heavy lifting of tax calculations and payments from you, the individual, onto your employer.
This means your tax obligations are settled up consistently, right throughout the financial year. Whether you’re a permanent employee or a contractor working through an umbrella company, your employer uses a specific tax code issued by HMRC to figure out exactly how much Income Tax and National Insurance to deduct from your paycheque.
The Key Players And Their Roles
The PAYE system works so well because everyone involved has a clear and distinct role. Getting your head around who does what is the first step to truly understanding how your pay is calculated.
Let's break down the key participants in the PAYE process and what each one is responsible for.
| Participant | Role and Responsibility |
|---|---|
| The Employee | Your main job is to provide correct personal details and your P45 from any previous job. This is crucial for getting the right tax code from day one. |
| The Employer | This could be a traditional company or an umbrella company. They are legally required to calculate your tax and NICs, deduct it, and pay it to HMRC for you. |
| HMRC | As the UK's tax authority, HMRC sets the tax rates and issues the tax codes employers need. They collect the payments and keep a running total of your contributions. |
As you can see, the process is designed to be pretty seamless from your perspective. Your employer manages all the complex maths and sends the money directly to HMRC on your behalf. All of this is neatly broken down on your payslip, showing your gross pay, every deduction, and your final 'take-home' amount.
By collecting tax directly from the source of income, PAYE makes tax compliance almost automatic for millions of workers. It stops people from accidentally racking up huge tax debts and ensures a steady stream of funding for public services.
For contractors working inside IR35, this system is a game-changer. An umbrella company steps in to act as your employer for tax purposes, handling all your Pay As You Earn deductions correctly.
This setup offers the best of both worlds. You get the freedom of contracting, but with the administrative simplicity and legal protections of being an employee. If you want to dive deeper into how this works in practice, check out our guide on Umbrella Company vs PAYE.
The Origins and Evolution of PAYE
To really get your head around the Pay As You Earn system we use today, it helps to rewind the clock. PAYE was not just some dusty administrative update; it was forged in the heat of national crisis. Its story kicks off right in the middle of the Second World War, when the government was grappling with the monumental task of funding the war effort.
Before PAYE came along, Income Tax was something only the wealthiest sliver of the population had to worry about. The whole collection process was painfully slow, with tax often being settled long after the money had been earned and spent. Wartime Britain could not afford that kind of lag. It needed a new, faster way to bring in revenue, and that need sparked one of the biggest shake-ups in British financial history.
A Wartime Fix That Stuck
The Pay As You Earn (PAYE) system, launched in 1944, was the government's answer. Before the war, fewer than half a million people paid Income Tax. But with the colossal costs of the conflict, tax rates soared and the earnings threshold dropped, pulling millions more into the tax net. Almost overnight, the taxpayer base exploded from a select few to over 12 million people.
This is where the new system was so clever. It took tax directly from people's wages at the source. Instead of chasing payments at the end of the year, the Treasury got a steady, reliable stream of cash when it needed it most. You can actually read more about the system’s 80th anniversary on the official government news desk.
What started as an emergency measure quickly proved its worth. Today, PAYE is a cornerstone of the UK’s finances, with more than 30.5 million people contributing through it.
From Paper Ledgers to Digital Data
For decades, PAYE was a manual beast. Imagine vast offices filled with clerks, armed with paper ledgers and ridiculously complex tables, calculating deductions for every single employee in the country. It was slow, labour-intensive, and, as you can guess, prone to mistakes.
The slow march towards modernisation began with early computerisation, but the real game-changer landed much more recently. The journey from a paper-shuffling operation to a streamlined digital system was long, but absolutely vital for a growing workforce.
Here are the key milestones in its journey:
- 1944: PAYE is born as a manual, paper-based system.
- Late 20th Century: Computers begin to creep in, gradually taking over payroll and tax records.
- 2013: The launch of Real Time Information (RTI), a truly landmark moment.
The switch to Real Time Information was the single biggest overhaul of PAYE since it was first created. It dragged a 1940s system kicking and screaming into the 21st century, making tax collection more accurate and responsive than ever.
RTI changed everything. It meant employers had to report pay and deduction details to HMRC electronically every single time they paid their staff. This gave HMRC a live, up-to-the-minute picture of the nation's earnings, slashing errors and the need for messy end-of-year corrections.
So, what began as an urgent solution to a wartime crisis has evolved into a sophisticated, tech-driven system. It now forms the bedrock of the UK's public finances, proving remarkably adaptable while sticking to its original, simple purpose: collecting tax efficiently.
How to Decode Your Tax Code and Payslip
Your tax code and payslip are not just bits of admin; they are the complete story of your earnings. Getting to grips with them is absolutely vital for managing your finances, but the jumble of letters, numbers, and jargon can often feel like another language entirely.
This section will walk you through how to read these documents with confidence. By understanding how the Pay As You Earn system shows up on your payslip, you can check that you’re being taxed correctly and spot any potential errors before they snowball into a bigger problem.
What’s the Deal with Tax Codes?
Think of your tax code as a direct instruction from HMRC to your employer (or umbrella company). It tells them precisely how much tax-free income you’re allowed in a tax year. Anything you earn above that threshold gets taxed according to the current tax bands.
For the 2024/2025 tax year, the most common tax code you’ll see is 1257L.
- The number 1257 is the key part. It represents your Personal Allowance, the amount you can earn before you start paying tax. Just pop a zero on the end, and you get the full figure: £12,570.
- The letter L simply confirms you’re entitled to the standard tax-free Personal Allowance. Simple.
If your tax code is different, it’s a sign that your tax-free allowance has been adjusted for some reason. It might be lower if you have a company benefit like a car, or it could be higher if you’re claiming tax relief for work-related expenses.
A common reason for ending up on an emergency tax code (like BR, 0T, or W1/M1) is starting a new contract without a P45 from your previous role. This usually means you’ll pay more tax at first, but do not panic, it’s easily corrected once HMRC gets your new employment details sorted.
We see a variety of tax codes every day, and each tells a specific story about an individual's financial situation.
Common UK Tax Codes and Their Meanings
This table breaks down some of the most frequent tax codes and what they mean for you.
| Tax Code | Meaning and Application |
|---|---|
| 1257L | The standard tax code for most people who have one job or pension. It means you have the full tax-free Personal Allowance of £12,570. |
| BR | Stands for Basic Rate. All your income from this job is taxed at the basic rate (20%), with no Personal Allowance applied. Common for second jobs. |
| 0T | Your Personal Allowance has been used up, or you do not have the details for a new job. All your income is taxed, potentially at higher rates. |
| K | A 'K' code means your untaxed income (like company benefits) is greater than your Personal Allowance. The tax you owe is collected from your wages. |
| NT | No Tax. This means you are not liable for any tax on this income. |
| W1/M1 | An emergency tax code that taxes you on a 'Week 1' or 'Month 1' basis, without considering your previous earnings in the tax year. |
Knowing your code is the first step to making sure you're paying the right amount of tax.
Breaking Down Your Payslip
Your payslip is a line-by-line breakdown of your pay and all the deductions for a specific pay period. While the layout might look a bit different depending on who processes your payroll, the core information is always the same.
Let's look at the key terms you’ll come across.
Gross Pay: This is your total earnings before a single penny has been deducted. For contractors, it’s your agreed day rate or hourly rate multiplied by the time you’ve worked.
Taxable Pay: This is the figure that your Income Tax is actually calculated on. It’s your gross pay minus any non-taxable bits, like your pension contributions.
Deductions: This section details everything that gets taken out of your gross pay. It’ll almost always include:
- Income Tax: The amount taken based on your tax code and taxable pay.
- National Insurance (NI): Your contribution towards state benefits like the NHS and State Pension.
- Pension: Any contributions you’re making towards a workplace or private pension.
- Other Deductions: This could cover anything from student loan repayments to other agreed deductions.
Net Pay: This is the important one, your take-home pay. It's what’s left after all deductions have been subtracted from your gross pay. This is the amount that should land in your bank account.
Make a habit of checking your payslip carefully each month. For a deeper look at how umbrella companies present this, check out our insights into the PayStream service and what to expect. Staying on top of it puts you in complete control of your earnings.
How PAYE Works for Contractors
For contractors, getting to grips with the Pay As You Earn system is crucial, especially when you’re navigating the world of umbrella companies and IR35. If your contract is deemed 'inside IR35', it simply means that for tax purposes, you’re treated just like a regular employee. This is where an umbrella company steps in to become your essential partner.
At UmbrellaCompany.com, we effectively become your employer. We designed this structure specifically to manage all your tax and National Insurance contributions through the PAYE system, keeping you fully compliant with HMRC. You get the best of both worlds: the freedom of contracting with the administrative ease of being an employee.
It’s a straightforward approach that takes the headache of tax management off your plate, so you can just focus on delivering great work.
The Umbrella Company PAYE Process
When you join an umbrella company, the way your earnings flow is simple and transparent. Instead of you invoicing the client for your take-home pay, the entire gross payment for your hard work comes directly to us. We then run this through our payroll software, exactly as any traditional employer would.
From there, we calculate the precise amount of Income Tax and National Insurance Contributions (NICs) you owe, based on your earnings and specific tax code. We then pay these deductions straight to HMRC on your behalf, so your tax obligations are always met.
This little infographic breaks down how your money gets from the client to your bank account.
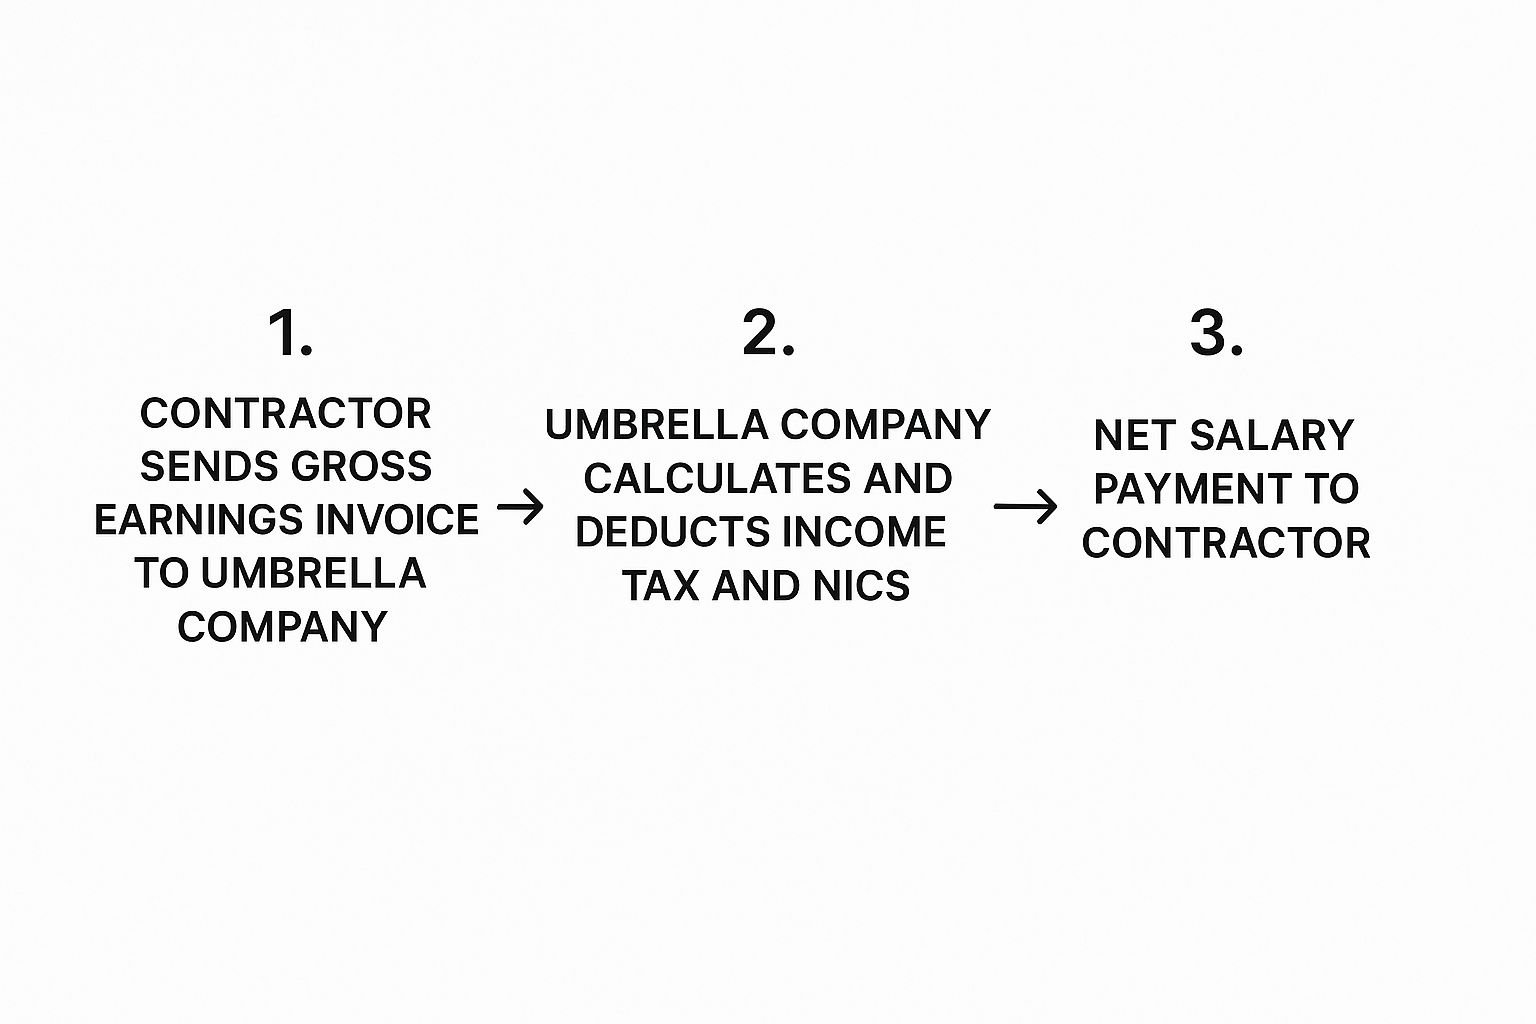
As you can see, the umbrella company is the vital link in the chain, turning your gross contract value into a fully taxed, compliant net salary.
Benefits Beyond Simple Payroll
But working this way is about more than just sorting out your taxes. By becoming an employee of an umbrella company like ours, you unlock a whole range of statutory employment rights and protections, things that are usually out of reach for self-employed professionals.
This creates a valuable safety net, bringing a welcome layer of security and stability to your contracting career. It nicely bridges the gap between the flexibility of contracting and the security of a permanent role.
Here are a few of the key benefits you’ll get:
- Statutory Sick Pay (SSP): If you’re too ill to work, you’re entitled to SSP, giving you a financial buffer while you recover.
- Statutory Holiday Pay: You build up paid time off for every hour you work, meaning you can take those well-earned breaks without your income dropping to zero.
- Access to a Workplace Pension: We’ll automatically enrol you into a workplace pension, helping you save for the future with contributions from your earnings.
- Continuity of Employment: Having one continuous employer, even while you work on different projects for different clients, creates a consistent employment history. This can be a huge help when applying for a mortgage or a loan.
By handling your Pay As You Earn obligations, an umbrella company not only ensures tax compliance but also unlocks the full suite of statutory rights that come with employment. It is a structure designed to support and protect contractors.
Making the Right Choice for Your Situation
Deciding how to operate as a contractor is a big deal. It directly impacts your take-home pay, your admin workload, and your legal standing. The main alternatives are usually setting up your own limited company or working as a sole trader.
Each route has different tax implications. Contractors often want to compare the numbers, and using a Sole Trader Vs Limited Company Calculator can help you see the differences. But if you’re working inside IR35, the decision is made for you: your income must be processed via PAYE. An umbrella company is simply the most efficient and compliant way to do this.
For a more detailed look at these structures, our guide on Umbrella Company vs PAYE gives you a complete breakdown to help you make an informed choice. Ultimately, the umbrella route offers a secure, hassle-free way to enjoy the perks of contracting without the administrative nightmare.
Navigating Common PAYE Problems
While the Pay As You Earn system is built to keep things simple, it is not always a perfect science. Glitches can happen, leaving you paying either too much tax or, worse, not enough. Getting your head around these common hiccups is the best way to get them sorted fast and keep your finances on an even keel.
One of the most common snags contractors and employees hit is being put on the wrong tax code. This little string of numbers and letters dictates exactly how much tax comes off your pay, so when it is wrong, the impact on your bank account can be significant. Do not panic, though, these things are usually straightforward to fix once you know what you’re looking at.
The Incorrect Tax Code Dilemma
Your tax code can shift for all sorts of reasons. Maybe you’ve just started a new contract, you’re juggling more than one income stream, or you've started getting company benefits. If HMRC does not have the latest info, they might issue a code that does not quite match your situation, leading to the wrong amount of tax being deducted.
Overpayments are surprisingly common. A 2018 report, for instance, found that PAYE overpayments hit a staggering £1.57 billion. It’s a clear sign of how easily wires can get crossed. You can dig into the details of these PAYE system challenges if you’re curious.
If you have a hunch your tax code is off, the best move is to get in touch with HMRC directly, either through your online personal tax account or by giving them a call. They’ll review your details and send an updated, correct code straight to your employer.
Being proactive is your best defence. Make a habit of checking your payslip against the tax code HMRC has sent you. It’s a simple check that can save you a world of financial headaches later on.
Changing Jobs and the Dreaded Emergency Tax Code
Switching jobs or contracts is another classic tripwire. When you start a new role, the single most important document is your P45 from your previous employer. It holds all the vital information needed to get you on the right tax code from day one.
If you cannot provide a P45, you will almost certainly be put on an emergency tax code (like W1, M1, or 0T). This is just a temporary fix that does not take into account any tax you've already paid that year, often resulting in you paying too much initially.
Here’s how you can avoid it or sort it out:
- Hand Over Your P45: As soon as you get your P45, give it to your new employer or umbrella company. Simple.
- Fill in the Starter Checklist: No P45? Your new employer will give you a starter checklist instead. Fill it out carefully, as this helps HMRC work out the right code for you.
- Check Your First Payslip: Once you get paid, double-check that the emergency code has been switched to your correct one. If it has not, have a word with your employer and HMRC.
For contractors, this is especially crucial when a contract is deemed inside IR35. Knowing what happens if you’re inside IR35 is key to staying compliant from the get-go. At UmbrellaCompany.com, we manage these complexities every day, ensuring you have a seamless transition between assignments and that your tax affairs are always in perfect order.
The Role of Real Time Information in PAYE
The biggest shake-up to the Pay As You Earn system since its inception was the introduction of Real Time Information (RTI). It completely changed the game, moving how employers report payroll to HMRC from a clunky, once-a-year summary to a live, continuous feed of information.
What this means in practice is that every single time you’re paid, your employer, including an umbrella company, has to send the details of your pay and deductions to HMRC electronically. Instantly. This gives HMRC an immediate, up-to-the-minute picture of your earnings, rather than waiting for an old-fashioned P60 to land on their desk at the year's end.
This move to live reporting has made the whole PAYE system far more accurate and responsive, which is a direct win for you as a contractor or employee.
Why Real Time Information Matters to You
The number one benefit of RTI is accuracy. Because HMRC has a constant flow of data about your earnings, your tax code is much more likely to be correct. This dramatically cuts the chances of you accidentally overpaying or underpaying tax throughout the year.
The result? Far fewer nasty surprises or frustrating refund claims when the financial year is over.
For contractors using an umbrella company, this real-time process offers total transparency. We report every payment we process for you straight away, guaranteeing your tax record is always spot-on and fully compliant. This is a crucial part of how an umbrella company works to keep you protected.
The key benefits really boil down to this:
- Fewer End-of-Year Surprises: With ongoing adjustments, massive tax discrepancies are now a rarity.
- Greater Accuracy: Live data helps HMRC keep your tax code and records precise.
- Simpler Administration: The whole reporting process is automated, ensuring compliance without the headache.
Before RTI, the PAYE system was like trying to settle a bar tab a year later using a shoebox full of crumpled receipts. Now, it’s like tapping your contactless card. The transaction is instant, accurate, and recorded in real time, giving everyone a clear and current financial picture.
A Wider Economic Impact
RTI is not just about individual tax affairs; it has also given the UK government an incredibly powerful tool for reading the health of the national labour market. The aggregated, anonymous data provides almost instant insights into employment levels, wage growth, and economic trends across the country.
This allows for much more informed, responsive economic policy-making. For example, joint data from HMRC and the Office for National Statistics can track subtle monthly shifts in the number of payrolled employees, showing exactly how the job market is reacting to economic events. This data has highlighted that while employee numbers grew, the pace of that growth has been slowing since April 2022, giving policymakers a vital heads-up.
You can dive into these earnings and employment trends on ONS.gov.uk yourself to see the data in action.
Ultimately, RTI has transformed PAYE from a simple tax collection tool into a dynamic, data-rich system that supports both your personal financial stability and the nation's economic strategy.
Your PAYE Questions Answered
Working with the Pay As You Earn system can throw up a few practical questions, especially for contractors. To help clear things up, here are some straightforward answers to the queries we hear most often.
What Should I Do If I Think My Tax Code Is Wrong?
If you suspect your tax code is wrong, it's best to act fast. An incorrect code means you're either paying too much tax or not enough, and neither is a good situation to be in.
The first step is to contact HMRC. You can do this through your personal tax account online or by giving them a call. Before you do, grab your National Insurance number and a recent payslip. HMRC will look into it and, if they find a mistake, they will send a new tax code directly to your employer or umbrella company to get your deductions corrected.
How Does Changing Jobs Affect My PAYE Tax?
When you finish up at a job, your old employer must give you a P45 form. This little document is essential. It shows how much you have earned and how much tax you have paid in the current tax year.
Make sure you give this P45 to your new employer. It allows them to put you on the right tax code straight away, so everything runs smoothly from your first payday. If you do not have a P45, you will probably be put on a temporary emergency tax code until HMRC sorts out the correct one for you.
Can I Get a Tax Refund If I Have Overpaid Through PAYE?
Yes, absolutely. If you have paid too much tax through PAYE, you are entitled to get it back. HMRC usually catches this automatically after the tax year ends on 5th April.
You will typically get a P800 tax calculation letter in the post from HMRC. This letter breaks down why you overpaid and gives you clear instructions on how to claim your refund online. It often happens if you were on the wrong tax code for a while or if you did not work for the whole year.
Does PAYE Cover My Self-Employment Income?
No, the Pay As You Earn system is only for income you get from an employer. If you have other earnings, say, from freelance work outside an umbrella company, rental income, or other significant investments, you need to declare it yourself.
This is usually handled by filling out an annual Self Assessment tax return. It’s how you report all your earnings to HMRC and make sure you’re paying the right amount of tax on your total income, keeping you fully compliant.
At UmbrellaCompany.com, we make tax compliance simple for contractors. Our platform helps you compare trusted, accredited umbrella companies to find the perfect fit for your needs, ensuring your PAYE is managed correctly every time. Find your ideal umbrella company in minutes by visiting https://umbrellacompany.com.


