


Figuring out what you'll actually take home can be a bit of a headache. Thankfully, a good net salary calculator for the UK does the heavy lifting, translating your gross salary into the real figure that hits your bank account. It takes the latest tax and National Insurance rates and gives you a clear estimate in moments.
This guide will explain how your pay is calculated, what deductions to expect, and how you can use a calculator to plan your finances with confidence.
What Really Happens to Your Gross Pay
Ever get a contract, see the headline rate, and then get a shock when your first payment comes through? You're definitely not alone. The journey from your gross pay, the total amount agreed before anything is taken off, to your net pay involves several mandatory deductions set by HMRC.
Getting your head around these is the first step to properly managing your finances as a UK contractor. Your gross salary is the starting block, but it’s not what you have to spend.
The Core Deductions Explained
For almost every worker in the UK, the two biggest chunks taken out of their pay are Income Tax and National Insurance Contributions (NICs). These are your contributions towards public services like the NHS, state benefits, and roads. How much you pay is tied directly to how much you earn; the more you make, the higher the percentage.
But it does not stop there. A few other common deductions can also shrink your gross pay before it gets to you.
These often include:
- Pension Contributions: If you’re paying into a workplace pension, this money is usually taken before tax is worked out. This is a good thing, as it means you get tax relief on your contributions.
- Student Loan Repayments: Got a student loan? As soon as you earn over a set threshold, repayments are automatically deducted from your pay.
All these deductions are broken down on your payslip. That is why learning how to read a payslip is such a vital skill for any contractor, it shows you exactly where every penny is going.
Below is a quick summary of the main deductions a salary calculator will factor in for you.
Key Deductions From Your Gross Salary
This table summarises the main deductions that a net salary calculator accounts for, turning your gross pay into your net take-home pay.
| Deduction Type | What It Is | Who It Applies To |
|---|---|---|
| Income Tax | A tax on your earnings, tiered into different percentage bands based on your income level. | Almost all earners in the UK, with different rates applying in Scotland. |
| National Insurance | Contributions that fund state benefits like the State Pension, Jobseeker's Allowance, and the NHS. | Employees and self-employed people earning over a certain threshold. |
| Pension Contributions | Your payments into a workplace or private pension scheme to save for retirement. | Employees who are auto-enrolled into a workplace pension, or anyone contributing voluntarily. |
| Student Loan Repayments | Repayments on government loans taken out for higher education. | Graduates earning above the repayment threshold for their specific loan plan. |
Each of these deductions serves a specific purpose, whether it is a legal obligation to the taxman or a personal investment in your own future.
Understanding the difference between gross and net pay is absolutely fundamental for financial planning. It stops any nasty surprises on payday and lets you budget with confidence, whether you are saving for a house or just managing your monthly bills.
Ultimately, a reliable net salary calculator for the UK crunches all these numbers for you. It gives you a realistic snapshot of your earnings after all the deductions, so you can plan your finances without any guesswork.
Calculating Your Contractor Take-Home Pay
Seeing your gross pay figure is one thing, but figuring out how much of that actually lands in your bank account is another beast entirely. Let's walk through a real-world scenario to demystify the process and show you how a net salary calculator UK models these deductions. This is not just about abstract rules; it is about following the money from your contract rate to your final payslip.
The journey from gross to net pay involves subtracting a few key deductions. The flowchart below gives you a bird's-eye view of how your total earnings are whittled down to your final take-home pay.
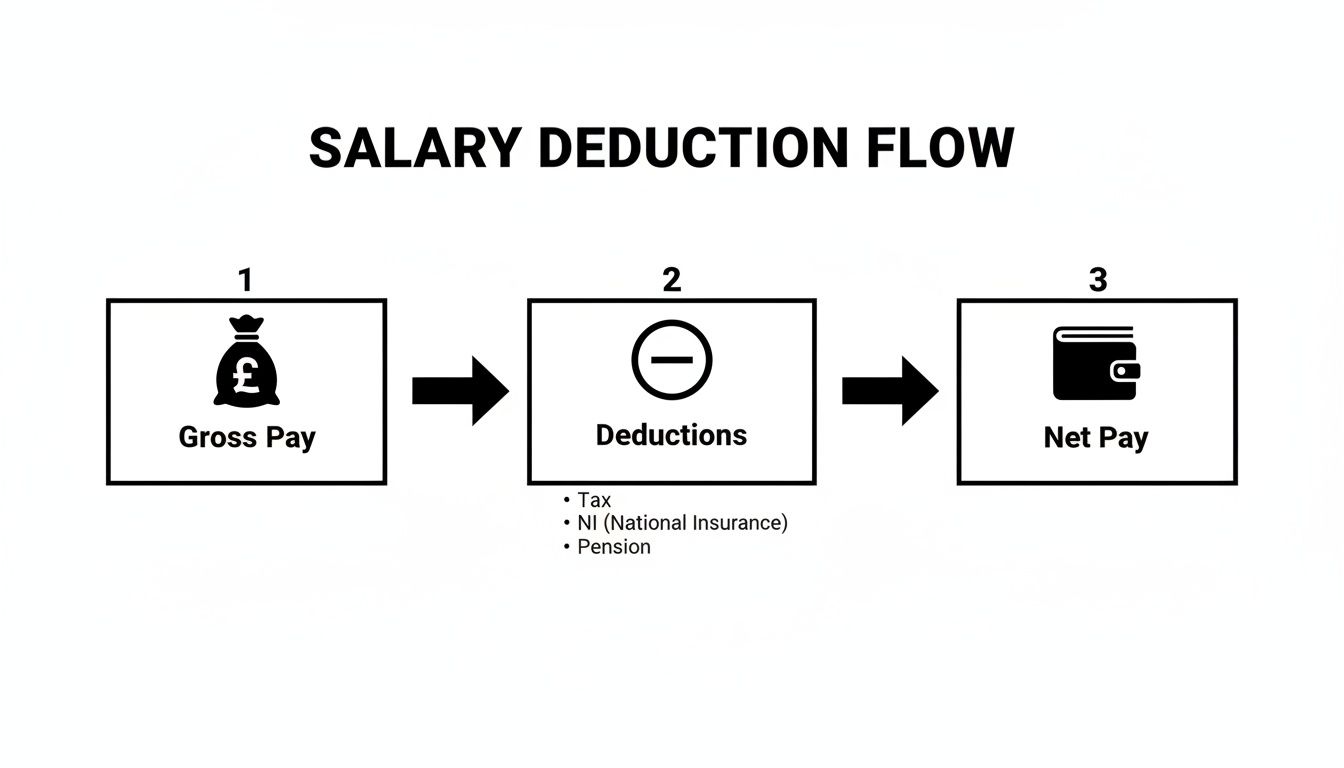
As you can see, your gross pay is just the starting line. The real story is told in the deductions for tax, National Insurance, and your pension.
A Practical Example: Alex the Contractor
To make this tangible, let's meet Alex. He’s an IT contractor working through an umbrella company with a gross salary of £55,000 per year. That breaks down to a monthly gross figure of £4,583.33.
Alex is on the standard tax code (1257L for the 2024/25 tax year) and contributes 5% to his workplace pension via auto-enrolment. He is also paying back a Plan 2 Student Loan.
Right, let's break down how Alex's take-home pay is actually calculated.
Applying Income Tax
The first big chunk to come out is Income Tax, which is applied in bands. Everyone gets a Personal Allowance, an amount you can earn completely tax-free. For the 2024/25 tax year, this is £12,570.
For Alex's £55,000 salary, the tax works out like this:
- First £12,570: Taxed at 0% = £0
- Next £37,700 (from £12,571 to £50,270): Taxed at the 20% basic rate = £7,540
- Remaining £4,730 (from £50,271 to £55,000): Taxed at the 40% higher rate = £1,892
Add it all up, and Alex's total annual Income Tax comes to £9,432, which is £786 per month.
Factoring In National Insurance Contributions
Next up is National Insurance Contributions (NICs), another mandatory deduction. NICs work a bit like Income Tax, with different rates for different earnings bands, but the thresholds are slightly different. For the 2024/25 tax year (assuming Alex is on NI Category A):
- First £12,570: 0% NICs
- Earnings from £12,571 to £50,270: 8% NICs
- Earnings over £50,270: 2% NICs
Let’s run the numbers for Alex's annual NICs:
- £37,700 (the portion between £12,571 and £50,270) at 8% = £3,016
- £4,730 (the portion above £50,270) at 2% = £94.60
This gives Alex a total annual National Insurance bill of £3,110.60, or £259.22 per month. Getting these figures right is absolutely crucial for accurately forecasting your contractor take-home pay.
Deducting Pension Contributions
Alex is putting 5% of his gross salary into his workplace pension. This is calculated before tax, which is a massive plus as it provides some very welcome tax relief.
A 5% contribution on £55,000 is £2,750 per year, which works out to £229.17 a month.
One of the smartest things you can do is get your head around how pension contributions affect your net pay. Because they’re taken from your gross salary, they lower your taxable income. This means you pay less Income Tax, essentially getting a government top-up on your retirement savings.
Including Student Loan Repayments
Finally, we need to account for Alex's Plan 2 Student Loan. Repayments for this plan are set at 9% of any income you earn above the annual threshold of £27,295.
Alex's earnings above that threshold are £55,000 – £27,295 = £27,705.
So, his annual repayment is 9% of £27,705, which comes to £2,493.45. That is £207.79 coming out of his pay each month.
The Final Take-Home Pay Calculation
Now we can put all the pieces together and see what Alex is left with at the end of the month.
- Gross Monthly Pay: £4,583.33
- Less Income Tax: -£786.00
- Less National Insurance: -£259.22
- Less Pension Contribution: -£229.17
- Less Student Loan: -£207.79
Alex's Monthly Net Pay = £3,101.15
This step-by-step example shows you exactly where the money goes. While the numbers can seem daunting, a good online calculator automates this whole process, applying the correct tax bands and thresholds in an instant. It gives you the clarity you need to budget, plan, and feel confident about your finances as a contractor.
Putting Our Net Salary Calculator to Work
Now you’ve got the theory down, it’s time to get a clear, instant answer for your own situation. We’ve built our own net salary calculator UK contractors can use for a swift and accurate estimate of their take-home pay.
This tool is designed to cut through the complexity. Instead of wrestling with tax bands and National Insurance thresholds yourself, you can get a realistic projection in seconds. We keep it constantly updated with the latest HMRC rates and rules, so you can trust the numbers when you are planning your finances.
Getting Started With the Calculator
Using the calculator is simple. We have laid it out to capture the essential information needed for an accurate calculation without bogging you down in jargon. You just need to pop in a few key details about your contract and personal circumstances.
The main fields you’ll need to fill in are:
- Your Gross Pay: This is the headline figure for your contract. You can enter it as a daily, weekly, monthly, or annual rate, and the calculator will handle the rest.
- Your Tax Code: For most people, this will be the standard 1257L. If HMRC has given you a different code, it is really important to enter it here, as it directly affects how much you can earn tax-free.
- Pension Contributions: If you’re paying into a workplace pension, enter the percentage here. Do not skip this, it reduces your taxable income, so it makes a real difference.
Once you’ve filled in these core details, the calculator gets to work.
Understanding Your Results
After you enter your information, our calculator crunches the numbers instantly. It applies the correct Income Tax bands, works out your National Insurance contributions, and deducts your pension payments plus any student loan repayments you’ve told it about.
The result is a simple breakdown of your earnings, showing:
- Your gross pay for the period.
- A summary of all your deductions.
- Your final net or take-home pay.
This gives you immediate and powerful insight into your finances. It takes the guesswork out of your payslip and lets you see exactly how each deduction nibbles away at your gross pay.
Using a dedicated contractor calculator is about more than just satisfying curiosity. It’s a vital budgeting tool that empowers you to make informed financial decisions, from negotiating new contract rates to planning major life purchases with confidence.
Our net salary calculator for the UK is built to give you this clarity. It translates complex payroll rules into a simple, digestible format, giving you the figures you need to plan ahead. Think of it as your first step towards taking full control of your contractor finances.
Figuring Out Your Pay as an Umbrella Contractor
If you’re a contractor working through an umbrella company, you have probably noticed your pay structure is a bit different from a standard permanent job. It’s a common point of confusion, but getting your head around it is crucial for planning your finances and making sure there are no nasty surprises on payday.
Let's clear it up.
The first thing to nail down is the difference between your assignment rate (what the agency pays for your services) and your actual gross pay for tax. They are two very different numbers. The assignment rate is the total amount your recruitment agency pays to us, UmbrellaCompany.com, for the work you've done. This figure is all-inclusive, meaning it covers all employment costs.
Before we can even get to your salary, several deductions have to come off that assignment rate. These are not random fees; they are the legitimate, legally required costs of being your employer.
Breaking Down Your Assignment Rate
Think of the assignment rate as the total cost to the agency for hiring you. From this initial pot of money, we have to cover all the statutory employment costs first. Only then can we work out your gross pay.
Here’s what needs to be deducted from the assignment rate:
- Employer’s National Insurance Contributions (NICs): This is a tax every single UK employer has to pay to HMRC on their employees' earnings. It’s currently calculated at 13.8% on any earnings above the secondary threshold.
- The Apprenticeship Levy: Another government tax on UK employers, this is used to fund apprenticeship training. It is set at 0.5% of the annual pay bill for any employer whose bill tops £3 million.
- Our Umbrella Margin: This is our fee for running your payroll, arranging your insurance, providing HR support, and making sure you get paid correctly and on time. It is a simple, fixed amount taken either weekly or monthly.
Once these employment costs are taken care of, the money that is left over becomes your gross pay. This is the figure that is then subject to the usual deductions you’d expect, like Income Tax and your own employee NICs.
Why Do I Have to Cover Employer Costs?
This is probably the most common question we get asked. The answer is all about how contractor rates are set in the first place. The assignment rate you agree with an agency is deliberately "uplifted" or inflated to cover these exact costs. A permanent employee never sees these on their payslip because their employer handles them separately out of company revenue.
As an umbrella contractor, the agency pays a single, inclusive rate to us. We then have a legal responsibility to pay the employer's contributions to HMRC on your behalf. It’s the only compliant way for an umbrella company to operate under UK law.
Any compliant umbrella company will show you these deductions clearly on your reconciliation statement. If you ever see a provider promising you can take home an unbelievably high percentage of your contract rate, like 85% or 90%, it is a massive red flag. This almost always points to a non-compliant tax avoidance scheme.
Staying compliant is about protecting you from future headaches with HMRC, like investigations and unexpected tax bills. It’s a core part of the peace of mind we provide.
How IR35 Fits into Your Pay
The IR35 legislation, or off-payroll working rules, is another key piece of the puzzle. These rules are there to figure out if a contractor is genuinely self-employed or, for tax purposes, a ‘disguised employee’.
If your contract is determined to be ‘inside IR35’, it means your working relationship is treated like a permanent employee's. Because of this, you have to be taxed at source through Pay As You Earn (PAYE), just like anyone on a company's payroll. This is where an umbrella company becomes essential, as we manage all those PAYE deductions for you.
For contractors and freelancers, getting this distinction right is vital. Confusing the gross assignment rate with your net umbrella pay could leave you overestimating your take-home pay by hundreds of pounds every month.
This is where a good net salary calculator for UK contractors becomes so valuable. By plugging in your assignment rate, you can get a realistic forecast of what you’ll actually see in your bank account after all employment costs and taxes have been handled correctly. We have built our service and tools to give you this clarity from day one. To learn more, check out our guide on how an umbrella company for freelancers works. It’s all about making sure there are no financial shocks so you can focus on doing what you do best.
Other Factors That Can Change Your Net Salary
While Income Tax and National Insurance are the big deductions everyone talks about, a few other personal details can make a real difference to your final take-home pay. A good net salary calculator for the UK will have fields for these, but it pays to understand what they are and why they matter for your own financial planning.
It’s these specifics, from your student loan plan to the tax code HMRC puts you on, that make your payslip unique. Getting them right is the key to turning a rough guess into a genuinely accurate salary estimate.
How Student Loan Plans Affect Your Pay
Not all student loans are the same, and the type you have dictates when you start paying it back and how much comes out of your pay packet each month. This is a crucial detail to get right in any calculation.
The UK has several repayment plans, and each one comes with a different annual earnings threshold. You only begin making repayments once your income tips over that specific line.
- Plan 1: For students who started courses before 1 September 2012. You pay back 9% of what you earn over £24,990.
- Plan 2: For students who started courses between 1 September 2012 and 31 July 2023. The threshold is higher at £27,295, but the repayment is still 9% of your earnings above it.
- Plan 4 (Scottish): For Scottish students, repayments are 9% on income over £31,395.
- Plan 5: For anyone starting a course from 1 August 2023. You’ll repay 9% on earnings over £25,000.
- Postgraduate Loan: This is for Master's and Doctoral loans. Repayments are lower at 6%, but the threshold is also lower at £21,000.
As you can see, the difference between plans can be significant. Making sure you select the right one is essential for an accurate net pay calculation.
Understanding Your UK Tax Code
Your tax code is a short string of numbers and letters that tells your employer how much tax-free income you get in a tax year. HMRC issues it, and it can change depending on your circumstances.
For the 2024/25 tax year, the most common code is 1257L.
This code simply means you have the standard tax-free Personal Allowance of £12,570. The 'L' just confirms you are entitled to it. Your code might be different, though, if you have a second job, get benefits from work (like a company car), or perhaps underpaid tax in a previous year.
An incorrect tax code is one of the most common reasons people end up overpaying or underpaying tax. It is always a good idea to check the code on your payslip and make sure it matches any letters you've had from HMRC.
If HMRC sends you a notice with a new tax code, it is vital to update it in any salary calculator you use. A different code directly alters your tax-free allowance and, in turn, your net salary.
The Impact of Salary Sacrifice Schemes
Salary sacrifice is where you agree to give up a portion of your gross salary in return for a non-cash benefit from your employer. This is often used for things like extra pension contributions, a cycle-to-work scheme, or even an electric car.
The big advantage here is the savings on tax and National Insurance. Because you have technically lowered your gross salary, you pay both tax and NI on a smaller amount.
For instance, if you sacrifice £100 a month into your pension, your taxable income for that month is reduced by £100. It is a very tax-efficient way to boost your retirement savings. Many contractors use this method to optimise their earnings, making it a key factor when comparing the benefits of an umbrella company to other routes. It is a similar kind of financial optimisation to weighing up a salary versus dividends as a limited company director.
Each of these factors, student loans, tax codes, and salary sacrifice, plays a vital role in figuring out your final net pay. By paying close attention to these personal details, you can move from a rough estimate to a much clearer picture of your true financial position.
Your Contractor Pay Questions Answered
Getting to grips with contractor pay can be a bit of a minefield, especially when you are starting out. We get asked the same questions time and again from contractors trying to make sense of their payslips.
To help you get ahead, we’ve put together some clear, straightforward answers to the most common queries we see. Think of this as your go-to guide for those nagging questions about your take-home pay.
Why Does My Payslip Not Match the Calculator's Estimate?
Our net salary calculator UK is designed to give you a really accurate forecast based on standard tax information. But sometimes, your actual pay might be slightly different. Why? It usually comes down to personal circumstances.
For instance, HMRC might have issued you a non-standard tax code, maybe to collect some underpaid tax from a previous year. You might also have other deductions coming off, like for workplace benefits or specific salary sacrifice schemes you’ve opted into.
Always treat your official payslip as the final word. The calculator is a fantastic tool for planning and budgeting, but just remember it’s a powerful estimate, not a guarantee.
What is the Difference Between Employee and Employer National Insurance?
This is a big one, and it catches a lot of new umbrella contractors out. It’s actually quite simple.
As an employee of UmbrellaCompany.com, you pay Employee's National Insurance directly from your gross pay. It is the same for every employee in the UK, and you will see it clearly itemised on your payslip.
Then there is Employer's National Insurance. As your legal employer, the umbrella company has to pay this to HMRC on your earnings. It’s a standard cost of employment, and it is factored into the assignment rate agreed with your agency before your own gross salary is calculated. This is a completely standard and compliant practice across the industry.
How Often Should I Check My Net Salary?
It’s a really smart habit to run the numbers whenever your contract or financial situation changes. It keeps your budget on track and means you will not get any nasty surprises when your pay hits the bank.
We’d recommend using a calculator in a few key situations:
- Starting a new contract: Get a clear picture of your earnings right from the start.
- Beginning of a new tax year: Rates for tax and NI often change in April, so it is good to see how that affects you.
- If HMRC changes your tax code: A new code can make a big difference to your take-home pay.
- When you change your pension contributions: Bumping your contributions up or down will naturally impact your net salary.
Regular checks just help you stay in control of your money. Simple as that.
Think of a net salary calculator as a financial health check. Running the numbers regularly ensures you understand your true earning power and can plan for the future with confidence, whether you are saving for a deposit or managing monthly expenses.
Ultimately, staying on top of your pay is one of the most important parts of being a successful contractor. By understanding these key details and using tools like a net salary calculator, you can manage your finances effectively.
At UmbrellaCompany.com, we give you the tools and support you need to make your contracting journey as smooth as possible. You can compare trusted, compliant umbrella companies in minutes and find the perfect partner for your career.
Find your ideal umbrella company with our comparison tool


