


Think of IR35 insurance as your business's financial backstop. It’s a specialised policy designed to shield you from the significant costs of an HMRC investigation into your employment status, covering fees for accountants and legal experts. This guide explains what it is, why it matters, and how to choose the right cover.
What Is IR35 Insurance and Why It Matters Now
If you're contracting in the UK, you cannot ignore IR35. Receiving a letter from HMRC launching an enquiry is a stressful and costly distraction, even if you are certain your contract is correctly outside IR35. This is precisely where IR35 insurance offers much-needed peace of mind.
At its heart, this insurance covers the costs of defending your business if HMRC comes knocking. The financial fallout from an enquiry can be substantial, often running into thousands of pounds for specialist tax and legal advice alone. Without a policy, those costs land squarely on your limited company.
The Primary Purpose of IR35 Cover
The main job of an IR35 insurance policy is to mount a robust defence for you. If HMRC decides to put one of your contracts under the microscope, the policy pays for a team of specialists to handle the entire process on your behalf. This lets you get on with your work without the constant worry of a compliance battle.
This kind of protection has become more vital than ever. With HMRC sharpening its focus on contractor compliance and the off-payroll rules getting trickier, the risk of an investigation is a genuine concern for most independent professionals.
Having a policy in place sends a strong signal that you take your compliance responsibilities seriously. It shows you are a legitimate business, ready to defend your status with professional support.
Key Benefits for Contractors
Understanding the value of this insurance is a key part of managing your business risk. Here is what it brings to the table:
- Financial Protection: It covers the potentially huge costs of professional representation, from tax accountants to legal experts, who you will need to manage an HMRC enquiry.
- Expert Defence: You get immediate access to seasoned IR35 specialists. These experts live and breathe this legislation and know how to build the strongest possible case for your defence.
- Peace of Mind: Knowing you have a financial and professional buffer lets you focus on your clients and growing your business, not on the threat of a costly investigation.
- Business Credibility: Holding proper business insurance, including IR35 cover, reinforces your status as a genuine business, completely separate from an employee.
Ultimately, IR35 insurance is not just about a potential tax bill. It is about protecting your business from the disruptive and expensive process of an HMRC investigation. For a deeper look into the rules, you can learn more about what IR35 is and why it matters to UK contractors in our detailed guide.
Decoding the Different Levels of IR35 Insurance Cover
Navigating the world of IR35 insurance can feel overwhelming. Not all policies are created equal, and understanding the different tiers of cover is the only way to pick one that fits your needs as a contractor, without paying for extras you will never use.
Most providers package their policies into three main levels. Think of it as a ladder, where each rung offers more protection than the last, safeguarding you against the serious financial risks of an HMRC investigation. Let's break down what you can typically expect.
Basic Cover: Tax Enquiry Insurance
The entry-level option is often called Tax Enquiry Insurance. Its main job is to cover the professional fees you would face if HMRC decides to launch an investigation into your status. It pays for specialist accountants and legal experts to handle the process and build a solid case on your behalf.
This type of policy is your foundational safety net. It means you have an expert team in your corner from day one, which is vital for navigating the complex enquiry process. However, this basic cover will not pay for any tax liabilities, interest, or penalties if HMRC ultimately decides you fall inside IR35.
Comprehensive Cover for Tax Liabilities
Moving up a level, you get to a more comprehensive policy. This includes everything from the basic cover, so all your professional defence fees are sorted, but adds a critical layer of protection. If the investigation does not go your way, this policy will also cover the final bill from HMRC, including back-taxes, interest, and any penalties.
This is by far the most popular choice for contractors. It tackles the two biggest financial threats of an IR35 challenge head-on. Not only does it fund your defence, but it also settles the bill if the worst-case scenario plays out, protecting your business from what could otherwise be a crippling financial blow.
As you can see, it is all about creating a financial safety net, covering the costs of a dispute, and ultimately, giving you back your peace of mind.
Premium Cover with Additional Protections
For contractors who want the highest level of security available, premium policies offer the most extensive protection. On top of covering defence costs and tax liabilities, these plans often bundle in valuable extras designed to minimise the wider disruption an investigation can cause.
Some common additions you might find in premium tiers include:
- Loss of Earnings Cover: This compensates you for the time you are forced to take away from your contract work to deal with meetings or hearings.
- Retrospective Cover: A huge benefit for some, this can extend your cover to contracts you worked on before the policy even started.
- Higher Indemnity Limits: Premium options typically come with much higher cover limits, perfect for those on high-value contracts. It is not unusual to see cover ranging from £100,000 to over £1 million.
Comparing Tiers of IR35 Insurance Cover
To make it clearer, here is a simple table breaking down what you generally get with each level of cover.
| Feature | Basic Cover | Comprehensive Cover | Premium Cover |
|---|---|---|---|
| Professional Defence Fees | Yes | Yes | Yes |
| Tax Liabilities & Penalties | No | Yes | Yes |
| Retrospective Contract Cover | No | Sometimes | Yes |
| Loss of Earnings | No | No | Often Included |
| Higher Indemnity Limits | Standard | Standard | Yes |
Of course, the specifics can vary between insurers, but this gives you a solid idea of how the protection stacks up.
While premium policies naturally come at a higher price, they provide an all-encompassing shield for your business. It is also worth remembering that IR35 insurance is just one piece of the puzzle. We have a separate guide to contractor indemnity insurance that covers other key protections you should consider. In the end, choosing the right level of IR35 cover is a personal decision, about balancing your specific risk against your budget.
Do I Actually Need IR35 Insurance?
Figuring out if you need IR35 insurance boils down to one simple question: who is responsible for deciding your tax status? While recent reforms pushed this job onto clients for many contracts, there is a huge exception. If your client is a 'small' business, the responsibility, and all the financial risk, lands right back on your limited company's doorstep.
This distinction is more critical than ever. The goalposts for what defines a 'small' company have recently moved, meaning more contractors are finding themselves making their own IR35 status calls. Deciding whether to get insured is a fundamental part of managing your business risk in this new landscape.
It All Comes Down to Your Client's Size
The off-payroll working rules, which force the end client to issue a Status Determination Statement (SDS), only apply to medium and large businesses. When you work for a client that qualifies as 'small' under the Companies Act 2006, the original IR35 rules from 2000 apply. In that situation, you are legally responsible for determining your own IR35 status.
If HMRC disagrees with your 'outside IR35' assessment, they will investigate your limited company. This is why IR35 insurance becomes a lifeline for any contractor working with small businesses. Without it, you would be left funding the entire legal and accountancy defence yourself, not to mention any back-taxes and penalties if you lose.
Heads up: The government recently expanded the definition of a 'small' company. Businesses you might have thought were medium-sized could now fall into this category, making it more likely that you will be responsible for your own IR35 status.
Recent Changes That Increase Your Risk
The rules have changed, and it directly impacts your need for IR35 insurance. From April 2025, the government raised the thresholds for what defines a ‘small’ company. The turnover limit increased from £10.2 million to £15 million, and the balance sheet total grew from £5.1 million to £7.5 million. The employee count remains at 50 or fewer.
This means that a host of businesses that were previously medium-sized now count as small. This automatically shifts the IR35 determination duty back onto the contractor's personal service company (PSC). As a contractor, you are now much more likely to have to make the status call yourself, which naturally raises the risk of an HMRC challenge.
How to Figure Out Your Personal Risk Level
Beyond your client's size, a few other things should factor into whether insurance is a smart move. Think about these points when you are weighing up your own risk profile:
- Industry Scrutiny: Some sectors are on HMRC's radar more than others. IT, public sector roles, and media have always been hotspots for investigations. If you work in one of these fields, your risk is probably higher.
- Contract Clarity: How watertight is your contract? If the wording is vague or has clauses that could look like employment (like a weak substitution clause), your position is less secure. This is when insurance becomes a real safety net.
- Working Practices: What you do day-to-day must match what is in your contract. If you act like an employee even though your contract says you are a consultant, you create a weak spot that an HMRC inspector would target.
- Your Financial Buffer: Could your business take the hit of an IR35 defence? We are talking tens of thousands of pounds in professional fees, plus a potential tax bill. If that thought makes you nervous, insurance is your financial backstop.
Ultimately, deciding if your contract is inside or outside IR35 is a tricky business. For a deeper dive, take a look at our guide on making the correct inside or outside IR35 determination. A clear-eyed look at these risks will help you decide if IR35 insurance is a 'nice-to-have' or an absolute must.
Understanding Policy Exclusions and Small Print
An insurance policy is only as good as what is written in the small print. When it comes to IR35 insurance, this could not be more true. You must get into the details of the terms and conditions to make sure the cover you are paying for will actually step in when you need it. Let’s shine a light on the crucial details you cannot afford to skim over.
These policies are there to protect contractors who have made a genuine effort to operate compliantly. They are not a get-out-of-jail-free card for anyone deliberately trying to bend the rules. Knowing the common exclusions from the outset will save you from costly surprises down the line if you ever have to make a claim.
Common Policy Exclusions You Must Know
Every IR35 insurance policy will list specific situations it will not cover. Think of these exclusions as the insurer's way of making sure the policy is used as intended: to defend a contractor who has acted in good faith. Being aware of them is your first step towards picking the right protection.
A classic exclusion relates to the timing of your contract reviews. Many insurers will only cover you if your contracts were professionally assessed as 'outside IR35' before you started the work or took out the policy. This is a big one. You cannot get into trouble with HMRC and then buy insurance to solve the problem.
Another key area to watch is the idea of 'reasonable care'. If you cannot show that you have taken sensible, documented steps to determine your IR35 status, your claim could easily be rejected. This means keeping good records of your working practices, getting expert advice, and making sure how you work day-to-day matches what your contract says.
An insurance policy supports your compliant business practices; it does not replace them. Insurers expect you to have done your homework and will check this before paying a claim.
Key Limitations and What to Look For
It is not just about what is excluded; policies also have limits on how much they will pay out. It is vital to check the indemnity limits for different parts of a potential claim, as they can vary. For instance:
- Legal Fees: Look at the maximum amount the policy will pay for professional representation. A dispute with HMRC can get expensive fast, so you need to be sure this limit is realistic.
- Back Taxes and Penalties: If your policy includes cover for tax liabilities, there will be a cap on the total payout. Make sure this number is high enough to cover your potential exposure, which will depend on your contract value.
- Time Limits: Policies often have restrictions on how far back they will cover previous contracts. This is usually called retrospective cover and it is a key feature to look for if you have past projects that were not insured.
Before you commit to anything, always ask the provider for the full policy wording. Reading this document carefully is non-negotiable. Watch out for vague or ambiguous language and look for clear definitions. For wider protection, it is also smart to explore other types of business cover; you can find more information in our complete guide to contractor insurance in the UK. At the end of the day, knowing what is not covered is just as important as knowing what is.
Building a Complete IR35 Risk Management Strategy
Relying solely on IR35 insurance to protect your business is like fitting a smoke alarm but never checking for fire hazards. It is an essential safety net, but it cannot be your entire plan.
A truly robust approach to IR35 is proactive, not just reactive. It is about building such a strong 'outside IR35' case from the start that an HMRC investigation becomes far less likely. This means embedding compliance into your daily operations. Insurance is there for the worst-case scenario, but a solid strategy aims to prevent that from ever happening.
Let's look at the other essential pieces that work alongside insurance to create a comprehensive shield for your contracting business.
Proactive Measures Beyond Insurance
The best defence against an IR35 challenge is to consistently think and act like a genuine business. You need to demonstrate at every turn that you are a separate commercial entity, not a 'disguised employee'. Several proactive steps can help cement this position, reducing your reliance on an insurance policy alone.
A cornerstone of this strategy is getting an independent, expert contract review for every new engagement. An IR35 specialist will analyse both the contractual terms and your intended working practices, giving you a professional opinion on your status and flagging potential red flags before you start the work.
Another powerful tool is keeping a detailed record of your working practices. This could include:
- A Confirmation of Arrangements (CoA) document: This is a simple but effective statement signed by you and your client. It outlines the day-to-day reality of the engagement, confirming key 'outside IR35' indicators like your autonomy and right to use a substitute.
- Maintaining business evidence: This sounds obvious, but it matters. Having a professional website, a dedicated business bank account, and your own company-branded stationery all help paint a clear picture of a legitimate, independent business.
The Problem with Relying on HMRC's CEST Tool
For a while, many contractors and clients turned to HMRC's own Check Employment Status for Tax (CEST) tool for a quick verdict. Confidence in this tool, however, has plummeted.
HMRC’s own data shows that CEST usage dropped from 806,432 uses in 2021–2022 to just 138,758 in 2023–2024. That is a staggering 73% decline. This freefall is linked to a growing belief that the tool is unreliable, often produces an 'undetermined' result, and can be easily manipulated. You can read more about the decline in CEST tool usage on kingsbridge.co.uk.
This erosion of trust makes independent, expert assessments more critical than ever. It underscores the danger of relying on a single, flawed source for such a crucial determination and reinforces the need for a multi-layered risk management strategy.
A robust defence is built on evidence. Combining an expert contract review, a signed CoA, and a clear record of business-like behaviour creates a powerful file that can stop an HMRC enquiry in its tracks.
An Alternative Route: Working Through an Umbrella Company
For some contractors, the most straightforward way to manage IR35 risk is to sidestep it entirely. Working through a compliant umbrella company offers a simple and effective alternative to operating your own limited company (or PSC).
When you join an umbrella company, they become your employer for tax purposes. They handle all your PAYE tax and National Insurance contributions, ensuring you are fully compliant with HMRC's rules. This structure means IR35 legislation no longer applies to your engagement because you are already being taxed as an employee.
This route provides complete peace of mind, freeing you from the headache of status determinations, contract reviews, and the need for IR35 insurance. It is a practical choice for contractors who prioritise simplicity and certainty over the potential tax efficiencies of running a PSC.
Your Practical Checklist for Managing IR35 Risk
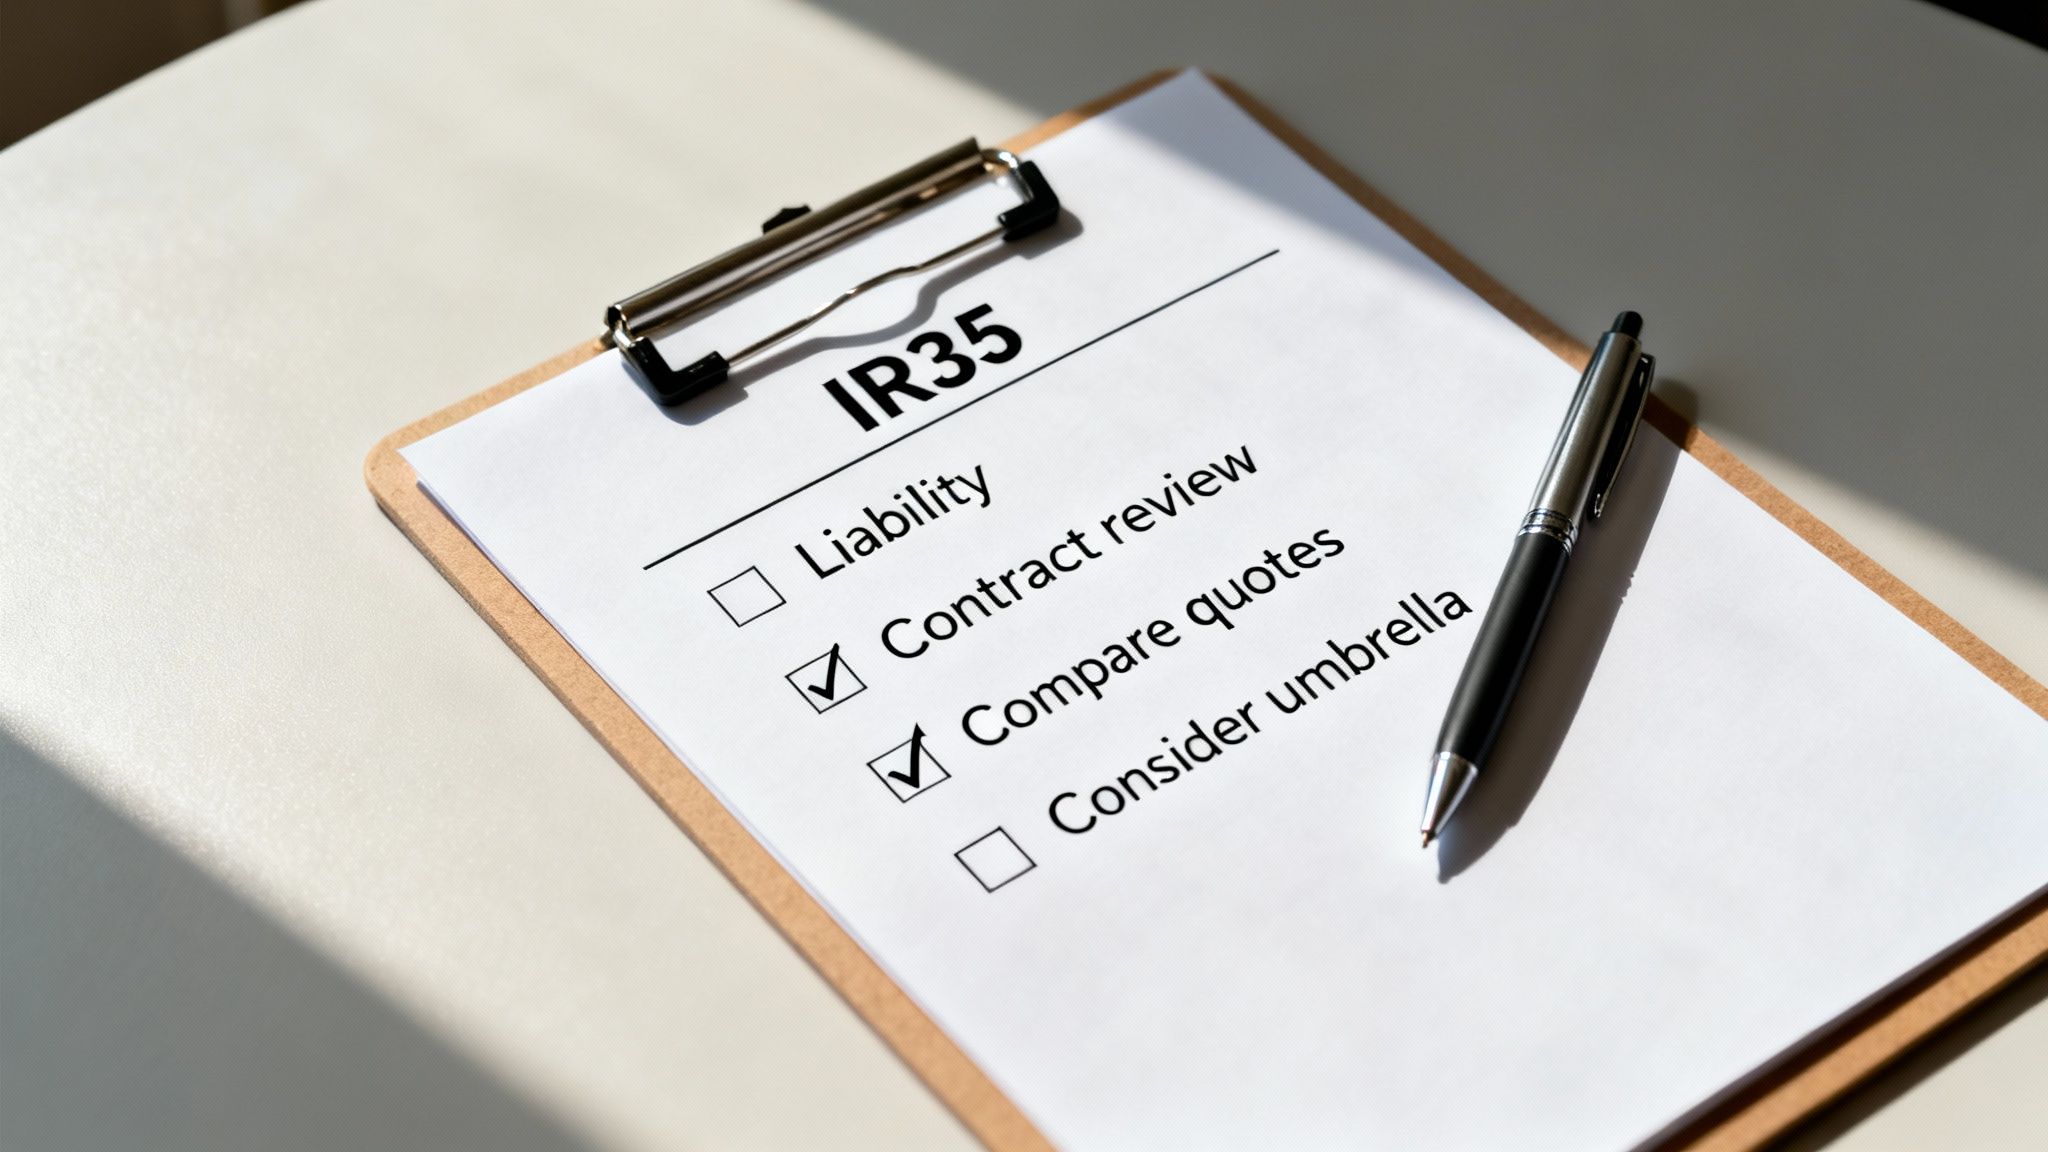
Tackling IR35 risk is all about being proactive. You cannot just wait and see. This checklist breaks down the essential steps into a straightforward plan, giving you the confidence to manage your compliance and protect your contracting business.
Follow these steps to get a clear picture of your situation and decide what action to take.
Assess Your Liability First
Before you do anything else, you need to know who is liable for the IR35 decision on your contract. If your client is a medium or large business, the responsibility is theirs to issue a Status Determination Statement (SDS).
But if you are working for a 'small' business, the tables turn. The liability for determining your IR35 status falls squarely on your own limited company. This is the exact point where proper protection like IR35 insurance goes from being a 'nice-to-have' to a critical business safeguard.
Get Your Contracts and Practices Professionally Reviewed
A solid defence against an HMRC challenge is built on hard evidence. Never start a contract without getting both the written agreement and your actual working practices reviewed by an IR35 specialist. In fact, most insurers will insist on this independent check before they will offer you cover.
To add weight to your case, get a Confirmation of Arrangements (CoA) document signed. It is a simple statement, co-signed by you and your client, that confirms the day-to-day reality of your engagement and backs up your 'outside IR35' status.
Evaluate Your Insurance Options
Once you know your risk level, it is time to shop around for IR35 insurance. Do not just look at the price tag. Dig into the policy details to make sure the cover truly fits your needs.
Here is what to check:
- Level of Cover: Does it just pay for professional fees to fight your case, or does it also cover the big-ticket items like back-taxes, interest, and any penalties?
- Indemnity Limits: Is the maximum payout high enough? A policy that is too small for your contract value will not do you much good.
- Exclusions: Scrutinise the small print. Are there get-out clauses, like needing a contract review before the start date, that could render your policy useless when you need it most?
Taking these steps transforms IR35 from a source of anxiety into a manageable business risk. It demonstrates that you are a diligent, professional business owner who takes compliance seriously.
Consider Compliant Alternatives
Finally, step back and look at the bigger picture. While IR35 insurance is a fantastic tool for PSC contractors, it is not your only option. For some, the simplicity and certainty of working through a compliant umbrella company is a better fit, as it removes the IR35 headache entirely.
As specialists in this area, we at UmbrellaCompany.com can help you figure out which solution is right for you. Whatever path you choose, getting expert, compliant advice is the single most important step you can take to secure your contracting career.
Got Questions About IR35 Insurance? We've Got Answers
Digging into the details of IR35 insurance often raises a few recurring questions. To give you the confidence to make the right call, we have tackled some of the most common queries we hear from contractors just like you.
Understanding these points is key to seeing where this cover fits into your wider strategy for protecting your business.
Can I Get Insurance After My Contract Starts?
This is a classic question, but the answer is nearly always a firm "no." Insurers are strict on this: you need to have cover in place before you start the work. Think of it as a preventative measure. IR35 insurance is there to shield you from future risks, not to step in and cover an investigation that is already on the cards.
You might find some premium policies that offer a bit of retrospective cover for work you have already done, but that is the exception, not the rule. The golden rule is simple: get your insurance sorted before day one of the contract. That is the only way to be sure you are protected from the get-go.
Does Insurance Guarantee an Outside IR35 Status?
This is a crucial point to grasp: IR35 insurance does not and cannot change your actual IR35 status. An insurance policy is a financial safety net, not a badge of compliance. Its job is to pay for your legal defence and cover any tax liabilities if HMRC decides to challenge your status and wins.
It's similar to having car insurance. It does not stop you from having an accident, but it is there to cover the costs if you do. In the same way, IR35 insurance is there to handle the financial fallout of an investigation, not to prevent one from happening.
What really determines your IR35 status is the reality of your contract and your day-to-day working practices. The insurance is simply the backstop that lets you defend that status without putting your business's finances on the line. A solid defence always begins with a proper, independent status review.
Is IR35 Insurance a Tax-Deductible Expense?
Yes, it is. For any contractor running their business through a limited company, the premium for an IR35 insurance policy is almost always seen as a legitimate business expense. This is because the policy is taken out 'wholly and exclusively' for the purposes of your trade.
This means you can offset the cost of the premium against your company’s profits, which helps to lower your overall Corporation Tax bill. This tax relief makes the real cost of protecting your business even more affordable, highlighting its value as a smart investment in your financial security.
Staying on the right side of IR35 is a huge part of life as a contractor, and having the right support can make all the difference. At UmbrellaCompany.com, we give you the tools and guidance to compare compliant solutions, so you can focus on your work with total confidence. Find the right path for your contracting career by exploring your options with us.


