


You're probably in the middle of a familiar comparison.
One contract looks attractive because the day rate is higher, but it's inside IR35. Another looks cleaner because it's outside IR35, yet the headline rate is lower. On paper they can look close. In your bank account, they often won't.
That's where an IR35 calculator earns its place. It helps you turn a contract advert into something useful, an estimate of what you may keep after tax, National Insurance and, where relevant, umbrella deductions or company taxes. Used properly, it's one of the quickest ways to avoid comparing contracts on day rate alone.
At UmbrellaCompany.com, we see the same issue repeatedly. Contractors don't usually struggle with the phrase “inside IR35”. They struggle with the practical question: what will I receive each week or month? A calculator can answer that, but only if you understand what it is modelling, what it leaves out, and why two calculators can produce different results from the same rate.
Understanding Your Contract Pay with an IR35 Calculator
A contractor looking at two similar roles rarely needs more theory. They need clarity.
If one role is inside IR35 and the other is outside, the headline rate is only the starting point. The tax treatment changes the economics of the contract, so comparing one rate to another without modelling the deductions can lead to a poor decision.
A good IR35 calculator gives you a fast working estimate of the difference between those two worlds. It helps you test the practical questions that matter:
- Net pay reality: What lands in your account under each arrangement.
- Rate negotiation: Whether the inside-IR35 role needs a higher day rate to be worthwhile.
- Career trade-offs: Whether flexibility, contract length, remote working, or certainty offset a lower take-home figure.
- Planning ahead: What your monthly cash flow may look like once deductions are applied.
That last point matters more than many contractors expect. A role can be professionally attractive and still fail the basic affordability test once umbrella deductions and PAYE are applied.
If you're also widening your search, practical job-search material can help at the same time as pay modelling. For example, these UK remote work application tips are useful if you're comparing remote contract roles and want to improve the quality of the opportunities reaching your inbox.
Practical rule: Never assess an inside-IR35 contract by day rate alone. Assess it by realistic take-home pay.
For a quick first pass, we'd usually start with a take-home estimate and then pressure-test the assumptions behind it. Tools like the UK take-home pay calculator can help you turn a rate into a more meaningful number before you commit to interviews, negotiations, or a new umbrella arrangement.
What Is an IR35 Calculator and What Does It Do
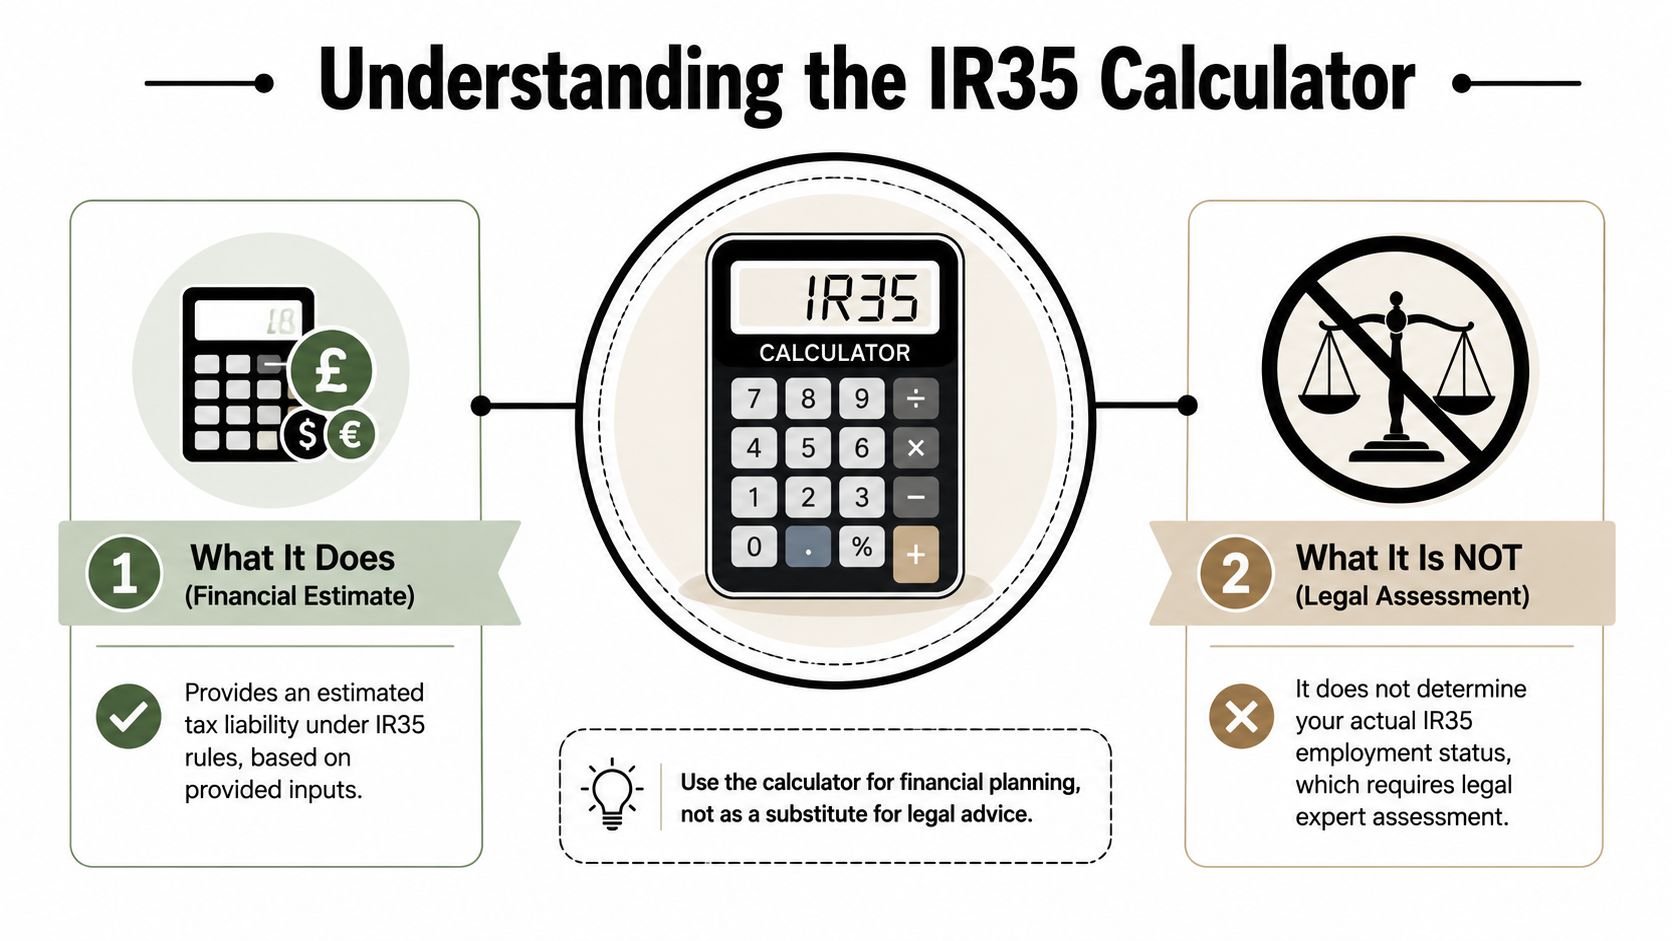
An IR35 calculator is not a status tool.
It doesn't decide whether your contract is inside or outside IR35. That is a separate status assessment based on the working arrangement, contractual terms, and how the engagement operates in practice. A calculator does something narrower and more useful for day-to-day planning. It models the likely financial outcome once a status assumption has already been made.
The calculator is a forecasting tool
In practical terms, an IR35 calculator is a payroll-modelling tool. It compares take-home pay under inside-IR35 and outside-IR35 assumptions by combining contract revenue, Income Tax, employee and employer National Insurance, corporation tax, and dividend tax rules. One UK-focused calculator also models 2026/27 inputs and shows that outside-IR35 estimates depend on deducting business expenses, then applying corporation tax at 19% up to £50,000 of profit and 25% above that, before extracting value through salary plus dividends, as outlined by Tax Calculate's IR35 tax calculator.
That distinction matters because many contractors click into a calculator expecting a legal answer. What they're really getting is a financial estimate based on whichever status they select.
Two different financial models
A solid calculator usually models one of two routes:
| Scenario | What the calculator is trying to simulate |
|---|---|
| Inside IR35 | Income treated broadly like employment income, often through payroll or an umbrella arrangement |
| Outside IR35 | Income received by a limited company, with business expenses, company taxation, salary, and dividends considered |
That's why the same day rate can produce sharply different outputs. The tool isn't being inconsistent. It's applying two different tax treatments to the same contract income.
A useful IR35 calculator answers, “What does this contract look like financially if the status is inside or outside?”, not “What is my status?”
If you want to compare those two routes side by side, the inside vs outside IR35 calculator is the type of tool to use. It's most valuable when you already know, or strongly suspect, how the role will be classified and now need to judge whether the rate still works for you.
How an IR35 Calculator Works and Its Key Inputs
The output is only as good as the inputs.
Many contractors rush straight to the result, but the stronger approach is to understand what the calculator is asking and why. If you leave important fields blank, you'll still get a number. It just may not be a number you should rely on.
The main inputs that shape the result
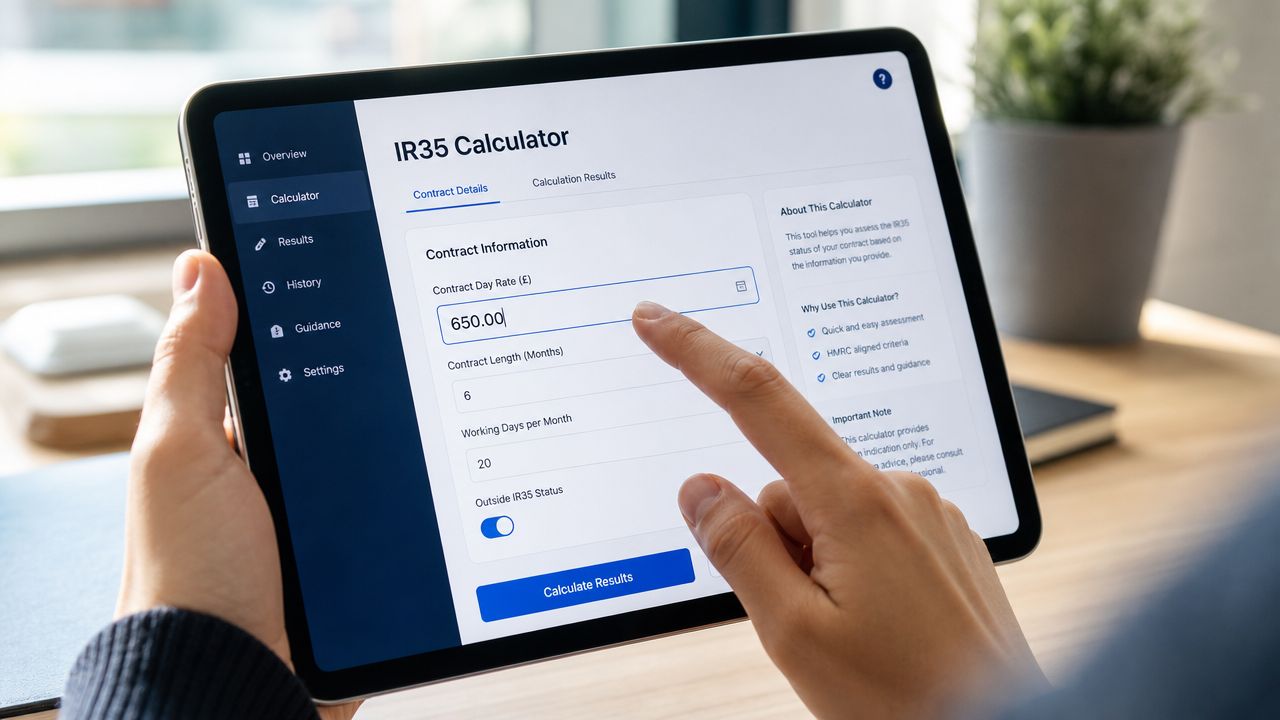
Most IR35 calculators ask for a familiar set of details. The exact labels vary, but the core inputs tend to be similar.
- Contract rate: Usually a day rate, sometimes hourly. This is the headline figure everyone notices first.
- Working pattern: Days per week or contract length. A rate on its own doesn't tell the calculator how much revenue to model.
- Tax assumptions: Tax code or standard assumptions where the tool allows it.
- Pension choices: Particularly relevant for umbrella calculations, because pension deductions can alter take-home pay.
- Expenses and company assumptions: More relevant for outside-IR35 modelling through a limited company.
- Umbrella-related inputs: Fees and other deductions where the calculator is detailed enough to include them.
If you need a refresher on the difference between gross and net figures while entering your data, this Fintrack guide on annual income is a helpful reference point.
Why modern calculators ask more than rate and days
The UK's IR35 framework changed materially in April 2021, when the off-payroll working rules were extended from the public sector to the private sector. Under the original rules for small-company engagements, a contractor's company could claim a 5% allowance for business expenses, but that allowance is not available under the off-payroll rules for larger clients after the April 2021 reform, as explained by IT Contracting's IR35 calculator guide.
That's one reason modern calculators often show a much bigger gap between inside and outside outcomes than contractors expect. The assumptions changed, and the calculators had to change with them.
What happens in each model
The mechanics differ depending on the scenario selected.
For inside IR35, the calculator generally models deductions in a payroll-style environment. For outside IR35, it models company income first and personal extraction second.
Inside IR35 route
- The contract income is treated in a way that reflects PAYE-style deductions.
- The calculation focuses on what remains after payroll costs and tax treatment have been applied.
- If the engagement runs through an umbrella, extra inputs become important.
Outside IR35 route
- The calculator starts from company revenue.
- It then reflects business expenses and company taxation.
- Finally, it estimates what you may draw personally through a salary-and-dividend approach.
Entering only your day rate gives you a rough answer. Entering your actual working pattern, pension position, and payment route gives you something you can use.
If you're trying to make sense of the payroll side before using any calculator, a simple grounding in how PAYE works makes the result easier to interpret.
Example Scenarios Inside and Outside IR35
The fastest way to understand an IR35 calculator is to treat it like a decision tool, not a tax lecture.
Suppose you're offered a contract at £500 per day. The obvious question is whether that rate is still attractive once it is modelled as inside IR35 through an umbrella, and how it compares with the same headline rate outside IR35 through a limited company.
We need to be careful here. Without a full set of personal assumptions, no article can give you a precise net figure that will fit your circumstances. That's exactly why calculators exist. But we can still show how the comparison should be approached and which deductions belong in each route.
A side-by-side comparison framework
Take-Home Pay Comparison: Inside vs Outside IR35 (£500/day)
| Metric | Inside IR35 (via Umbrella) | Outside IR35 (via Ltd Co) |
|---|---|---|
| Starting point | Contract income paid into an umbrella-style payroll model | Contract income received by your limited company |
| Main tax treatment | PAYE-style treatment on income | Company taxation first, then personal extraction |
| Key deductions to expect | Income Tax, employee NICs, employer-side costs, umbrella-related deductions where applicable | Business expenses, corporation tax, then salary and dividend tax treatment |
| Pension impact | Can affect take-home if included by the calculator | Depends on how the company makes contributions and how the tool models them |
| What often gets missed | Employer-side deductions and umbrella details | The effect of expenses and extraction choices |
| Usefulness of the result | Helps test whether the offered inside rate is commercially viable | Helps judge whether the limited-company route preserves enough of the rate |
Benchmarks become particularly useful. A practical guide used by UK IR35 tools is that an inside-IR35 day rate often needs to be about 20% to 30% higher than an outside-IR35 rate to produce the same net income. The same source notes that a contractor on a £250 daily rate working inside IR35 through an umbrella company can typically expect to take home 60% to 70% of gross earnings after deductions, according to Employers Calculator's IR35 calculator.
That benchmark doesn't replace a personalised calculation. It does explain why contractors regularly underestimate how much higher an inside rate needs to be before it feels equivalent.
How to use this in a real negotiation
If you're comparing a genuine outside-IR35 role against an inside-IR35 alternative, the practical workflow looks more like this:
- Model the outside role first: Treat it as your economic baseline.
- Test the inside role at the offered rate: Don't assume the higher gross figure solves the problem.
- Adjust for realism: Include pension choices, fees, and any umbrella-specific deductions where possible.
- Decide commercially: If the inside role still works after a realistic calculation, you can negotiate from a position of clarity.
Contractors often focus on whether an inside rate is “high”. The better question is whether it is high enough.
If you're weighing contract offers and need a broader explanation of the classification itself, this guide on inside or outside IR35 is useful alongside the calculator output.
Common Caveats and Why Different Calculators Give Different Results
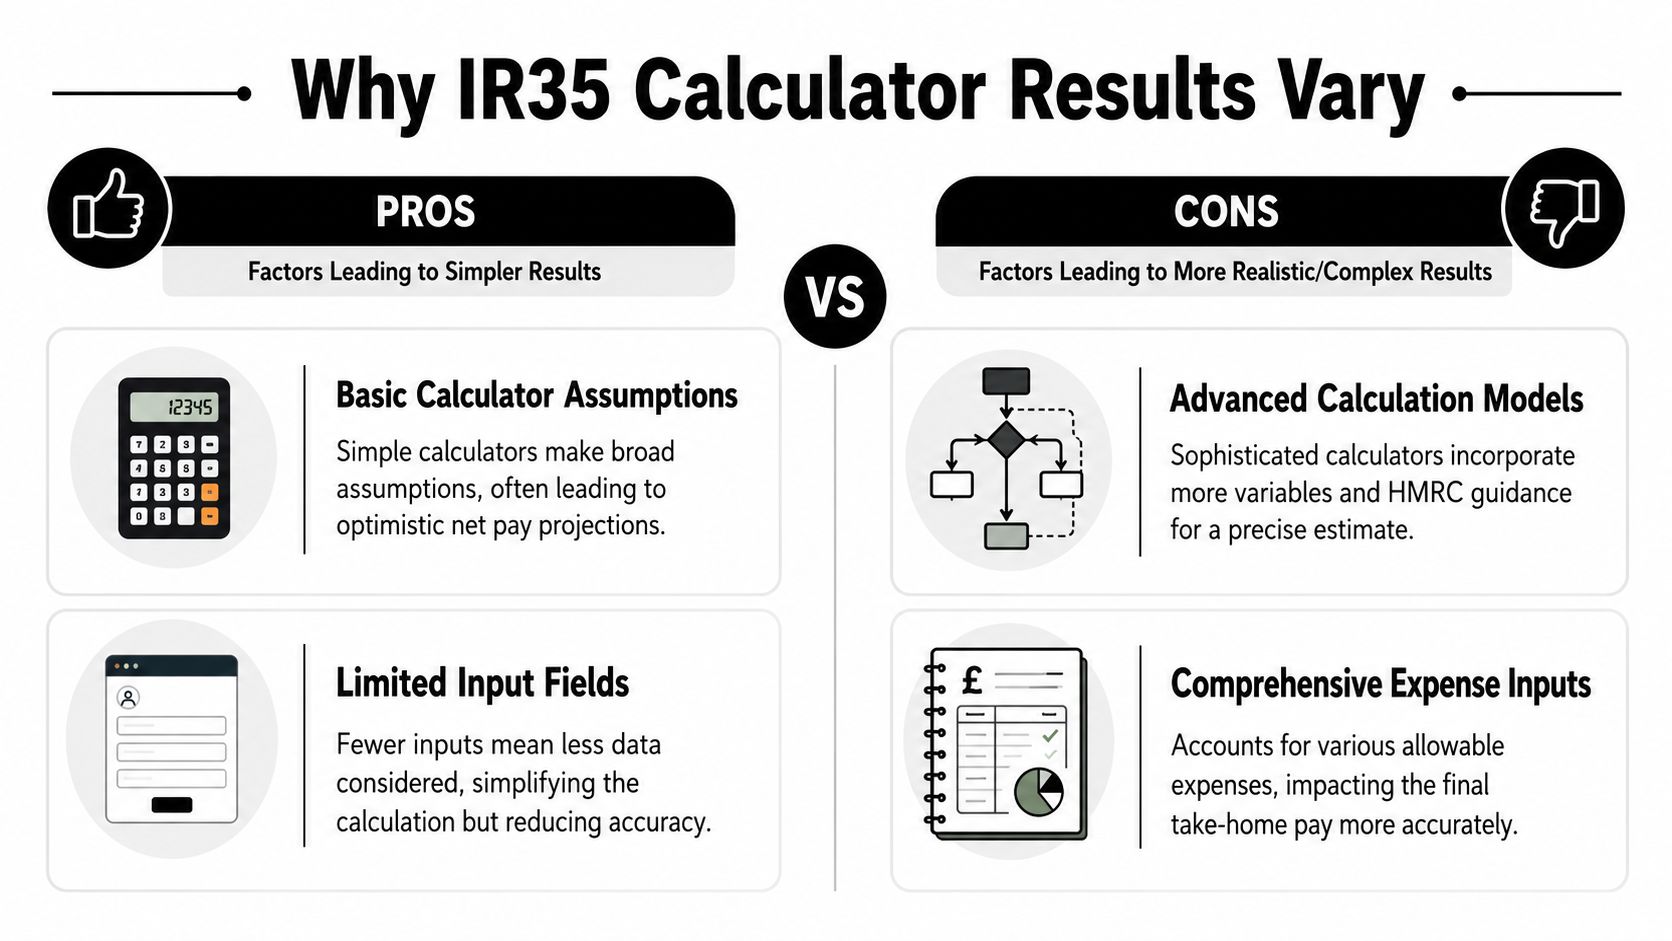
Two IR35 calculators can take the same contract rate and give you different take-home figures.
That isn't always because one is wrong. Often, one is more complete than the other.
The biggest reason simple tools mislead
Most free calculators aim for speed. They ask for a rate, perhaps a few working assumptions, and then produce a neat headline answer. That's convenient, but it can create false confidence.
More accurate inside-IR35 calculations need to account for more than PAYE and employee National Insurance. According to PayStream's inside IR35 contractor calculator guidance, simple IR35 calculators can be misleading because they ignore deductions such as umbrella company fees, the Apprenticeship Levy, and statutory pension contributions. Those employer-side costs directly affect final take-home pay.
That's the key gap in many online tools. They show a clean estimate, but not always a realistic one.
What usually changes the result
The differences usually come from assumptions hidden behind the result.
- Umbrella margin: One calculator may include it, another may assume none, and a third may leave it for you to enter.
- Employer-side deductions: Some tools model them properly. Some gloss over them.
- Pension treatment: Whether you are opted in, opted out, or contributing at a particular level can alter the net figure.
- Expense handling: Especially relevant where a calculator asks about allowable costs or work-related treatment.
- Default assumptions: Tax code, work pattern, and payment timing can all move the estimate.
What to check before trusting the output
When we review calculator outputs, these are the questions worth asking:
Does it explain the deductions?
If the result appears as a single net figure with no breakdown, treat it as directional only.Does it model umbrella-specific costs?
That matters for inside-IR35 roles far more than many first-time umbrella users realise.Can you alter pension assumptions?
If not, the estimate may not reflect your actual payslip.Does it show employer-side impact clearly?
If those costs are hidden, the tool may overstate take-home pay.
The quickest calculator isn't always the most useful one. The best one is the one that mirrors how you'll actually be paid.
This applies beyond contractor tax modelling. Any personal finance tool can look sharper than it is if it strips out real-world variables. The same issue appears in consumer budgeting and mortgage planning, which is why tools that model the detail tend to be more useful than headline-only estimates, such as those designed to help you pay off your home faster.
Your Next Steps After Using a Calculator
A calculator result is only useful if it changes the decision you make on the contract.
At this stage, the job is to turn an estimate into a rate decision, a negotiation point, or a clear no. That matters because many free IR35 calculators still miss costs that show up on the payslip, especially under an umbrella. Employer's NI, the umbrella margin, and pension contributions can turn a contract that looks acceptable on screen into one that feels poor in practice.
Start by pressure-testing the number against the contract terms and the payment route you will use.
- Check status separately from pay modelling: A calculator can estimate net pay, but it does not determine IR35 status.
- Rework the assumptions using real figures: Use the quoted day rate, expected days worked, umbrella margin, pension choice, and any student loan or other deductions that apply to you.
- Test whether the rate still works after hidden costs: For inside-IR35 contracts, this is usually the point where unrealistic calculator outputs get exposed.
- Decide what you need to do next: Accept the rate, negotiate a higher one, or walk away before investing more time in the role.
- Get advice if your position is not straightforward: Existing company income, dividend planning, retained profits, or more than one contract can change the picture.
One practical habit helps here. Compare the calculator output with a sample payslip or a detailed umbrella illustration before agreeing terms. If the two numbers are far apart, the calculator probably relied on assumptions that do not match how you will be paid.
For contractors heading into an inside-IR35 assignment, comparing umbrella providers is usually the next sensible step. The differences are rarely dramatic in headline marketing, but small variations in margin, pension setup, and payroll handling can still affect your monthly net pay and the quality of the service you receive.
The aim is simple. Use the calculator to set expectations, then verify the detail before you sign anything.
A contract can still fail the commercial test after a proper review. The opposite is also true. Some roles look marginal on the advertised rate, then become workable once you model the deductions properly and negotiate from the net figure rather than the gross day rate.


