


When you start out as a contractor in the UK, your first big decision is how to structure your business. It really boils down to two main paths: setting up your own limited company or working through an umbrella company.
Going the limited company route often means you will take home more pay, thanks to some smart, tax-efficient ways of drawing your income. On the other hand, an umbrella company is the simpler, low-hassle option; we handle all the tax and National Insurance for you.
Choosing Your Path: Limited Company vs Umbrella Company
This initial choice is a fundamental one for any UK contractor. It is the decision that will shape everything from your tax bill and admin workload to, most importantly, how much money you actually get to keep. Getting to grips with the real-world differences between an umbrella company and your own limited company is the first step to building a contracting career that is both profitable and sustainable.
The Umbrella Company Route: A Simple Start
For a lot of people, especially those just dipping their toes into contracting or taking on shorter gigs, an umbrella company is the most straightforward way to go. Here at UmbrellaCompany.com, we see it as a completely hassle-free entry point into the contracting world.
Think of an umbrella company as your employer, but just for tax purposes. We take care of all your PAYE (Pay As You Earn) tax and National Insurance contributions straight from your earnings. You get a payslip, just like you would in a permanent job. This model is a perfect fit for contracts that fall inside IR35, as the tax advantages of a limited company are mostly wiped out in those cases.
So, what are the main perks?
- Minimal Admin: Forget about company accounts, Corporation Tax, or VAT returns. The umbrella company handles it.
- Employment Rights: You actually get access to statutory rights like sick pay and holiday pay.
- Simplicity: It is an easy system to manage, freeing you up to focus on what you do best: your client work.
The Limited Company Route: Greater Control and Efficiency
Running your business through your own limited company, often called a Personal Service Company (PSC), gives you far more financial control and the potential for a higher take-home pay. As the director of your own company, you can structure your income in the most tax-efficient way possible.
Typically, this means paying yourself a small, tax-friendly salary and then taking the rest of your company’s profits as dividends. Why? Because dividends are taxed at a much lower rate than salary income, which is precisely why this structure can be so much better for your bank balance.
This image breaks down the three core parts of structuring your income through a limited company.
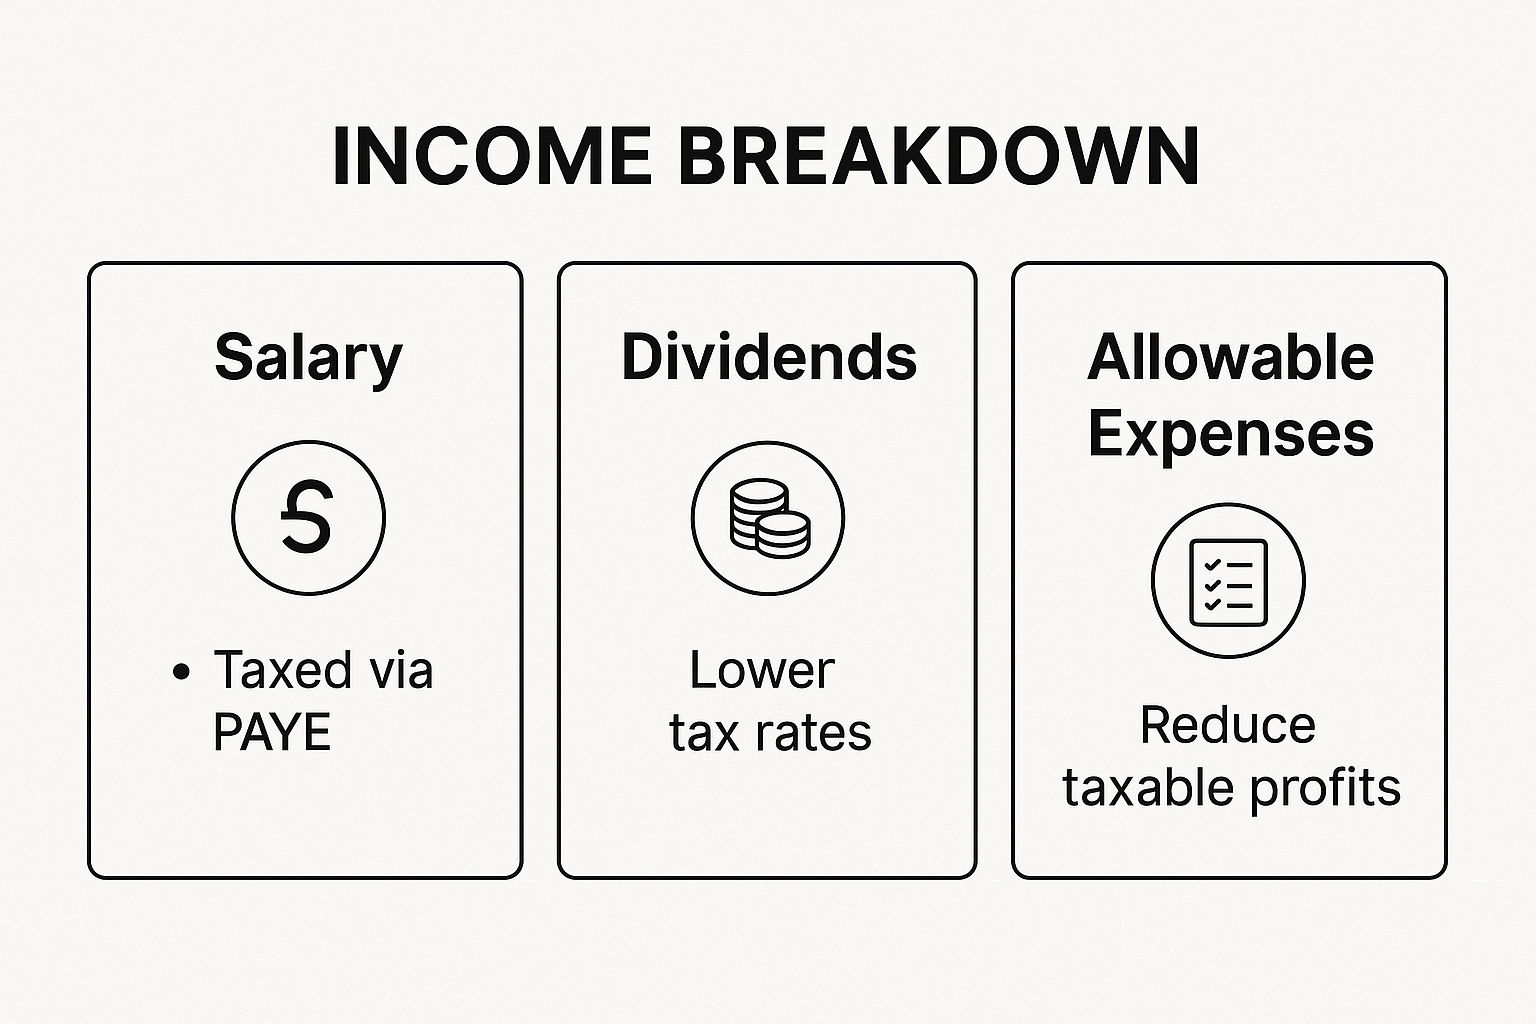
You can see how blending a PAYE salary with lower-taxed dividends and claiming all your allowable business expenses works in harmony to bring down your overall tax liability.
Of course, this extra financial control comes with a bit more responsibility. You are now legally accountable for your company’s finances and making sure you are square with the taxman. This path is usually the best fit for long-term contractors working on projects outside IR35, who are happy to manage the admin or are ready to bring an accountant on board to help out.
When you're a company director, you're not just a contractor anymore, you're a business owner. That means you have to step up and embrace the legal duties that come with it, from filing your annual accounts with Companies House to making sure you're fully compliant with all of HMRC's rules.
Umbrella vs Limited Company: A Head-to-Head Comparison
To help you decide which path is right for your contracting career in the UK, we've put together a simple, side-by-side summary of the key differences.
| Feature | Umbrella Company | Limited Company |
|---|---|---|
| Take-Home Pay | Generally lower due to PAYE deductions on all income. | Potentially higher through a tax-efficient mix of salary and dividends. |
| Admin & Paperwork | Very low. The umbrella company handles almost everything. | High. You are responsible for accounts, tax returns, and compliance. |
| Legal Responsibility | Minimal. You are an employee of the umbrella company. | Full responsibility as a company director for all legal and financial matters. |
| IR35 Suitability | Ideal for contracts that are inside IR35. | Best suited for contracts that are firmly outside IR35. |
| Control & Flexibility | Limited. You operate under the umbrella's structure. | Complete control over your business finances and structure. |
| Costs | A weekly or monthly margin is deducted from your earnings. | Accountant fees, software costs, and other business running costs. |
| Benefits | Access to statutory employment rights (sick pay, holiday pay). | No automatic employment rights, but you can set up your own benefits. |
Ultimately, the choice comes down to your personal circumstances. Are you looking for simplicity and peace of mind, or are you after maximum financial control and prepared to handle the extra admin that comes with it? Your answer will point you in the right direction.
Optimising Your Income as a Limited Company Director
If you've decided the limited company route is for you, the next challenge is structuring your income to be as tax-efficient as possible. For most UK contractors working outside IR35, this comes down to a tried-and-tested strategy: paying yourself a small salary and taking the rest of your earnings as dividends.
This is not just a popular approach; it is a smart way to manage your finances, and it all hinges on how salaries and dividends are taxed.
A salary is a straightforward business expense, which means it reduces your company's profit and, therefore, its Corporation Tax bill. The catch? It attracts both employee's and employer's National Insurance Contributions (NICs), which can take a real bite out of your earnings.
Dividends, on the other hand, are paid from post-tax profits and are completely free of National Insurance. That single difference is why the low-salary, high-dividend model is so effective at boosting what you actually take home.
Finding the Director's Salary Sweet Spot
Setting your director's salary is not a random guess. It is a strategic decision. You are looking for that 'sweet spot' that unlocks key benefits while keeping tax and National Insurance as low as legally possible.
Most contractors aim for a salary high enough to count as a qualifying year for state benefits but low enough to avoid paying much (or any) tax or NI.
Here is a quick look at the key thresholds:
- Lower Earnings Limit (LEL): Paying yourself above this level (£6,396 for the 2024/25 tax year) ensures you are building up qualifying years for your State Pension. This is a non-negotiable for long-term planning.
- Primary Threshold: This is the point where you start paying employee's NI contributions. For 2024/25, it is £12,570.
- Secondary Threshold: This is when your company starts paying employer's NI. For 2024/25, it is £9,100.
By setting a salary between the LEL and the Secondary Threshold, you hit the ideal balance. You get the credit for your State Pension, but neither you nor your company has to pay any National Insurance. For most sole directors, a salary around £9,100 per year is a common and highly efficient starting point.
Beyond Salary and Dividends
While the salary and dividend mix is the foundation, it is not the only tool in your box. Two other powerful strategies can further trim your company's tax bill and leave more money on the table for you.
Making Pension Contributions
One of the most effective tax-planning moves you can make is to pay into your pension directly from your business account. These contributions are typically an allowable business expense, reducing your company's profit and, as a result, its Corporation Tax liability.
Making significant pension contributions directly from your business can dramatically reduce your annual Corporation Tax bill. It is a win-win: you are saving for your future retirement while simultaneously lowering your immediate tax burden.
Think about it: if your company makes a £10,000 pension contribution, that is £10,000 less profit for HMRC to tax. This is almost always more efficient than paying into a pension from your personal, post-tax income.
Claiming All Legitimate Expenses
As a director, you can claim a wide range of business expenses. Every single legitimate expense you claim reduces your company’s taxable profit, pound for pound. This directly lowers your Corporation Tax bill, leaving more profit available to be paid out as dividends.
Common allowable expenses include:
- Accountancy fees and business insurance.
- Office costs, like stationery, phone bills, and software.
- Travel and subsistence costs when working away from your usual place of work.
- Relevant professional training courses.
Keeping meticulous records and claiming everything you are entitled to is not just good admin; it is a core part of a tax-efficient income strategy. For a deeper dive, our guide offers more detailed advice on how to maximise take-home pay as a contractor.
By combining an efficient salary, strategic dividends, business pension contributions, and diligent expense claims, you build a truly robust financial structure. This layered approach ensures you are not just earning well, you are keeping as much of that income as you legally can.
Right, so you have set up your limited company. This gives you incredible control over your finances, but it also means you have taken on some serious legal duties as a director. Getting your head around your tax obligations is not just a box-ticking exercise; it is the bedrock of structuring your income properly as a UK contractor.
Get this part right, and you will stay on the right side of HMRC, dodge any nasty financial surprises, and be able to plan your future with confidence.
Remember, your company is its own legal entity. That means its profits are hit with a few different taxes. The big ones you will be juggling are Corporation Tax, VAT (if you need to register), and PAYE on any salaries you pay out, including your own. On top of that, you will have your own personal tax bill for any dividends you take from the business.
Key Taxes for Your Limited Company
At first glance, the different taxes can feel a bit overwhelming. But it helps to think of them as separate pieces of the same puzzle, each one slotting together to build your company's complete financial picture.
Here is a quick rundown of what you are dealing with:
- Corporation Tax: This is the tax your company pays on its annual profits. You have to file a Company Tax Return and settle this bill within nine months and one day of your company's year-end. No excuses.
- VAT (Value Added Tax): If your company's turnover tips over the VAT threshold (currently £90,000), VAT registration becomes mandatory. You will start adding VAT to your invoices and then paying that collected tax over to HMRC, usually every quarter.
- PAYE (Pay As You Earn): This is the system HMRC uses to collect Income Tax and National Insurance from salaries. As you will be paying yourself a director's salary, your company will need to run a PAYE scheme.
- Income Tax on Dividends: This is a personal tax. The dividends you draw from company profits are taxed, and you declare and pay this through your annual Self Assessment tax return.
For a deeper dive into making your setup as efficient as possible, you should check out our guide on how to pay less income tax as a limited company.
The Impact of Regulatory Changes
Tax rules are never set in stone. They shift and change, sometimes subtly, sometimes significantly. Staying on top of these updates is absolutely critical for smart financial planning. Just look at the recent changes to National Insurance contributions; they have had a direct impact on what the 'optimal' director's salary looks like.
For instance, tweaks to the secondary threshold for National Insurance can completely change your take-home pay calculations. That is why it is so important to keep your finger on the pulse of government announcements.
My best advice? Pay very close attention to the annual Budget. Even small adjustments to tax-free allowances, NI thresholds, or Corporation Tax rates can have a surprisingly large knock-on effect on your bottom line for the year ahead.
Balancing Salary, NI, and Your State Pension
While cutting your tax bill is always a nice goal, it should not be your only focus. It is tempting to pay yourself a tiny salary to avoid tax and NI, but this can come back to bite you. If your salary is too low, you might not be making enough National Insurance contributions to build up qualifying years for your State Pension.
This is where the balancing act comes in. For most contractors, the smartest play is to pay a salary that is just above the Lower Earnings Limit. This ensures you get that all-important qualifying year for your State Pension.
Yes, it might mean your company pays a small amount of National Insurance, but think of it as a worthwhile investment in your long-term financial security. It is a modest cost for a significant future benefit.
Ultimately, managing your tax obligations is not just about being compliant. It is about being strategic. It is about planning your salary and dividends intelligently, keeping an eye on the shifting rules, and making savvy decisions that benefit you both today and well into retirement.
How IR35 Rules Can Reshape Your Income Structure
Anyone contracting in the UK has heard of IR35. Also known as the off-payroll working rules, it is a piece of tax legislation you simply cannot ignore. Its entire purpose is to figure out if you are a genuine business or, in the eyes of HMRC, a ‘disguised employee’ working for your client.
Getting this determination right is critical. It can completely change how you structure your income, hitting everything from your take-home pay to your tax bill.
At its heart, IR35 draws a line in the sand. If your contract is deemed ‘outside IR35’, you are operating as a proper business. This is the sweet spot for most limited company contractors, allowing you to pay yourself tax-efficiently through a mix of a small salary and dividends.
But if your contract is found to be ‘inside IR35’, things look very different. HMRC sees you as an employee for tax purposes, wiping out the main tax advantages of running your own company. Your entire income from that specific contract gets taxed at source through PAYE, just as if you were on the client's payroll.
Who Makes the IR35 Decision?
In the past, the burden of deciding your IR35 status fell on you. Not anymore. For the vast majority of contracts, the responsibility now lies with your end client.
If your client is a medium or large private sector business, or any public sector organisation, they are legally required to assess your engagement. They must then issue a Status Determination Statement (SDS), which officially declares whether your contract is inside or outside IR35.
If it is an inside determination, the 'fee-payer' (usually the recruitment agency or the client) is responsible for deducting Income Tax and National Insurance Contributions before your company even sees the money.
The rule changes in 2017 for the public sector and 2021 for the private sector were a massive shift. Placing the compliance burden on the client forced many contractors to completely rethink their setup and how they get paid.
Operating Inside vs. Outside IR35
So, what does this actually mean for your bank account?
If you are working inside IR35 through your limited company, your invoicing fundamentally changes. Instead of your full day rate hitting your business account, you will receive a 'deemed payment' after tax and NI have already been taken off. This drastically cuts the funds available for you to draw as dividends.
This is exactly why many contractors find it much simpler and safer to use an umbrella company for inside-IR35 roles. It removes the administrative headache and ensures you are fully compliant. At UmbrellaCompany.com, we help contractors make this switch seamlessly.
On the other hand, if you have secured an outside-IR35 contract, your work is not done. You must ensure your day-to-day working practices genuinely reflect your status as an independent business. This means demonstrating control over your work, showing you bear financial risk, and having a right of substitution.
To stay on the right side of HMRC, you need to understand the nuances. We cover this in much more detail in our guide explaining what IR35 is and how to navigate it properly.
Ultimately, getting to grips with your IR35 status is non-negotiable. It dictates the most compliant and financially sensible way to structure your income for every single contract you take on.
Mastering Your Cash Flow and Planning for the Future
Structuring your contractor income smartly is about more than just tax planning. It is the foundation for building real financial stability and hitting those big life goals, whether that is buying a home or setting yourself up for a comfortable retirement.
As any contractor knows, income can be a bit of a rollercoaster. That makes solid cash flow management an absolutely essential skill. Get this right, and you can ride out the quiet spells between contracts without the stress, making your contracting career both sustainable and rewarding.
Building Your Financial Foundations
The first practical step is to treat your finances like a pro. That starts with using a dedicated business bank account properly. All your client payments go in, and all your business expenses come out. Simple.
This clean separation creates a clear audit trail for HMRC and makes life much easier for you or your accountant when it is time for year-end accounts. It also gives you a real-time, no-nonsense view of your business's financial health.
A dedicated business bank account is your single source of truth. It simplifies bookkeeping, clarifies your tax position, and stops personal and business finances from becoming a tangled, stressful mess.
Next, you need to get into the habit of ringfencing money for tax as soon as it hits your account. Do not wait for the bill to land. A good rule of thumb is to shuttle around 20-25% of every invoice payment into a separate savings account. This way, you have always got the funds ready for your Corporation Tax, VAT, and personal tax bills.
Forecasting for Financial Security
You cannot predict the future, but you can definitely forecast your income and expenses. A simple spreadsheet is all you need to map out your expected earnings for the next three to six months based on your current contract and any likely extensions.
Alongside your income, list all your regular outgoings:
- Fixed Costs: Things like your accountancy fees, business insurance, and software subscriptions.
- Variable Costs: Travel, training, new equipment (the stuff that changes month to month).
- Tax Provisions: The money you are siphoning off into that separate tax pot.
This little exercise gives you a clear picture of your financial runway. It helps you spot potential cash flow gaps long before they become a problem, allowing you to make informed decisions. Can you afford that holiday? Or do you need to start lining up the next contract sooner rather than later?
Setting Your Day Rate Strategically
A huge part of structuring your income is making sure you are earning the right amount in the first place. Setting a competitive day rate is not just about what you need; it is about what the market will bear. What are other contractors with your skills and experience charging?
Knowing the average earnings in sectors like IT or construction helps you benchmark your own rates. For example, recent wage growth trends show that in January 2025, the average weekly salary and bonuses for UK construction workers hit £792. Having these figures in your back pocket helps you forecast your potential gross income and ensures your rates are aligned with the market.
Planning for the Long Term
With your day-to-day cash flow under control, you can start thinking about the bigger picture. This means creating a solid financial safety net and planning for those major life goals.
Building a 'Rainy Day' Fund
Every single contractor needs a contingency fund. This is a pot of money, completely separate from your tax savings, designed to cover your essential living and business costs when you're between contracts. A good target is to build a fund that can see you through for at least three to six months.
Protecting Your Income
As a contractor, you do not have the safety net of sick pay or redundancy. To protect yourself, it is wise to look into options like Income Protection and Redundancy Cover. These policies can provide a vital financial cushion if you are unable to work due to illness or find yourself on the bench for longer than expected.
By mastering these cash flow principles and planning ahead, you can turn a variable income into a powerful tool for building a secure and prosperous future.
Common Questions on Contractor Income Structures
Getting your head around contractor finances can feel like a minefield. Whether you are running a limited company or using an umbrella, a few key questions always seem to pop up. Getting them right can make a huge difference to your confidence, and your take-home pay.
Let’s tackle some of the most common queries we hear from UK contractors, with clear, straightforward answers.
What Is the Most Tax-Efficient Salary for a Limited Company Director?
Finding the ‘sweet spot’ for a director’s salary is a real balancing act. You are essentially trying to hit a target that is high enough to qualify for state benefits but low enough to minimise tax and National Insurance (NI) payments.
For most contractors, that means setting a salary at or near the Secondary Threshold for NI. This is the point where your company does not have to pay any employer's NI on your salary. At the same time, it is often structured so you pay little to no employee’s NI or income tax yourself.
Crucially, though, your salary must be above the Lower Earnings Limit. This ensures the tax year counts towards your State Pension entitlement, something that is easy to overlook but vital for your future. These thresholds change every tax year, so it is always worth checking the latest rates and getting a quick bit of advice from your accountant to make sure your setup is still optimal.
A smart director's salary isn't just about saving tax today. It's a strategic move that shores up your long-term financial security by protecting your State Pension.
Can I Claim Expenses Through an Umbrella Company?
Claiming expenses through an umbrella company has become much tighter in recent years. The game-changer was a set of rules around Supervision, Direction, or Control (SDC).
If your client has SDC over how you work (which is the case for most contractors), you generally cannot claim tax relief on things like your daily commute or lunch. HMRC sees these as ordinary travel and subsistence costs, just like a permanent employee would have.
However, that does not mean all expenses are off the table. You can often still claim for other genuine business costs, such as:
- Professional subscriptions to bodies relevant to your industry.
- Specific training courses you need to complete for your role.
- Essential equipment you have to buy out of your own pocket to do the job.
The key is to always check the policy of the umbrella company you are working with. A compliant provider will be completely transparent about what you can and cannot claim.
How Do Dividends Work and When Should I Take Them?
Dividends are simply a way for a company to share its profits with its shareholders. As the director and (usually) sole shareholder of your limited company, you can pay yourself dividends from whatever profit is left after you have paid Corporation Tax.
But you cannot just move the money across. To do it properly, you need to declare the dividend formally. This means holding a board meeting (even if you are the only one there!), creating minutes, and issuing a dividend voucher for your records. This paper trail is absolutely essential; it is your proof to HMRC that the payment is a legitimate dividend, not just a salary in disguise.
As for timing, it is entirely up to you, but it is wise to only draw dividends when you are sure your company is profitable. Many contractors do this quarterly or annually. Do not forget, every shareholder gets a tax-free Dividend Allowance each year. Anything you take above that is taxed at different rates depending on your income tax band. A smart blend of a small salary and regular dividends is the cornerstone of running a tax-efficient limited company.
At UmbrellaCompany.com, we specialise in helping contractors find the perfect compliant umbrella company for their needs. Our comparison tool makes it simple to make an informed choice. Get started.


