


Ever stared at your payslip, completely baffled by how your hefty gross pay shrinks to that final figure? You’re not alone. The whole process, known as PAYE (Pay As You Earn), is actually quite straightforward once you get the hang of it.
This guide will explain exactly how PAYE is calculated. You will learn about the key components like your Personal Allowance and tax code, see a step-by-step calculation, and understand how it all applies to you as a contractor.
Essentially, HMRC figures out your tax-free Personal Allowance, gives your earnings a tax code, and then takes off Income Tax and National Insurance from your gross pay before the money ever lands in your bank account.
Your First Look at How PAYE Is Calculated
Getting to grips with how PAYE is calculated is your first real step towards mastering your finances as a contractor. It is the system HMRC uses to collect what you owe directly from your earnings, which means you pay your dues bit by bit throughout the year. It’s a smart system, really, as it stops you from getting hit with a massive, terrifying tax bill at the end of the year.
The whole thing is designed to be pretty much automatic. Your employer, or your umbrella company if you're a contractor, uses HMRC's rules to work out exactly what to deduct. This process keeps the tax system ticking over for millions of people across the UK.
The Main Components of PAYE
To understand the calculation, you just need to know the key ingredients. Think of it like a recipe; each part plays a crucial role in the final dish.
- Gross Pay: This is the big number. It's your total earnings before anyone takes a penny.
- Tax Code: HMRC sends this code to your employer. It tells them how much of your income is tax-free. The standard one right now is 1257L.
- Personal Allowance: This is the amount you can earn each tax year without paying a single bit of Income Tax. For most people, it’s £12,570.
- Income Tax and National Insurance: These are the main deductions. Once your tax-free allowance is accounted for, these are taken from the rest of your pay.
The History and Purpose of PAYE
The PAYE system has been the backbone of UK tax for a long time. It was brought in on 6 April 1944 to help manage the huge workforce during the Second World War, replacing the old-fashioned method of paying tax in one or two giant, painful lump sums each year.
Today, it handles tax for over 30.5 million people, making life much simpler for both employees and employers. You can dive deeper into PAYE's background and how it works today.
Here at UmbrellaCompany.com, our job is to make all of this simple for contractors. We bring clarity and support, making sure you understand exactly where every penny of your hard-earned money goes. By breaking down the basics of Pay As You Earn, we put you back in control of your contract income.
The Building Blocks of Your Payslip
To get to grips with how PAYE is calculated, you first need to know the key terms that pop up on your payslip. Think of them as the basic ingredients in the recipe for your take-home pay. Once you understand what each part does, the whole calculation suddenly makes a lot more sense.
We believe in making payroll simple. This section will break down the core concepts, such as gross pay, Personal Allowance, tax codes, Income Tax, and National Insurance, without the confusing jargon.
Gross Pay: The Starting Point for All Calculations
Your gross pay is simply the total amount of money you've earned before a single penny is deducted. It's that top-line figure on your payslip, and it’s the foundation for everything that follows. For contractors using an umbrella company, this number comes from the assignment rate you agreed with your client, after all the employment costs are handled.
This amount covers your basic pay plus any extras like bonuses or overtime. It’s the full value of your work for that pay period, whether you're paid weekly or monthly.
Your Tax-Free Personal Allowance
Just about everyone working in the UK gets a Personal Allowance. This is the amount of income you can earn each year before you have to start paying Income Tax. For the current 2024/2025 tax year, the standard Personal Allowance is £12,570.
This tax-free buffer is a cornerstone of the PAYE system. It means the first chunk of your earnings is protected from tax, which lowers your overall bill. Just be aware that this allowance starts to shrink if your income goes over £100,000.
Your tax code is essentially an instruction from HMRC to your employer, telling them how much tax-free income you should receive in a pay period. Getting it right is crucial for accurate PAYE deductions.
Demystifying Your Tax Code
Your tax code is that little combination of numbers and a letter that HMRC sends to your employer. It’s a shorthand message that tells them how to apply your Personal Allowance. The most common one you'll see is 1257L.
Here's what that actually means:
- The numbers (1257) are just your tax-free Personal Allowance with the last digit removed. Stick a zero on the end, and you get the full amount: £12,570.
- The letter (L) tells your employer that you’re entitled to the standard Personal Allowance. You might see other letters if your circumstances are different, for instance if you have a second job or receive company benefits.
The Two Main Deductions: Income Tax and National Insurance
Once we know your taxable income (that’s your gross pay minus your Personal Allowance), two main deductions come into play. These are Income Tax and National Insurance Contributions (NICs).
Income Tax is what you pay on your earnings above your Personal Allowance. How much you pay depends on which tax band your income falls into. These rates have changed a lot over the years. Back in the 1970s, the top rate was a staggering 75%!
National Insurance Contributions (NICs) are what you pay to fund state benefits like the State Pension, Jobseeker's Allowance, and of course, the NHS. There are different "classes" of NI. As an employee, you'll pay Class 1 Employee's NICs.
Your employer also pays a separate contribution for you, known as Employer's NICs. This is a really important part of umbrella company payroll, as it's an employment cost that's covered by the assignment rate. You can find out more in our detailed guide on what employer National Insurance contributions are.
By understanding these core building blocks, you’re already well on your way to mastering your payslip and knowing exactly where your money goes.
A Practical Walkthrough of a PAYE Calculation
Right, let's pull back the curtain and see exactly how the numbers work. Forget the jargon for a moment; we're going to walk through a real-world calculation together, step-by-step. The goal is to make the maths behind your payslip crystal clear.
This whole process turns abstract tax rules into something you can actually follow.
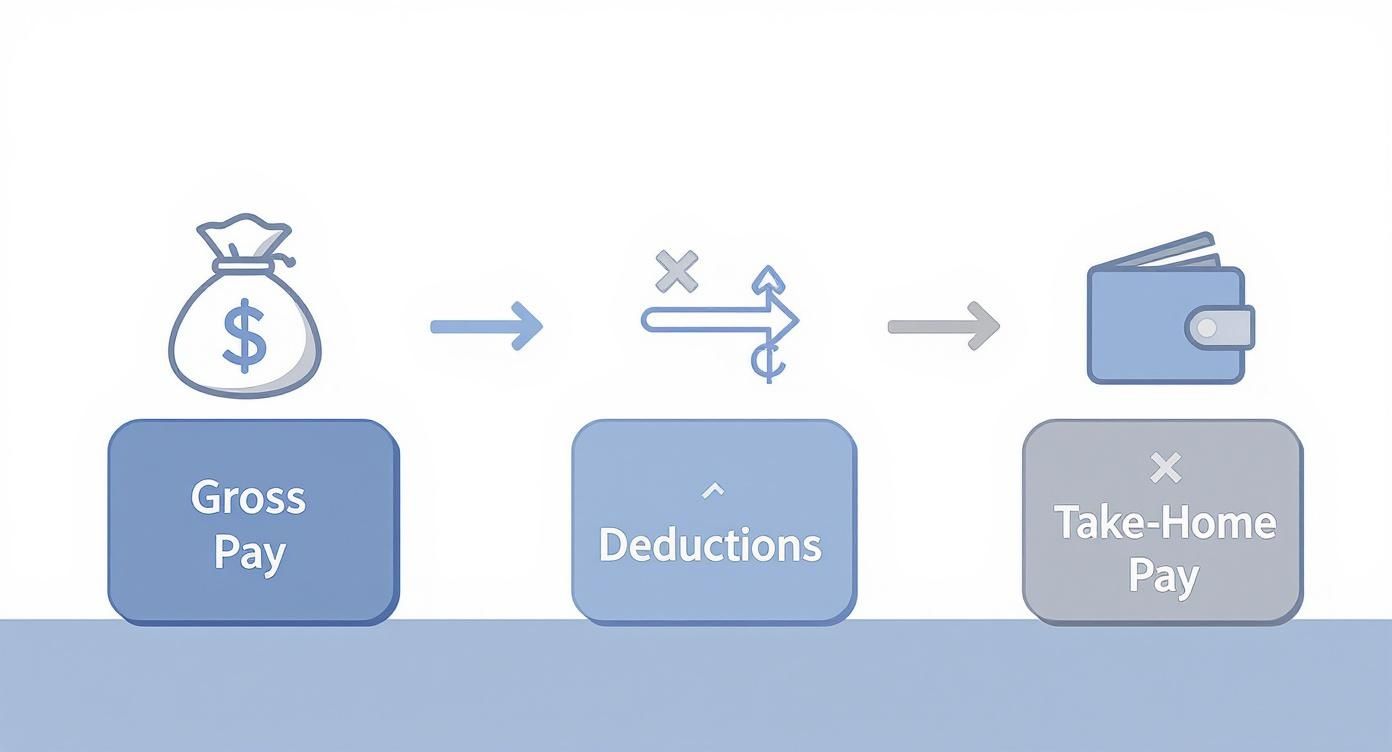
As you can see, it's a simple journey from what you earn to what you actually get. The deductions are the crucial bit in the middle.
Step 1: Work Out Your Taxable Income
First things first, we need to figure out how much of your pay is actually subject to tax. It’s not your total gross pay. Before HMRC takes a penny in Income Tax, you get to subtract your annual tax-free Personal Allowance.
For the 2024/2025 tax year, the standard Personal Allowance is £12,570. Think of this as the amount you can earn every year, completely tax-free.
Let’s put this into practice with an example. Imagine a contractor earns a solid £60,000 a year.
- Gross Annual Pay: £60,000
- Less Personal Allowance: – £12,570
- Total Taxable Income: = £47,430
This £47,430 is the magic number we'll use to work out the Income Tax. The PAYE system then cleverly chops this annual figure into monthly or weekly amounts, so the tax comes off each payslip correctly.
Step 2: Apply the Correct Income Tax Bands
Once we have our taxable income, we apply the different Income Tax bands. It’s a common myth that your entire income gets taxed at one single rate. It doesn't work like that.
Instead, your income is sliced up, and each slice gets taxed at a different percentage.
Here’s a quick breakdown of the UK Income Tax bands for England, Wales, and Northern Ireland.
UK Income Tax Bands and Rates (Excluding Scotland)
This table shows the taxable income bands and the corresponding tax rates for England, Wales, and Northern Ireland for the current tax year.
| Tax Band | Taxable Income | Tax Rate |
|---|---|---|
| Basic Rate | Up to £37,700 | 20% |
| Higher Rate | £37,701 to £125,140 | 40% |
| Additional Rate | Over £125,140 | 45% |
Let's stick with our contractor's taxable income of £47,430 and see how it fits into these bands.
- The first £37,700 of their taxable income falls into the Basic Rate band. So, that's £37,700 x 20% = £7,540.
- The rest of their income (£47,430 – £37,700 = £9,730) spills over into the Higher Rate band. This bit is taxed at 40%, which is £9,730 x 40% = £3,892.
Add them together, and the total annual Income Tax for this contractor comes to £7,540 + £3,892 = £11,432.
Step 3: Calculate Employee National Insurance Contributions
Next up is National Insurance. This is a totally separate deduction from Income Tax. Crucially, it is calculated on your gross earnings, not your taxable income, and it uses completely different thresholds.
From 6 April 2024, the main rate for Employee's Class 1 National Insurance is 8% on earnings between £12,570 and £50,270 per year. Anything you earn above that top threshold is taxed at 2%.
For our contractor on £60,000:
- Earnings up to £12,570: This portion is charged at 0%, so that's £0.
- Earnings between £12,570 and £50,270: The amount in this band is £37,700. We calculate 8% of this, which is £37,700 x 8% = £3,016.
- Earnings above £50,270: They have £9,730 left (£60,000 – £50,270). This bit is charged at 2%, which works out to £9,730 x 2% = £194.60.
So, their total annual Employee's NI contribution is £3,016 + £194.60 = £3,210.60.
Step 4: Factor in Employer National Insurance
Now for the final piece of the puzzle, especially for contractors using an umbrella company: Employer's National Insurance Contributions. This is a mandatory cost of employment that the umbrella company, as your official employer, has to pay to HMRC.
Employer's NI is a non-negotiable employment cost. It's worked out based on your gross earnings and taken from the assignment rate the end client pays, before your own gross pay is calculated.
The rate for Employer's NI is 13.8% on all earnings above the Secondary Threshold, which is £9,100 per year.
Back to our £60,000 earner one last time:
- First, we work out how much of their earnings are subject to Employer's NI: £60,000 – £9,100 = £50,900.
- Then we calculate the contribution: £50,900 x 13.8% = £7,024.20.
This amount, along with other employment costs like the Apprenticeship Levy and the umbrella's margin, is deducted from the funds received from your client. What's left over becomes your gross pay for tax purposes. By breaking it down like this, you can see precisely where every penny goes.
How Your Pay is Actually Calculated as a Contractor
When you're a contractor working through an umbrella company, seeing how the theory of PAYE translates to your actual payslip is crucial. Let's move beyond the general rules and walk through some real-world examples to show you exactly how your money moves from the client's invoice to your bank account.
We will break down every single deduction a compliant umbrella company handles for you, so you have total clarity on where every penny goes.
From Assignment Rate to Gross Pay
One of the biggest points of confusion for new contractors is the gap between the assignment rate and your gross pay for tax purposes. It's a simple distinction once you get it.
The assignment rate is the total amount your client pays the umbrella company for your work. Think of this as the master pot of money. This rate has to cover all the costs of your employment, not just your wage.
Before your personal gross pay can be worked out, a few mandatory employment costs have to be deducted straight from this assignment rate.
These costs include:
- Employer’s National Insurance Contributions: This is a legal requirement for any employer, calculated at 13.8% on earnings above the secondary threshold.
- The Apprenticeship Levy: A UK-wide tax on employers, set at 0.5% of their annual pay bill.
- The Umbrella Company Margin: This is the fee you pay the umbrella for running your payroll and handling all the admin. It’s usually a small, fixed amount each week or month.
- Employer’s Pension Contributions: If you’re auto-enrolled into a workplace pension, the employer's slice is also paid from the assignment rate.
Whatever is left after these deductions is your gross pay, the figure that’s then used to calculate your personal Income Tax and Employee's National Insurance.
Worked Example for a £400 Day Rate Contractor
Let's put this into practice with a real-life scenario. Meet Alex, a contractor working five days a week at a day rate of £400. We'll assume they're paid weekly and their umbrella company charges a margin of £25 per week.
1. Calculating the Weekly Assignment Income
First, we work out the total amount invoiced to the client for the week.
- £400 (day rate) x 5 (days) = £2,000
2. Deducting Employment Costs
Next, we subtract the employer costs from this total.
- Umbrella Margin: – £25.00
- Employer's NI (13.8%): – £242.02
- Apprenticeship Levy (0.5%): – £8.66
The total employment costs come to £275.68.
3. Determining Gross Pay for Tax Purposes
Now we can get to Alex's gross pay for the week.
- £2,000 (assignment income) – £275.68 (employment costs) = £1,724.32
This £1,724.32 is Alex's official gross pay. It's this figure that HMRC cares about for calculating his personal deductions.
The separation of the assignment rate and gross pay is a critical concept in umbrella employment. It ensures that all legal employment costs are covered transparently, as required by HMRC.
Calculating Alex’s Take-Home Pay
With a weekly gross pay of £1,724.32, we can now figure out Alex’s final take-home pay. We will use the standard 1257L tax code, which gives him a weekly tax-free allowance of £241.73 (£12,570 / 52 weeks).
Income Tax Calculation:
- Weekly Taxable Income: £1,724.32 – £241.73 = £1,482.59
- Taxable at Basic Rate (20%): £725.00 x 20% = £145.00
- Taxable at Higher Rate (40%): £757.59 x 40% = £303.04
- Total Weekly Income Tax: £145.00 + £303.04 = £448.04
Employee's National Insurance Calculation:
- Earnings between £242 and £967 (at 8%): £725 x 8% = £58.00
- Earnings above £967 (at 2%): (£1,724.32 – £967) x 2% = £15.15
- Total Weekly Employee's NI: £58.00 + £15.15 = £73.15
Final Net Pay:
- Gross Pay: £1,724.32
- Less Income Tax: – £448.04
- Less Employee's NI: – £73.15
- Net Pay for the Week: £1,203.13
As you can see, the process is perfectly logical once you break it down. By following the steps, you get a clear picture of how every pound is accounted for. If you want to see how these numbers might look for your specific rate, pop your details into our handy UK payroll calculator for a personalised estimate.
Navigating Common PAYE Adjustments
Life isn’t static, and neither is your tax situation. The standard PAYE calculation often needs a few tweaks to account for different events or financial decisions. Getting these adjustments right is crucial for making sure you pay the correct amount of tax over the year and avoid any nasty surprises from HMRC down the line.
Understanding these common variables is key to deciphering your payslip. Here at UmbrellaCompany.com, we handle all these adjustments behind the scenes, so you can be confident your payslip is always accurate and compliant.
What Is an Emergency Tax Code?
An emergency tax code is what HMRC gives you temporarily when they don't have enough information to assign the correct one. This usually happens when you start a new job, switch from being self-employed, or begin receiving company benefits.
You'll spot it on your payslip as something like 1257 W1, 1257 M1, or 1257 X. These codes give you the basic Personal Allowance but do not take into account any tax you've already paid in the tax year. This often means you’ll overpay tax for a short while until HMRC gets your records up to date.
Once everything is sorted, HMRC will issue a new code to your employer (or to us, as your umbrella company). Your tax deductions will then be corrected automatically, and you'll often get a refund in a future payslip.
Student Loan Repayments Through PAYE
If you've got a student loan, the good news is that your repayments are handled painlessly through the PAYE system. You will not start repaying until your income crosses a specific threshold, which varies depending on which repayment plan you're on.
HMRC simply tells your employer to make the deductions for them. The amount taken is a set percentage of whatever you earn above the repayment threshold for your particular loan plan.
Here’s a quick rundown of how it works:
- Plan 1, 2, 4, 5, and Postgraduate Loans: Each plan has its own annual and monthly earnings threshold before repayments kick in.
- Deduction Rate: For most plans, this is 9% of your income above that threshold.
- Automatic Process: The deductions happen at the same time as your tax and National Insurance, so there's nothing for you to manage manually.
Pension Contributions and Tax Relief
Putting money into a pension is one of the most tax-efficient ways to save for your future, and it’s all managed through your payslip. When you contribute to a workplace pension, you get tax relief, which is a way of saying some of the money that would have gone to the taxman goes into your pension pot instead.
For instance, if you're a basic-rate taxpayer and want to add £100 to your pension, you only have to contribute £80 from your take-home pay. The government then adds the extra £20, which is the tax you would have paid on that amount. The relief is even more generous for higher-rate taxpayers.
The total PAYE tax liability in the UK was approximately £413.3 billion in the 2023 to 2024 tax year. However, a 'tax gap' from unpaid taxes amounted to £3.9 billion, highlighting why accurate calculations and compliance are so important. You can discover more insights about these figures on the official government statistics page.
Statutory Payments and Other Deductions
Finally, PAYE is also used to handle statutory payments, which are the payments you're entitled to by law in certain circumstances. This includes things like Statutory Sick Pay (SSP) and Statutory Maternity Pay (SMP) or Paternity Pay.
These payments are treated just like normal earnings, meaning they are subject to both tax and National Insurance deductions. Our payroll systems calculate and process these for you automatically, ensuring you get exactly what you're owed while keeping everything fully compliant with HMRC rules.
How Umbrella Companies and IR35 Shape Your PAYE
For contractors in the UK, getting to grips with PAYE often means understanding its relationship with umbrella companies and the IR35 rules. It’s a crucial connection. When you decide to work through an umbrella company, you effectively become their employee. This one change has a huge knock-on effect on how your pay is calculated and how your taxes are handled.
A good, compliant umbrella company steps in and takes on all the legal duties of an employer. This means it’s our job to process your earnings and make every single necessary PAYE deduction for you. By the time the money hits your bank, it has all been taken care of.
The Role of an Umbrella Company in PAYE
Think of an umbrella company as the intermediary between you and your end client (or recruitment agency). When the client pays the invoice for your hard work, the money comes to us first. We then run these funds through our payroll system, making sure all the legal employment costs are covered before we even start on your personal deductions.
This system takes a massive weight off your shoulders. You get the freedom of contracting combined with the security and employment rights you’d get in a permanent role, but without the headache of running your own limited company. If you want to dive deeper into the nuts and bolts, check out our guide on how an umbrella company works.
The deductions we handle on the employment side of things include:
- Employer’s National Insurance Contributions: This is a non-negotiable cost for every UK employer.
- The Apprenticeship Levy: A tax that larger employers pay to help fund apprenticeship schemes.
- Our Margin: This is our small, fixed fee for running your payroll and handling all the admin.
Once those costs are settled, what’s left is your gross pay for tax purposes. From this figure, we calculate your personal Income Tax and Employee’s National Insurance contributions, exactly as any other employer in the country would.
Connecting PAYE Calculations to IR35
Now, let's talk about IR35, otherwise known as the off-payroll working rules. This legislation is all about making sure that contractors who work in a way that’s similar to a permanent employee pay a similar amount of tax. If your contract is deemed ‘inside IR35’, it means your working arrangement is classed as 'deemed employment'.
When a contract falls inside IR35, the organisation paying you, be it the client or an agency, has a legal duty to deduct tax and National Insurance at source through PAYE. This is precisely where an umbrella company offers a clean, compliant solution. By making you our employee, we guarantee that these mandatory PAYE deductions are sorted out correctly, right from your very first payment.
Working through an umbrella company when you’re inside IR35 isn't just an option; it's a way to ensure you're fully compliant with HMRC's rules. It completely removes the risk of incorrect tax treatment for both you and your client.
This direct link between being inside IR35 and needing to use PAYE is why so many contractors go down the umbrella route. It brings genuine peace of mind, knowing a professional is managing your tax obligations. Plus, you get a detailed payslip every time, showing every single calculation, which gives you total transparency and helps you keep on top of your finances.
Still Have Questions About PAYE?
It's completely normal to have a few questions swirling around about your pay and tax. The PAYE system has a lot of moving parts, and honestly, it can feel a bit confusing at times. We've pulled together some of the most common queries we get from contractors to give you clear, straightforward answers.
Think of this as your go-to guide for clearing up those last few uncertainties about your payslip.
Why Is My Tax Code Different from 1257L?
Seeing a tax code other than the standard 1257L can be a bit of a surprise, but it's usually for a good reason. Your code might change if you're juggling more than one job, receiving a taxable company benefit like private medical insurance, or perhaps you underpaid some tax in a previous year.
HMRC adjusts your tax code to make sure the right amount of tax is collected automatically, saving you a headache later. If your code changes, they will send you a notice explaining why. It is always worth a quick read to understand what's happened.
What's the Difference Between Employee and Employer National Insurance?
This is a classic point of confusion, but the distinction is pretty simple. Both are mandatory contributions, but they come from different places.
- Employee's NI is the amount deducted directly from your gross pay. It's your contribution.
- Employer's NI is an extra cost the employer pays on top of your earnings.
For contractors working through an umbrella company, this is where it gets interesting. The Employer's NI is also deducted from the assignment income sent over by your client. That is because the rate you agree with the client has to cover all the associated employment costs, including this one.
How Can I Check if My PAYE Calculation Is Correct?
Feeling the need to double-check the numbers is smart. You can use HMRC's official online tax calculator to get a reliable estimate of what your Income Tax should be. It’s a great way to put your mind at ease.
Your payslip from us will always give you a full, detailed breakdown of every single deduction. If you ever spot something that doesn't look right, or you think your tax code is wrong, the best course of action is to contact HMRC directly. They are the only ones who can sort it out, and it's always best to get it resolved quickly.
Getting to grips with how PAYE is calculated really puts you back in the driver's seat of your finances. By breaking it all down, we hope you feel more confident and empowered as a contractor.
Navigating the world of contractor payroll can be tricky, but you do not have to figure it all out on your own. UmbrellaCompany.com makes it simple to compare trusted, compliant umbrella companies to find the perfect fit for you.
Find your ideal umbrella company today at https://umbrellacompany.com.


