


Getting your head around PAYE, or Pay As You Earn, does not need to be complicated. At its core, the process is straightforward: take your gross earnings, subtract your tax-free Personal Allowance to find your taxable income, and then apply the correct tax and National Insurance rates.
That is the theory. Now, let’s get into the practical side of things.
A Contractor’s Guide to Calculating PAYE
If you are a contractor, especially one working through an umbrella company, getting a firm handle on PAYE is essential. It is the system HMRC uses to collect Income Tax and National Insurance Contributions (NICs) straight from your pay. Understanding how it works is the key to financial planning and making sure there are no surprises on payday.
Here at UmbrellaCompany.com, we aim to give every contractor the confidence to read their payslip and accurately forecast their take-home pay. This guide breaks down each part of the calculation, so you know exactly where your money is going.
The Building Blocks of Your PAYE Calculation
Before you can crunch the numbers, you need to know the key pieces of the puzzle. These are the fundamental elements that determine how much of your gross income ends up with HMRC and how much lands in your bank account.
Let's quickly run through the main components.
- Your Tax Code: This is a short string of numbers and letters that tells your umbrella company how much income you can earn tax-free.
- Your Personal Allowance: This is the specific amount you can earn before you start paying any Income Tax. It is dictated by your tax code.
- Income Tax Bands: The UK tax system is progressive. This means different tax rates apply to different portions of your earnings once you are over the Personal Allowance.
- National Insurance Contributions (NICs): These are mandatory payments that go towards funding state benefits like the NHS and your State Pension.
To give you a clearer picture, here’s a quick summary of what you need to know before we dive into the calculations.
Key PAYE Components at a Glance
| Component | What It Means for You | Current UK Rate or Amount |
|---|---|---|
| Personal Allowance | The amount you can earn before Income Tax kicks in. | Standard is £12,570 per year. |
| Tax Code | Tells your employer how much Personal Allowance you get. | Standard is 1257L for most people. |
| Income Tax Bands | Different rates apply to earnings within set brackets. | Rates are 20%, 40%, and 45%. |
| Employee NICs | A percentage paid on earnings above a threshold. | Primary rate is 8% on earnings between £12,570 and £50,270. |
These figures are the foundation for any PAYE calculation you will do.
The Personal Allowance is currently frozen at £12,570 a year. As contractor day rates and salaries rise, this freeze means more people will find themselves crossing the tax threshold for the first time. This makes it more important than ever to understand how these numbers fit together.
When you understand these individual parts, you can piece together the entire PAYE puzzle. It transforms a complex calculation into a predictable and manageable part of your contracting career.
Grasping these concepts is the first step toward mastering your finances. For a deeper dive, check out our guide on how Pay As You Earn works. Next, we will break down each of these components in more detail.
Finding and Understanding Your Tax Code
Getting to grips with your tax code is the first real step in figuring out your PAYE. Think of it as a small but vital instruction that tells your umbrella company exactly how much you can earn before any tax is taken.
Getting this right from the outset is crucial if you want to avoid any unpleasant surprises from HMRC down the line.
The tax code you will see most often is 1257L. This is the standard, default code for the current tax year, issued to most people with one job who do not have other untaxed income or benefits-in-kind. It is quite simple to break down: the number 1257 means you have a Personal Allowance of £12,570 (the last digit is removed).
The letter 'L' simply confirms you’re entitled to that standard tax-free Personal Allowance. You might see other letters, but 'L' is by far the most common.
Where Can I Find My Tax Code?
Thankfully, your tax code is not hidden away. You can usually spot it on:
- Any payslip from your umbrella company.
- Your P45, if you have recently finished a contract or left a job.
- A P60, which is the summary of your pay and tax for the year.
- Your personal tax account on the GOV.UK website.
Honestly, the quickest way is usually to log into your online tax account. You can see your current code and check if it has changed recently.
Why Your Tax Code Might Change
Your tax code is not set in stone. HMRC can, and often does, change it during the tax year. When they do, it means they have adjusted your Personal Allowance, which has a direct knock-on effect on your take-home pay.
There are a few common reasons this happens:
- Starting a new contract: You are often put on a temporary emergency tax code until HMRC sorts things out.
- Running multiple contracts at once: HMRC will split your Personal Allowance across your jobs to make sure you pay the correct amount of tax overall.
- Receiving taxable benefits: Things like a company car or private health insurance reduce your tax-free allowance.
- Claiming tax relief on expenses: If you have allowable work-related expenses, HMRC might increase your code to give you tax relief.
An incorrect tax code is one of the most common reasons people end up overpaying or underpaying tax. If a coding notice from HMRC drops through your letterbox, always give it a once-over to make sure they have their facts straight.
If your code looks wrong, do not just ignore it. Get in touch with HMRC as soon as you can to get it fixed. This saves a lot of hassle later on. If you find yourself on the wrong code, our guide on what to do about an emergency tax code has some useful pointers.
Right, you have got your tax code sorted. Now for the main event: figuring out your Income Tax deduction.
At its core, the process is logical. You just need to work out what part of your gross pay is actually taxable, and then apply the correct tax rates to that amount. It might seem a bit daunting at first, but once you get the hang of it, you will be able to check your payslip with confidence and stay on top of your finances.
Isolating Your Taxable Income
Before HMRC takes a penny, you need to ring-fence your tax-free earnings. This gives you your taxable income.
For most contractors on the standard 1257L tax code, this is straightforward. You simply take your gross pay for the period and subtract the portion of your Personal Allowance that applies.
- Annual Personal Allowance: £12,570
- Monthly Tax-Free Amount: £1,047.50 (£12,570 ÷ 12)
- Weekly Tax-Free Amount: £241.73 (£12,570 ÷ 52)
Anything you earn above these figures in a given pay period is what gets taxed. It is that simple.
The golden rule here is that you only pay tax on earnings that go beyond your Personal Allowance. By getting this taxable figure right first, the rest of the calculation falls into place much more easily.
This is why getting your tax code right is so crucial from the outset, as this handy little flowchart shows.
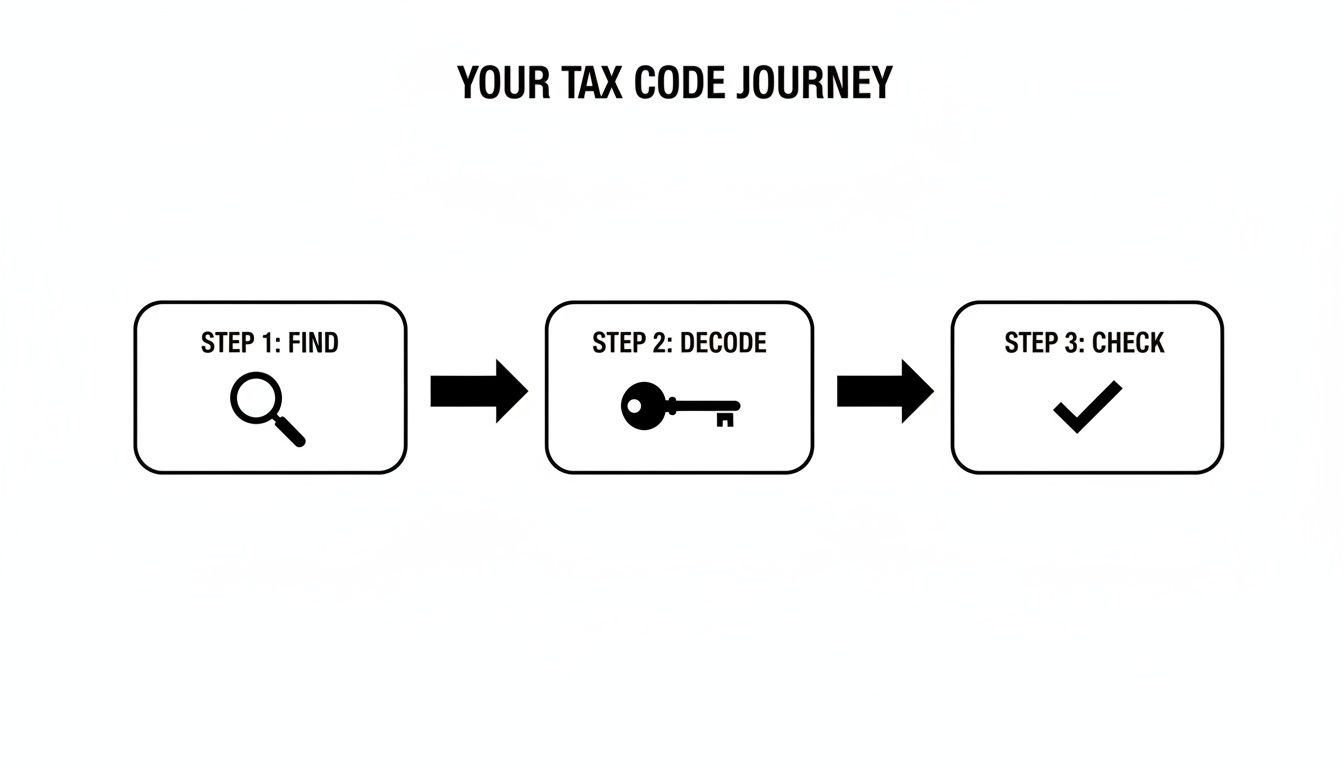
It really all starts here. If your tax code is wrong, everything that follows will be, too.
Applying the UK Tax Bands
Once you have your taxable income, it is time to apply the tax bands. The UK uses a progressive system, which just means different portions of your income get taxed at different rates.
For contractors in England, Wales, and Northern Ireland, the main bands are:
- Basic Rate: 20% on taxable income up to £37,700.
- Higher Rate: 40% on taxable income from £37,701 to £125,140.
- Additional Rate: 45% on taxable income over £125,140.
A key thing to remember is that these bands kick in after your Personal Allowance has already been accounted for.
This is especially relevant right now. With recent ONS data showing average regular earnings grew by 4.5% annually and 39% of UK employers planning pay rises, many contractors could find themselves tipping into a higher tax bracket. It pays to keep an eye on your earnings.
A Worked Example of a Weekly Calculation
Let's see how this works in the real world. Imagine you are a contractor on a weekly assignment rate of £750.
- Gross Pay: £750.00
- Subtract Weekly Allowance: £750.00 – £241.73 = £508.27 (this is your taxable income)
- Calculate Basic Rate Tax: £508.27 x 20% = £101.65 Income Tax
So, from your £750 weekly pay, you would have £101.65 deducted for Income Tax.
If you want to play around with different numbers or see a more detailed breakdown, our purpose-built UK payroll calculator is a great tool for running different scenarios.
Working Out Your National Insurance Contributions
Income Tax is only one side of the PAYE coin. The other major portion taken from your payslip will be for National Insurance Contributions (NICs), which funds state benefits like the NHS, Jobseeker's Allowance, and the State Pension.
As a contractor working through a compliant umbrella company, you’ll be paying Class 1 NICs. The system has some similarities to Income Tax, using thresholds and rates, but it is crucial to remember that it is an entirely separate calculation. Do not mix them up.
Understanding the NI Thresholds
This is where things differ from Income Tax. While income tax is typically based on an annual figure, your National Insurance is calculated purely on what you earn in that specific pay period, be it weekly or monthly. The slate is wiped clean each time you are paid; what you paid last month has no bearing on this month.
Here are the key thresholds you need to know for your employee contributions:
- Lower Earnings Limit (LEL): You do not pay any NI on earnings below £123 per week, but you still get the credit towards your State Pension qualifying years. It is a good-to-know figure.
- Primary Threshold (PT): This is the important one, it’s the point you actually start paying National Insurance. It is set at £242 per week or £12,570 per year, neatly aligning with the standard Personal Allowance.
- Upper Earnings Limit (UEL): Once your earnings push past this point, the NI rate drops off sharply. The UEL is £967 per week or £50,270 per year.
These thresholds slice up your gross pay and determine how much is subject to the different NI rates.
How to Compare Income Tax Bands and NI Thresholds
It is easy to get the different bands and thresholds for tax and NI muddled. They both apply to your gross earnings, but the percentages and the income levels at which they kick in are completely different.
Here’s a simple table to help you see the key differences at a glance:
| Deduction Type | Band or Threshold Name | Earnings Range | Percentage Rate |
|---|---|---|---|
| Income Tax | Personal Allowance | Up to £12,570 | 0% |
| Income Tax | Basic Rate | £12,571 to £50,270 | 20% |
| Income Tax | Higher Rate | £50,271 to £125,140 | 40% |
| Income Tax | Additional Rate | Over £125,140 | 45% |
| National Insurance | Below Primary Threshold (PT) | Up to £12,570 | 0% |
| National Insurance | Between PT and Upper Earnings Limit (UEL) | £12,571 to £50,270 | 8% |
| National Insurance | Above Upper Earnings Limit (UEL) | Over £50,270 | 2% |
As you can see, the main employee NI rate of 8% applies to the same portion of earnings as the basic rate of Income Tax. The key takeaway is that they are two separate deductions calculated independently.
Applying the Class 1 NI Rates
The main rate of employee National Insurance currently stands at 8%. This is what you will pay on your earnings that fall between the Primary Threshold and the Upper Earnings Limit.
Should your earnings go above that Upper Earnings Limit, any income you make beyond that point is subject to a much lower rate of just 2%.
Your National Insurance calculation is a separate process from your Income Tax calculation. While both use your gross earnings as a starting point, they apply different thresholds and rates, so it is vital not to confuse the two.
Let's walk through a practical example to see how this works for a typical contractor.
A Weekly NI Calculation Example
Let's say you are a contractor on a weekly rate of £850. Here’s the step-by-step breakdown of how your employee National Insurance would be calculated for that week:
- The first portion is NI-free. The first £242 of your earnings is below the Primary Threshold, so no NICs are due on this part. (£0 NI)
- Calculate the taxable portion. Next, we see what’s left. £850 (gross pay) – £242 (PT) = £608. This is the amount of your pay that falls between the PT and the UEL.
- Apply the main NI rate. This £608 is charged at the main employee rate of 8%.
- Work out the final figure. £608 x 8% = £48.64.
Simple as that. Your total employee National Insurance deduction for the week would be £48.64. Because your weekly pay of £850 is well below the Upper Earnings Limit of £967, the lower 2% rate does not come into play at all.
Umbrella Company and Other Common Deductions
When you are contracting through an umbrella company, your payslip has a few more lines on it than just Income Tax and National Insurance. To get a real grip on how to calculate PAYE and understand your final take-home pay, we need to look at all the legitimate deductions that show up.
These deductions cover everything from pension contributions and student loan repayments to the specific employment costs that an umbrella company manages for you. Getting familiar with them is the key to seeing exactly how your assignment rate translates into the money that hits your bank account.
Pension Contributions
Thanks to auto-enrolment rules, your umbrella company will sign you up for a workplace pension scheme. The contributions you make are usually taken straight from your gross pay, before any tax is calculated.
This is a really tax-efficient way to save for your future. Because the money comes out pre-tax, you get tax relief on every penny you put in, which brings down your overall tax bill. It might look like a large amount coming out, but it is a deduction that is working directly for you.
Student Loan Repayments
If you have a student loan, repayments are another standard deduction that HMRC handles through the PAYE system. They simply tell your umbrella company which plan you are on, and the correct percentage is automatically taken from any earnings above the threshold for that year.
There are a few different plans, each with its own repayment rate and earnings threshold:
- Plan 1: Typically for those who started their course before 1 September 2012.
- Plan 2: For courses that began between 1 September 2012 and 31 July 2023.
- Plan 4: A specific plan just for Scottish students.
- Plan 5: The newest plan, for courses started on or after 1 August 2023.
- Postgraduate Loan: This has its own unique threshold and repayment rate.
You do not need to do anything; it is all calculated and deducted for you based on what you earn.
Getting your head around these other deductions is just as important as the main tax and NI calculations. They all affect your net pay, and knowing what each one is for gives you total clarity on where your money is going.
Deductions Specific to Umbrella Employment
Working with an umbrella company introduces a couple of specific costs that are part of being an employee. It is crucial to understand that these are deducted from the assignment rate agreed with your agency, not from your personal salary. That is why the assignment rate is uplifted, to cover these costs.
First up is the umbrella company margin. This is the fixed amount we charge for handling all the payroll, admin, and compliance that comes with being your employer. At UmbrellaCompany.com, we make sure this is always clearly and transparently itemised on your payslip.
Then you have the statutory costs that every employer in the UK has to cover. This includes Employer's National Insurance and, where it applies, the Apprenticeship Levy. These are not your costs to bear; they are genuine business expenses covered by the assignment rate. You can find a deeper dive into how this all fits together in our guide for freelancers using an umbrella company.
By understanding this structure, you can clearly see how the rate from the agency is broken down to cover all employment costs, process your tax and NI correctly, and arrive at your final take-home pay.
Common Questions About Calculating PAYE
Even after you have got the hang of the calculations, a few questions always seem to pop up. Let's tackle some of the most common queries we hear from contractors to clear up any lingering confusion.
What Should I Do If My Tax Code Is Wrong?
If you get that sinking feeling that your tax code is wrong, it is really important to sort it out quickly. The wrong code means you are either overpaying or underpaying tax, both of which create problems down the line.
Your first port of call should be HMRC. The easiest way is usually through your online personal tax account, but you can also phone them. Just explain why you think it’s incorrect, maybe you have just finished a second contract and it has not been updated. HMRC will take a look and, if needed, send a new coding notice to us, your umbrella company, so we can adjust your deductions straight away.
Why Do My NI Contributions Vary Each Month?
This one catches a lot of people out. Unlike Income Tax, which is typically cumulative across the tax year, your National Insurance is calculated on a non-cumulative basis. This simply means it is worked out purely on what you earn in that specific pay period, whether it is weekly or monthly.
Your NI calculation resets with every single payslip. What you earned or paid in previous months has absolutely no bearing on the current month's calculation.
For contractors whose pay can fluctuate, this is why your NI deduction will go up and down from one payslip to the next. It is a direct reflection of your earnings for that specific period.
Can I Claim Expenses Through an Umbrella Company?
This is a big one, especially since the IR35 off-payroll working rules were rolled out. The short answer is that for most umbrella contractors, the ability to claim tax relief on travel and subsistence has been heavily restricted.
If your assignment is deemed 'inside IR35', you are essentially treated like a permanent employee for tax purposes. This means you generally cannot claim tax relief on your daily commute. There might be some specific, allowable business expenses you can still claim, but it really depends on the fine print of your contract. We always recommend having a chat with our team about your specific situation to make sure everything stays above board and compliant.
At UmbrellaCompany.com, our entire focus is on making the payroll process as clear and straightforward as possible for contractors like you. If you are looking for a compliant, reliable umbrella service that gives you total transparency, we are here to help.
Find the perfect umbrella company for your needs at https://umbrellacompany.com.


