


Before you even touch a calculator, the real work begins. Figuring out your daily rate is not just about plugging numbers into a formula; it is about knowing what annual income you should be aiming for in the first place. This number is a moving target, heavily influenced by your industry, experience, where you are based, and the unique skills you bring to the table.
Setting a rate that is both competitive and realistic is the foundation of a solid contracting career.
What Really Influences Your Daily Rate
Pricing yourself as a business is a world away from negotiating a salary for a permanent role. Your daily rate has to cover more than just your expertise. It needs to account for the costs, risks, and lack of benefits that come with being an independent professional.
Your Industry and Specialised Skills
The single biggest factor dictating what you can earn is the industry you're in. It is a simple case of supply and demand. A software developer with a niche specialism in cybersecurity, for instance, will naturally command a much higher rate than a generalist administrator.
Why? Because highly specialised skills are in greater demand and the pool of qualified people is much smaller.
Think about it this way:
- Niche Expertise: Do you hold specific certifications or have deep experience in a sought-after technology or methodology? That kind of specialisation justifies a premium.
- Years in the Game: A seasoned contractor with a decade of proven results under their belt can charge significantly more than someone just starting out. Experience is not just a number; it is a track record of delivering value.
- Market Demand: Some sectors are just hotter than others. When there is rapid growth and fierce competition for talent, rates go up.
To give you a clearer picture, here’s a quick look at how rates can vary across different trades.
Example Daily Rates for UK Construction Trades
This table offers a snapshot of the average daily rates for various skilled trades in the UK. Notice how much specialisation can impact the figures.
| Trade Speciality | Average Daily Rate (Approx.) |
|---|---|
| General Labourer | £120 – £150 |
| Carpenter | £180 – £220 |
| Plumber | £200 – £250 |
| Electrician | £220 – £280 |
| Bricklayer | £190 – £240 |
| Plasterer | £180 – £230 |
As you can see, the more specialised and licensed the trade, the higher the potential daily rate. This principle applies across nearly every industry, from IT to finance.
Location and Regional Differences
It is no secret that where you work in the UK makes a difference. A contract based in central London will almost always pay more per day than the same job in Manchester or Glasgow. This "London weighting" is there to offset the higher cost of living and reflects the concentration of big corporate clients in the capital.
That said, the recent boom in remote working has started to shake things up. It has given contractors outside the major city hubs a real chance to compete for those higher-paying gigs without having to relocate.
Of course, knowing the market rate is one thing; securing it is another. Mastering some effective contract negotiation strategies is absolutely crucial for getting the best possible daily rate agreed.
By properly analysing these factors (your industry, specific skills, and location) you stop guessing what you are worth and start strategically pricing your services. This is the groundwork that turns any daily rate calculator from a simple tool into a powerful asset.
From Permanent Salary to a Contractor Rate
Making the jump from a permanent job to contracting is a big move, especially when you start thinking about money. How do you set your rate? A good place to start is with a permanent salary for a similar role.
But you cannot just divide that salary by the number of working days in a year. That is a common rookie mistake. You need to build in a vital uplift.
This uplift, usually somewhere between 20% and 30%, is your financial cushion. It is there to make up for all the benefits and security you are leaving behind on the PAYE payroll. As a contractor, you are the one footing the bill for these things now.
Why the Uplift is Non-Negotiable
That extra percentage is not just for padding your pockets. It is a professional necessity, a crucial part of your business model that covers the very real costs you now face. It accounts for all the valuable perks you no longer get from an employer, such as:
- Paid Holidays: You will not get paid for bank holidays or that two-week summer break.
- Sick Pay: If you are too ill to work, your income stops dead.
- Employer Pension Contributions: That brilliant top-up to your retirement pot? That is all on you now.
- Other Perks: Think about private health insurance, gym memberships, or company car schemes. Those costs now come out of your pocket.
If you skip this step, you are essentially working for less than your permanent colleagues once you factor everything in. Adding the uplift is fundamental to making sure your contracting career is viable from day one.
Calculating Your Billable Days
Next up, you need a realistic handle on how many days a year you can actually charge for. Hint: it is not every weekday.
A fairly standard calculation starts with the total number of weekdays and then strips out all your non-working time:
- Total Weekdays: 260 (that is 52 weeks x 5 days)
- Subtract Bank Holidays: -8 days
- Subtract Annual Leave: -20 days (for a standard 4 weeks off)
- Subtract Sick Days/Downtime: -10 days (a sensible buffer for illness or gaps between contracts)
This leaves you with 222 billable days in a typical year. This figure is the bedrock of your day rate calculation. Using a realistic number like this stops you from over-promising and under-charging, which is key to hitting your financial goals.
Remember, these numbers are just a starting point. If you know you will take more holiday or you anticipate longer gaps finding your next project, you have to adjust your billable days down. This is the only way to get a day rate that truly works for you.
Accounting for Your Business Overheads
One of the biggest mindset shifts for any new contractor is learning to see yourself as a business. It is a crucial step. Your daily rate is not just your take-home pay; it is the total revenue that has to cover every single cost of running your operation professionally.
If you do not properly account for these overheads, you end up paying for them out of your own pocket. That eats directly into your real earnings. Thinking like a business owner from day one is what sets you up for profitability and a sustainable career.
Identifying Your Core Business Expenses
Before you can nail down a final figure, you need a comprehensive list of all your business costs. These are the non-negotiable expenses that keep you running smoothly and, just as importantly, compliantly.
Most of these will be annual costs. The trick is to total them up and then divide that figure by the number of days you plan to work in a year. This builds them right into your daily rate.
Essential overheads almost always include:
- Business Insurance: Most clients will insist on you having Professional Indemnity and Public Liability insurance. It is not just a box-ticking exercise; it protects you from claims of negligence or accidental damage.
- Accountancy Fees: Unless you are a tax whizz, you will need a good accountant. They will handle your tax returns, VAT submissions, and provide general financial guidance.
- Software and Hardware: This bucket covers everything from specialist software licences and new laptops to subscriptions for tools like project management apps.
- Professional Memberships: Do not forget the annual fees for any industry bodies or professional organisations that are vital for your work.
It is not just about tracking what you spend; using the right tools can make a huge difference. This strategic guide to cloud accounting solutions has some excellent insights into managing your finances more effectively.
Planning for Growth and Security
A smart contractor does not just think about the current contract; they plan for the future. Your daily rate needs to be high enough to fund your personal and professional development, keeping you competitive and financially secure.
Make sure you are setting money aside for:
- Training and Development: Budget for courses, certifications, and conferences. Your skills are your product, so you need to keep them sharp.
- Marketing and Networking: This could be the cost of a professional website, a LinkedIn Premium account, or attending key industry events.
- Your Pension: This one is huge. With no employer contributions, it is all on you. A decent chunk of your rate needs to go straight into your pension pot.
- Contingency Fund: An emergency fund is non-negotiable. It is your safety net for quiet periods between contracts or unexpected business costs.
By annualising these essential and forward-thinking costs and incorporating them into your daily rate calculation, you transform your rate from a simple wage into a comprehensive business charge. This proactive approach ensures you are not just surviving but thriving as an independent professional.
Factoring in Tax, National Insurance, and Pensions
Okay, so you have accounted for your business overheads. The next big piece of the puzzle is your personal financial obligations. It is a common rookie mistake to see a big daily rate and think that is what you will pocket. It is not.
Your gross rate is just the starting point. To get to a realistic take-home figure, you absolutely have to factor in tax, National Insurance, and your pension contributions from day one. This is not just good practice; it is non-negotiable for staying financially stable.
These deductions can feel like a minefield when you are starting out, but they are a fundamental part of being your own boss. Get this wrong, and you are in for a nasty shock when HMRC comes knocking.
Understanding Your Tax and NI Liabilities
How much tax you pay really depends on how you are set up. If you operate through your own limited company, you have Corporation Tax to think about, which is levied on your company's profits. Currently, the main rate is 25% for profits over £250,000, with a smaller profits rate of 19% kicking in for profits up to £50,000.
Then there is National Insurance Contributions (NICs). When you pay yourself a salary from your company, you face two types:
- Employee's NICs (Class 1 Primary): This comes directly off your salary.
- Employer's NICs (Class 1 Secondary): This is paid by your limited company on top of your salary.
That Employer's NIC is a big one. It is a significant cost that permanent employees never even see, so it is absolutely vital you build it into your day rate calculation. For a much deeper look at this, our guide on the most tax efficient way to pay yourself as a contractor in the UK is well worth a read.
Here is the key takeaway: Your daily rate has to cover more than just your personal tax. It needs to be high enough to absorb business-level taxes and those sneaky Employer’s NICs. Misjudge this, and your net income will take a serious hit.
Building Your Pension Pot
One of the biggest shifts when you leave permanent employment is the lack of an employer pension contribution. Suddenly, you are the only one responsible for your retirement fund. Your day rate must reflect this new responsibility.
Most financial advisors suggest stashing away a percentage of your earnings that ties in with your age or retirement goals. A solid rule of thumb is to aim for at least 12-15% of your income. By building this cost directly into your day rate from the start, saving for retirement becomes a regular, manageable habit, not something you scramble to do at the end of the year.
A Practical Scenario for Deductions
Let’s put some numbers to this. Imagine your initial calculations point to a target annual income of £70,000 before any personal tax. You need to build a buffer on top of this for all those deductions we have just talked about.
Here is a quick, simplified look at what that might mean:
- Your Target Income: £70,000
- Estimated Employer's NICs: Around £6,000 (this would be calculated on a small, tax-efficient salary portion)
- Pension Contribution (12%): £8,400
- Corporation Tax Provision: This will depend on your total profit, but you have to set money aside for it.
Just adding those up, you can see your business needs to bring in revenue significantly higher than your personal income target. By plugging these costs into your day rate calculation, you will land on a final figure that is robust enough to cover everything, securing both your finances today and your future.
Untangling IR35 and Your Umbrella Company Rate
The IR35 legislation is probably the single biggest factor that dictates your real take-home pay as a contractor. Getting your head around it is not just a box-ticking exercise; it is fundamental to planning your finances and setting a day rate that actually works for you.
Put simply, your IR35 status dictates how you are paid. If a contract is ‘outside IR35’, you are seen as a genuine business, running your own limited company and handling your own tax affairs. But if a role is deemed ‘inside IR35’, things change. Your client has to deduct tax and National Insurance right at the source, almost as if you were a permanent employee.
How an 'Inside IR35' Status Changes Things
When a contract lands inside IR35, the day rate you see advertised is not what lands in your bank. It is the gross figure before a whole load of deductions are made, including PAYE tax, employee's NI, and the big one: employer’s National Insurance Contributions.
This is where an umbrella company becomes the go-to, compliant solution for most contractors. We, at UmbrellaCompany.com, effectively become your employer for tax purposes and handle all those deductions for you, making sure everything is square with HMRC. If you need a full refresher, it is worth taking a moment to understand what IR35 is and how it works.
The most common pitfall we see is contractors forgetting to account for employer’s NI and the Apprenticeship Levy when quoting their rate for an inside IR35 job. These are deducted from the gross rate the client pays, so your day rate has to be high enough to soak up those costs.
Building Umbrella Costs into Your Day Rate
Working through an umbrella company simplifies everything by putting you on our payroll. In return for handling all the admin, tax, and NI payments, we keep a small, fixed amount from your invoiced income. This is called the umbrella margin. It is a flat weekly or monthly fee, never a percentage, and it is something you must factor into your day rate calculations.
When you are figuring out your rate for an inside IR35 contract, you absolutely have to build in:
- The Umbrella Margin: Our competitive margin covers all the payroll and administrative heavy lifting.
- Employer’s NI: This gets deducted from the assignment rate we receive from your agency or client.
- Apprenticeship Levy: Another small deduction that comes out of the gross assignment rate.
Most contractors prefer to set a clear daily rate. It makes billing simpler and gives you a predictable income stream. The only real downside is that it usually does not cover overtime, which is something you might get with an hourly rate model.
By carefully building these specific costs into your sums, you can set a day rate that ensures your take-home pay lines up with your expectations. No nasty surprises, just clarity from the get-go.
Putting It All Together: A Worked Example
Right, let's get practical. Theory is one thing, but seeing how all these numbers slot together is what really matters. We are going to walk through a complete, real-world example from start to finish, building a contractor's daily rate from the ground up.
Think of this as a template you can pinch and adapt for your own situation. It will help you land on a rate that is not just profitable, but robust.
Starting with the Target Income
Let us invent a contractor. We will call him Alex. Alex is a project manager who wants to draw a personal income of £60,000 a year. This is the figure he wants to see before his own personal tax, but after all his business costs are covered. This is our baseline.
Using our earlier calculation of 222 billable days in a year, we can get a very rough starting point:
- £60,000 / 222 days = £270.27 per day
Honestly, this figure is a trap. It is dangerously low because it ignores all the costs of running a business, not to mention things like tax liabilities or pension contributions. It is just a raw conversion of salary to a day rate, and it is not enough.
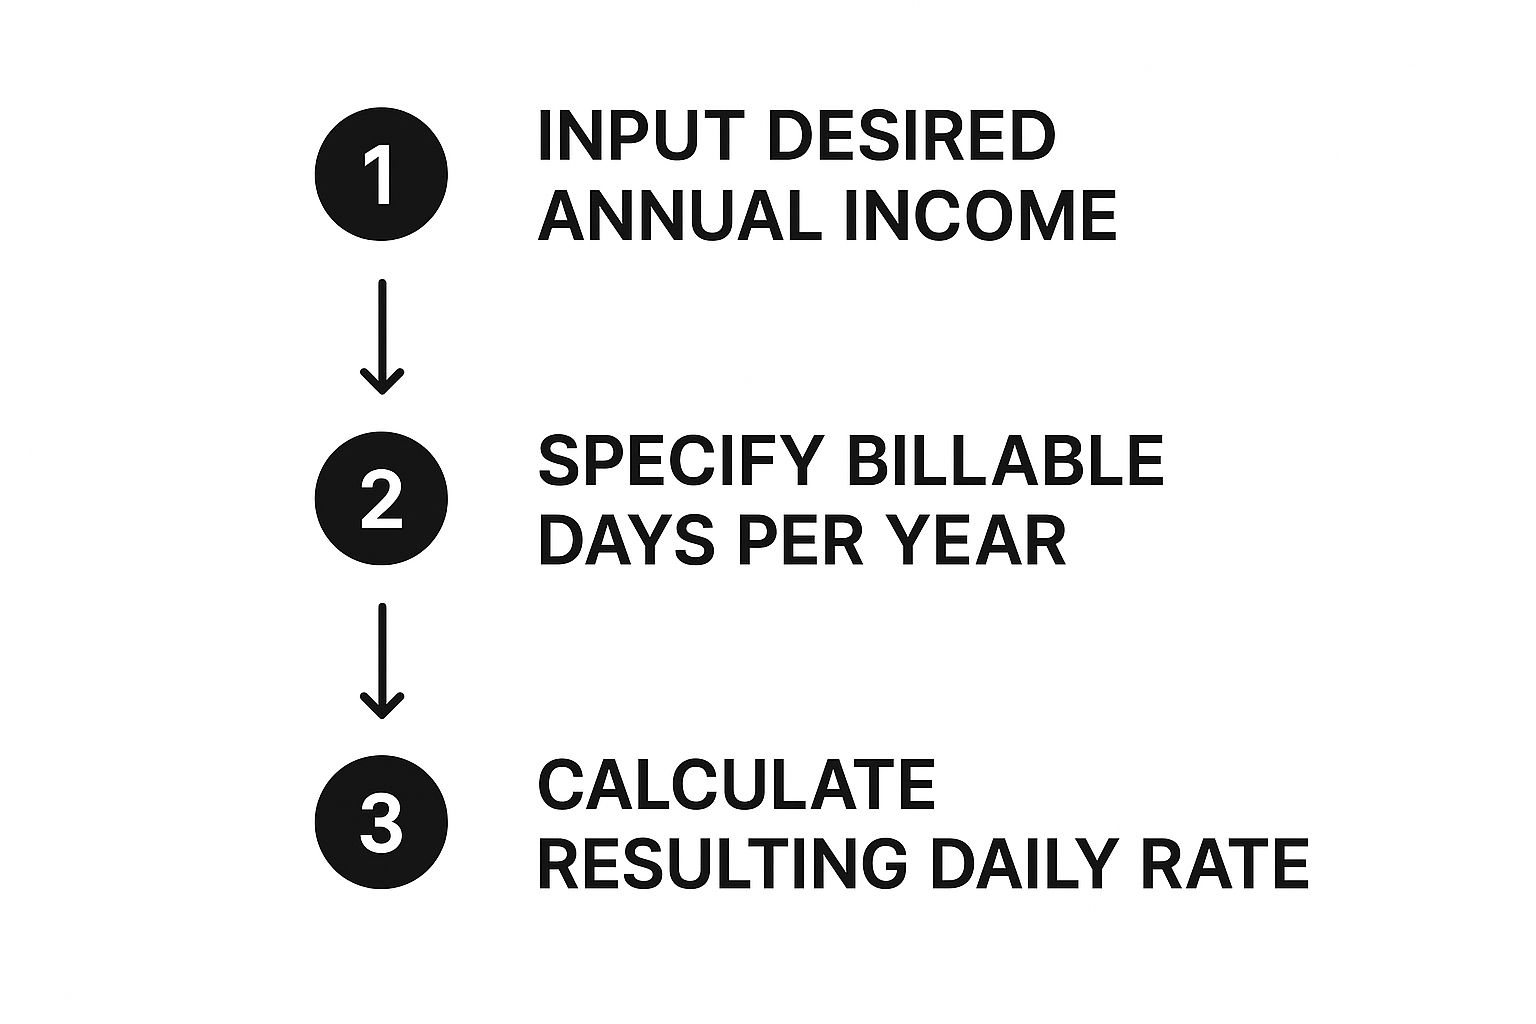
This gives you the basic idea, but now for the important bit: layering in all the real-world costs to find the rate you actually need to charge.
Adding Business Costs and Financial Planning
Okay, now we need to build up the total turnover Alex's business has to generate. We will start adding in estimated annual costs for his overheads, pension, and a buffer for business taxes.
Here is a realistic breakdown:
- Insurance (Professional Indemnity & Public Liability): £500
- Accountancy Fees: £1,200
- Software & Subscriptions: £600
- Pension Contributions (a healthy 12% of £60k): £7,200
- Employer's National Insurance (on a salary of £12,570): £0 (falls below the threshold)
- Contingency Fund (a sensible 5%): £3,000
When we add all those necessary costs to his target income, we get a completely new revenue goal for the business:
£60,000 (Target Income) + £12,500 (Total Costs) = £72,500
That £72,500 is the magic number. It is the total amount Alex's business needs to invoice over the year to cover every single expense and still hit his personal income goal.
To make this crystal clear, here is a table showing how we got from the initial goal to the final required turnover.
Worked Example Daily Rate Calculation Breakdown
| Calculation Step | Amount (£) |
|---|---|
| Target Personal Income | £60,000 |
| Insurance | £500 |
| Accountancy | £1,200 |
| Software | £600 |
| Pension Contributions | £7,200 |
| Employer's NI | £0 |
| Contingency Fund | £3,000 |
| Total Annual Revenue Needed | £72,500 |
| ÷ Billable Days | 222 |
| Calculated Daily Rate | £326.58 |
| Final Quoted Rate (Rounded) | £330 |
This breakdown shows the journey from a simple salary aspiration to a professional, sustainable day rate that accounts for the realities of contracting.
Calculating the Final Daily Rate
With that comprehensive revenue target of £72,500, we can now calculate a much more realistic daily rate.
- £72,500 / 222 billable days = £326.58 per day
Now, you would not quote £326.58. It is messy. To be safe and present a clean, marketable number, Alex would almost certainly round this up and quote a day rate of £330.
See the difference? This final figure is solid. It covers his salary, the costs of running his business, his retirement planning, and even gives him a small buffer for unexpected lulls.
Going through a thorough contractor daily rate calculator process like this is the difference between guessing your worth and knowing it. It ensures your rate can support a sustainable business, not just cover your time for a day.


