


For many contractors, the strongest first move with £10,000 is to protect an adequate emergency buffer, then use an ISA or pension according to your access needs and retirement goals before considering higher-risk options. The right choice depends on whether you need capital soon, how much income volatility you face, and how much loss you could comfortably tolerate.
A contractor might have £10,000 sitting in a current account while waiting for a possible tax bill, a gap between contracts or an uncertain move from one IR35 arrangement to another. At the same time, that money could support retirement, a house deposit or long-term financial security. One pot is being asked to do several jobs.
The best ways to invest 10k therefore depend on risk tolerance, liquidity, tax treatment and time horizon. Cash protects flexibility but may lose spending power when inflation is higher than the interest rate. Investments offer more growth potential, but their value can fall and they aren't suitable for money you'll need shortly.
For the 2026/27 tax year, the overall UK ISA allowance is £20,000, running from 6 April 2026 to 5 April 2027, so a £10,000 lump sum can fit entirely inside an ISA wrapper under the NS&I explanation of ISA allowances. Before choosing an account, check current HMRC ISA guidance and relevant FCA information. Our contractor and umbrella guidance can also help you understand how income arrangements affect your wider financial planning.
1. Emergency fund and high-yield savings
A contract can end before the next one is signed. For a contractor or freelancer, part of a £10,000 pot may therefore need to protect rent, tax payments and business costs before it seeks investment growth.
Keep money for an income gap, unexpected expense or urgent tax bill in a safe, easy-access savings account. Shares can fall just when you need to sell.
Practical rule: Money needed for tax, rent, mortgage payments or essential household costs should not depend on market conditions.
Set the reserve according to essential monthly spending, household support and the reliability of your work pipeline. Someone with regular renewals may need less accessible cash than a freelancer whose income changes sharply. Umbrella workers should also allow for take-home pay that varies with assignments, rates and unpaid gaps.
A separate account makes the boundary clearer. Compare the interest rate, withdrawal conditions and deposit protection arrangements. A cash ISA may suit savings where its tax treatment fits your circumstances, while a standard account can be simpler for money needed immediately.
Useful actions include:
- Calculate essential spending: Include housing, utilities, food, insurance, transport and minimum debt payments.
- Separate tax reserves: Do not treat money earmarked for HMRC as investment capital.
- Prioritise access: Avoid locking emergency cash into a fixed term.
- Review the buffer: Reassess it after a contract ends, your household changes or your work moves inside or outside IR35.
An emergency reserve can also protect your crypto savings with an emergency fund, since volatile assets may be unavailable at the right value when cash is needed.
Income protection can complement cash reserves by helping during a period when illness prevents work. It does not replace accessible savings, so contractors can consider income protection insurance alongside their wider plan.
2. Individual Savings Accounts
An ISA is a tax wrapper, not an investment itself. You can hold cash or investments inside it, depending on the type you select.
UK adults can invest up to £20,000 per tax year across ISAs. Interest, dividends and capital gains within the wrapper are tax-free, making an ISA a practical home for £10,000 when you want tax-efficient growth without pension restrictions.
A Cash ISA can suit money needed relatively soon, particularly when protecting the original capital matters. A Stocks and Shares ISA fits money that can remain invested through market falls and recoveries. Choose according to the job the money must do, not the product name.
For contractors and freelancers, an ISA sits between a savings account and a pension. It can provide more access than a pension while avoiding the tax treatment of an unwrapped investment account. That flexibility matters during variable income, contract gaps or changes in IR35 status.
Withdrawals still need checking. Taking money out does not automatically restore your allowance. That depends on whether the ISA is flexible and whether the provider supports that feature under the official withdrawal rules.
Match the ISA to the job
- Cash ISA: Suitable for accessible savings and near-term spending.
- Stocks and Shares ISA: Suitable for a longer time horizon and tolerance for market falls.
- Lifetime ISA: Consider only if you meet the eligibility conditions and the purpose fits, such as an eligible first home or later-life objective.
- Provider choice: Compare platform fees, fund charges, transfer procedures and available investments.
The Investment Association reported Stocks and Shares ISA ownership rising from 16% to 21%, while Cash ISA use rose from 31% to 40% in its 2026 ISA Barometer. Contractors should ask whether holding cash reflects a genuine short-term need or discomfort with investment risk.
Keep tax reserves and money needed for the next contract outside long-term market investments. An ISA may be tax-efficient, but it does not remove investment risk or make inaccessible cash available at short notice.
You can also read UmbrellaCompany.com's guidance on investing in technology when deciding whether £10,000 should support your business or personal finances.
3. Retirement planning and pensions
A pension is powerful because it rewards patience, but that benefit comes with restricted access. A Self-Invested Personal Pension, or SIPP, lets you choose from investments such as funds, shares and bonds while keeping the money designated for later life.
The tax treatment can be valuable for contractors, particularly when income varies between tax years. Contributions may receive tax relief subject to the relevant earnings and annual allowance rules. The exact outcome depends on how you earn, how contributions are made and your wider pension position, so don't treat a SIPP as a simple substitute for an ISA.
The main trade-off is access. Pension money is intended for retirement, not a contract gap, upcoming VAT or an uncertain tax bill. A contractor who puts every spare pound into a pension may gain tax advantages but lose the flexibility needed to manage irregular income.
Decide what you're giving up
Before contributing £10,000, ask:
- When will you need the money: If the answer is unclear, retain an accessible reserve.
- How stable is your income: A volatile pipeline strengthens the case for sequencing contributions rather than committing the full pot immediately.
- What pension arrangements already exist: Check workplace, personal and previous contract-related pensions before adding more.
- How will the money be invested: A pension still needs an investment choice, and its value can fall.
The UK pension contribution guidance for contractors can help you understand the issues to raise with a regulated adviser. Look closely at provider charges, fund costs, contribution flexibility and transfer arrangements.
A pension works best when the money has a retirement purpose. It shouldn't be the first destination for funds needed to preserve your ability to keep trading.
4. Investment funds and unit trusts
Funds suit contractors who want market exposure without researching every company themselves. They pool investors' money into shares, bonds or other assets. Unit trusts and OEICs are common UK structures, but the wrapper does not remove investment risk.
Their main benefit is diversification. A global equity fund can spread exposure across regions and businesses, while a mixed-asset fund can combine shares and bonds. That may be easier to maintain when your attention is on winning contracts, managing invoices and handling variable income.
Your cash position should influence the fund you choose. A contractor with a thin income buffer may prefer a lower-risk mix and keep the rest in accessible savings. Someone with a secure reserve and a long retirement time horizon may tolerate more equities. Money set aside for an upcoming tax bill, VAT payment or contract gap should not be invested in a fund designed for longer-term growth.
Check the fund's details
Read the factsheet and examine:
- Investment objective: Confirm what the manager aims to achieve.
- Asset mix: Check the proportions held in shares, bonds, cash or specialist assets.
- Geographic exposure: A UK-labelled fund may still invest internationally.
- Total costs: Include the fund charge, platform fee and dealing costs.
- Risk rating: Use it to guide further research, not as a promise about future losses.
Passive index funds can provide broad exposure at a straightforward cost. Actively managed funds involve decisions by a professional manager and may charge more. Compare the strategy, service and total cost rather than relying on recent performance.
A Stocks and Shares ISA can place a fund inside the ISA tax shelter. If you invest outside an ISA, check how income and gains may be taxed, particularly if your contracting income already varies, and keep suitable records. A fund can simplify diversification, but it cannot guarantee access to cash or protect your capital when markets fall.
5. Stocks and shares investment
Direct shares give you ownership of individual companies. They can pay dividends and grow in value, but your result depends heavily on each business, sector and market.
That concentration matters when £10,000 is a large share of your wealth. A contractor investing everything in one client-related company, technology theme or familiar brand may be taking more risk than intended. Keep money needed for an upcoming tax bill, VAT payment or contract gap in accessible savings.
For many investors, a diversified fund or exchange-traded fund is easier to manage than a collection of individual shares. It can still fall sharply, yet the outcome is spread across businesses rather than tied to one company. A Stocks and Shares ISA may hold eligible investments within a tax wrapper, subject to its rules.
Build a process, not a hunch
- Start broad: Consider diversified index exposure before adding individual companies.
- Understand the business: Read its accounts, strategy and risk factors.
- Set a holding period: Match shares to a long-term goal, not near-term contractor cash needs.
- Limit speculation: Keep highly volatile shares to a small satellite holding, if at all.
- Review deliberately: Do not sell solely because headlines cause anxiety.
Equities can support long-term growth, but no annual return is guaranteed. Historical figures for broad markets may look attractive, yet they are not forecasts for your portfolio and values can fall as well as rise. Your time horizon, income buffer and comfort with losses matter more than a headline return.
An investing journal records why you bought, what could invalidate the decision and when you will review it. A best trading journal can help organise those notes, but avoid turning long-term investing into constant trading.
If your income varies under contracts or your IR35 position changes, review how much capital can remain invested before increasing equity exposure. The right amount is the sum you can leave untouched through a market fall.
6. Bonds and fixed-income securities
Bonds lend money to a government or company in exchange for interest and repayment under agreed terms. UK government gilts usually have lower default risk than corporate bonds, although corporate debt can offer higher income alongside greater credit risk.
For a contractor, bonds can reduce reliance on equities when markets fall or income becomes unpredictable. They can also suit a known spending date, provided the bond's maturity matches when the money is needed. Prices may still move before maturity, especially as interest rates change.
A short-duration gilt or bond fund is often simpler than choosing individual issues. An individual bond held to maturity offers a clearer repayment structure, but check the issuer, purchase price, coupon and tax treatment. A bond fund has no single maturity, so its value continues to fluctuate.
Match the holding to the job
Use fixed income according to the pressure the £10,000 needs to handle:
- A planned expense: Choose maturity and risk that fit the date you expect to spend the money.
- Portfolio balance: Use bonds to reduce equity concentration, not to remove investment risk.
- Credit quality: Check whether the fund holds government debt, investment-grade companies or riskier issuers.
- Interest-rate exposure: Review duration, which shows how strongly prices may respond to rate movements.
- Tax treatment: An ISA may be suitable for taxable interest, depending on your wider allowances and plans.
The right choice also depends on your time horizon. Money needed during a contract gap should not be placed in a holding that may need to be sold after a price fall. Keep tax reserves separate as well. A bond investment is not automatically available at the price you want, and inflation can reduce the spending power of future repayments.
Gilts have relatively low credit risk, but they are not risk-free in every circumstance. Selling before maturity can produce a loss.
7. Premium Bonds
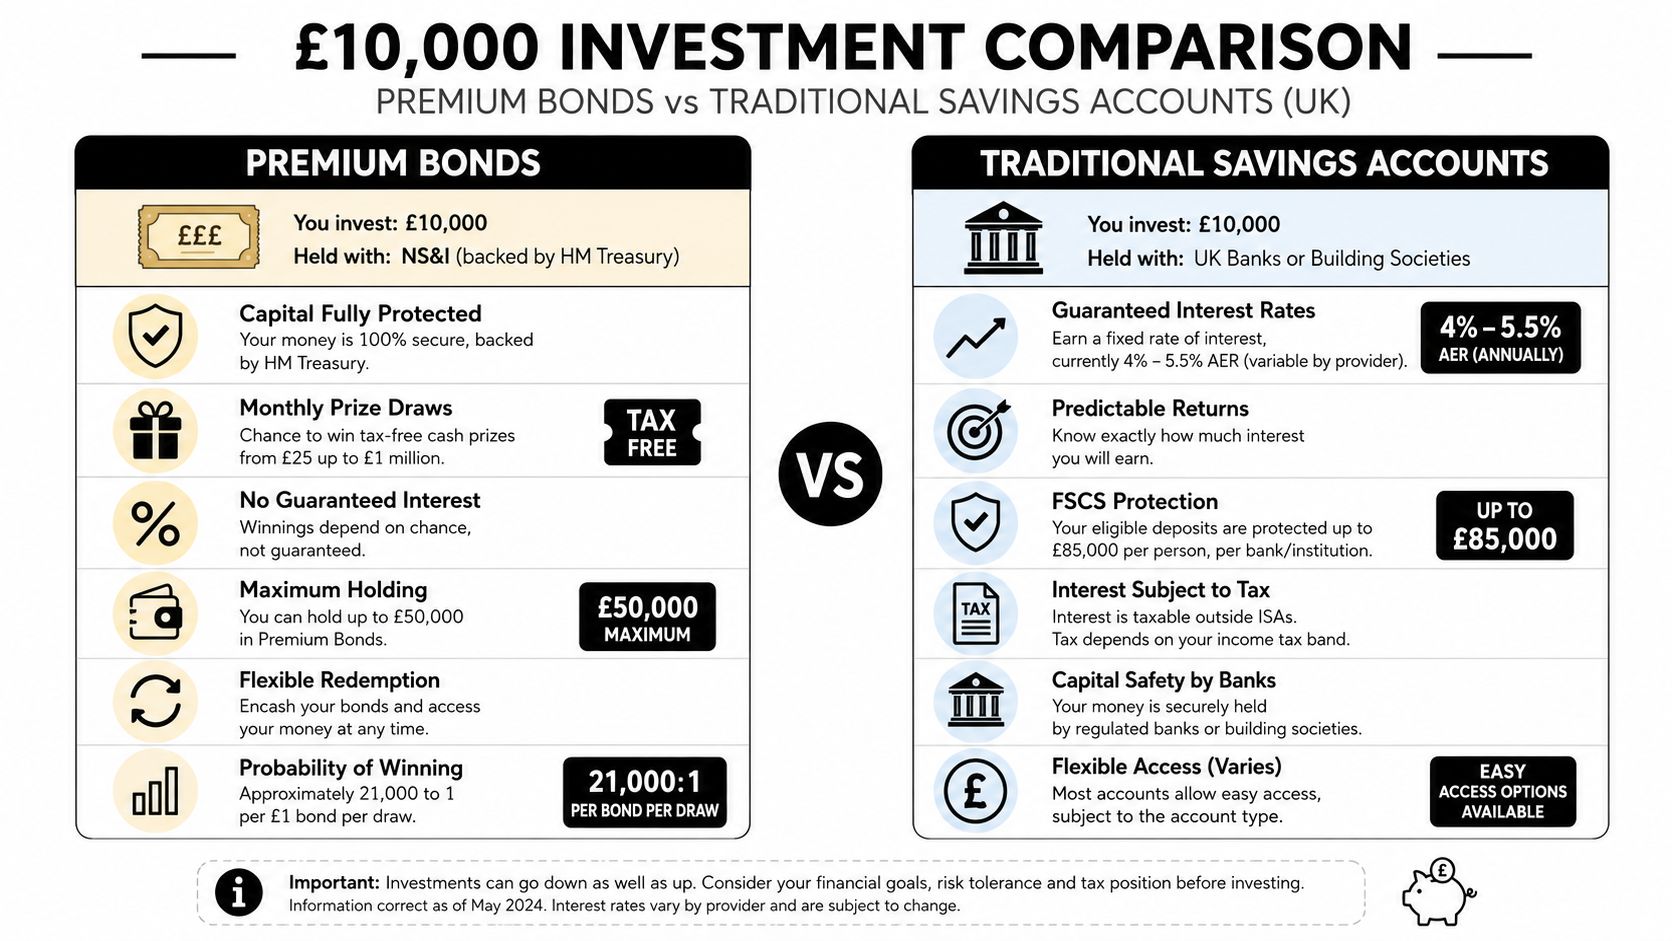
A contractor between assignments may need the £10,000 to remain available, while still wanting a return that does not depend on stock-market prices. Premium Bonds can fill that role for part of the money. They are issued by National Savings and Investments, a UK government-backed organisation. They pay no regular interest. Instead, eligible holdings enter monthly prize draws, with tax-free winnings.
The trade-off is certainty. There is no fixed rate, and no prize is guaranteed. The original capital can remain intact, but inflation may reduce what it can buy if winnings do not keep pace. That makes Premium Bonds different from savings accounts, where the expected interest is clearer.
Use them for liquidity, not a full investment plan
Premium Bonds may suit a freelancer who:
- Needs accessible reserves: The money could cover a contract gap or an unexpected business bill.
- Values capital security: The product is government-backed.
- Can accept variable returns: Monthly winnings may be high, low or absent.
- Has a defined allocation: The holding is one part of the plan, rather than the entire £10,000.
Keep tax money separate. Premium Bonds should not replace a reserve for an upcoming tax payment, particularly when income varies or an IR35 position changes the amount set aside.
Compare the product with easy-access and fixed-rate savings by asking what the money must do. A contractor seeking predictable interest may prefer a fixed-rate account. Someone who needs flexibility and can tolerate uncertain returns may value Premium Bonds instead.
For long-term growth, consider the time horizon. Once emergency and tax reserves are covered, an ISA or pension can give the remaining money a more deliberate investment purpose. Premium Bonds are better treated as a liquidity choice than as a retirement strategy.
8. Premium Bonds alternatives with fixed-rate savings
Fixed-rate savings accounts and fixed-term bonds exchange access for a guaranteed interest rate over an agreed period. They suit money with a clear job and a known date, such as a future tax payment or a planned business expense.
Contractors need to match the term to their cash flow. Someone with a signed contract, separate emergency reserve and no imminent tax bill might lock away part of £10,000. A freelancer between assignments, waiting for a tax calculation or uncertain about an IR35 position may need easy access instead. A higher rate is of little use if withdrawing early reduces the interest or is not permitted.
A cash ISA can keep interest tax-free, subject to the account terms and your available allowance. For the 2026/27 tax year, the overall ISA allowance is £20,000, so £10,000 can fit within it. From 6 April 2027, the Government plans to reduce the Cash ISA allowance to £12,000 for people under 65, while keeping the overall ISA limit at £20,000 and the Cash ISA limit at £20,000 for people aged 65 and over in its ISA reform factsheet.
Before opening an account, check:
- Withdrawal rules: Early access may be restricted or penalised.
- Maturity date: Avoid a term that extends beyond a known tax or business payment.
- Laddering: Staggered maturities can provide regular access without keeping everything in an easy-access account.
- Net return: Compare tax, fees and the cost of losing flexibility.
- Maturity instructions: Check whether the provider reinvests the balance automatically.
Cash still has a useful role in a contractor's plan, particularly for reserves that cannot take investment risk. Savings rates change, and inflation can reduce purchasing power when returns lag rising prices in its UK rates and inflation material. Review the rate, protection arrangements and access terms rather than assuming a fixed product remains competitive. A fixed account is a tool for predictable cash management, not a substitute for a longer-term investment strategy.
9. Real Estate Investment Trusts
A Real Estate Investment Trust, or REIT, lets you invest in property through shares in a company that owns, manages or finances income-producing buildings. The portfolio might include offices, warehouses, healthcare property, residential assets or specialist sectors, giving you property exposure without buying a building yourself.
For a contractor or freelancer, listed property can be easier to manage than becoming a landlord. You avoid a mortgage, repairs, tenant administration and the larger commitment of direct ownership. You can also sell shares more readily if a contract ends or an unexpected tax bill arrives, although the market price may be lower at that point.
The trade-off is market volatility. REIT prices respond to interest rates, financing costs, property values, occupancy and tenant demand. A REIT can fall while its buildings remain occupied, and dividends can change. It therefore suits money with a longer time horizon, not cash reserved for near-term tax or household costs.
Assess the business behind the shares
Before investing, examine:
- Property sector: Logistics, residential, healthcare and offices can perform differently through economic cycles.
- Tenant concentration: Dependence on a small group of major tenants can increase risk.
- Debt levels: Borrowing costs and refinancing needs affect profits.
- Occupancy and lease terms: These indicate how stable rental income may be.
- Portfolio concentration: A REIT fund can spread exposure across several property companies.
Eligible REIT investments held within an ISA can simplify the tax position on returns. Our buy-to-let investing guidance helps compare listed property exposure with the responsibilities of owning property directly.
Use REITs as a supporting allocation after establishing an accessible income buffer and considering your IR35 and business-structure position. Their liquidity helps, but their price remains exposed to market movements.
10. Peer-to-peer lending
Peer-to-peer lending lets you lend money to individuals or businesses through an online platform. Interest is the potential reward, while default, platform failure and limited access to your money are the main risks.
For a contractor or freelancer, that access issue matters. A contract can end unexpectedly, and tax may still be due on a known date. P2P lending is therefore unsuitable for emergency cash, VAT or corporation tax set aside, or money needed before your next invoice clears.
P2P also differs from a savings account in how protection works. The advertised return is not a guaranteed deposit rate, and safeguards depend on the platform and product. Spreading money across borrowers can reduce the impact of one default, but it cannot remove credit risk or operational risk.
Questions to answer before investing
Check the provider's current FCA status and permissions, then examine how it assesses borrowers and handles missed payments. The practical questions are:
- Liquidity: Can you exit early, or must you wait for loans to mature?
- Loss coverage: Is there a reserve fund or protection mechanism, and what limits apply?
- Tax treatment: How will interest and losses be reported in your circumstances?
- Diversification: Can your money be spread across enough borrowers and loan types?
A high headline rate signals greater risk rather than free extra income. Read the terms, start with a modest allocation and review the holding alongside your ISA, pension and business cash arrangements.
The deciding test is straightforward: does the possible return justify delayed access and a possible loss? If you cannot answer confidently, a diversified ISA fund or suitable savings product may fit a variable contractor income more comfortably. Consider P2P only after addressing near-term tax, reviewing your IR35 and business-structure position, and matching the investment to a time horizon you can maintain.
10-Point Comparison: Best Ways to Invest 10k
| Option | Implementation complexity | Resource requirements | Expected outcomes | Ideal use cases | Key advantages |
|---|---|---|---|---|---|
| Emergency Fund and High-Yield Savings | Very low, open account and deposit | Low cash requirement; 3–6 months expenses recommended | High liquidity, low return (~4–5.5%); capital preserved | Short-term emergency buffer; avoid forced asset sales | Immediate access; FSCS protection; simple and safe |
| Individual Savings Accounts (ISAs) | Low, choose provider and ISA type | Up to £20,000/year allowance; cash or stocks & shares options | Tax-free interest/dividends/capital gains; returns depend on underlying | Tax-efficient medium‑to‑long term saving/investing | Tax shelter; flexible ISA types; straightforward to use |
| Retirement Planning and Pensions (SIPP) | Medium–high, setup, investment selection, possible advice | Contributions up to £60,000/year (or % of earnings); fees and provider choice | Long-term, tax-advantaged growth; access from 55/57; compound benefits | Long-term retirement saving for contractors/freelancers | Significant tax relief; tax-free growth; control over investments |
| Investment Funds and Unit Trusts | Low–medium, pick funds on a platform | Minimums often £500–£1,000; ongoing management fees (~0.5–1.5%) | Diversified returns per fund strategy; performance varies by manager | Investors seeking diversification without stock-picking | Professional management; instant diversification; accessible |
| Stocks and Shares Investment | Medium–high, research and portfolio management | Brokerage account; time and knowledge for selection; £10k can diversify | Higher long-term growth potential (higher volatility); dividends possible | Growth-focused investors comfortable with risk | Direct ownership, dividend income, strong growth potential; ISA shelterable |
| Bonds and Fixed Income Securities | Low–medium, select gilts, corporate bonds or bond funds | £10k buys individual bonds or funds; yields ~3–5% | Predictable income and lower volatility; interest‑rate and inflation risk | Income-focused investors; portfolio diversification and capital preservation | Stable income; gilts offer government-backed safety; diversification |
| Premium Bonds | Very low, purchase via NS&I | £25 minimum, up to £50,000; capital protected by HM Treasury | No guaranteed return; chance of tax-free prizes; capital preserved | Risk-averse savers wanting capital safety with prize potential | Capital protection; tax-free prizes; no fees and easy access |
| Premium Bonds Alternatives (Fixed-Rate Savings) | Very low, open fixed-term account | Lump sum for fixed term (1–5+ years); FSCS protection up to £85k | Guaranteed fixed return (~4–5.5%); limited liquidity during term | Savers who can lock funds for a set period | Predictable returns; capital protection; higher guaranteed rates than easy-access |
| Real Estate Investment Trusts (REITs) | Medium, select REITs or REIT funds and monitor markets | Buy via brokerage; dividends typically ~3–5%; market liquidity applies | Rental income plus potential capital appreciation; property cycle exposure | Investors seeking property exposure without direct ownership | Property exposure with liquidity; dividend income; professional management |
| Peer-to-Peer (P2P) Lending | Medium, choose platform, diversify loans | Capital spread across many loans; platforms vary; returns 5–9% | Higher yield potential with credit and platform risk; liquidity can be limited | Investors seeking higher income who accept platform/default risk | Potentially higher returns than savings; passive interest income; supports SMEs |
Turn your £10,000 into a clear plan
The best ways to invest 10k aren't ranked by return alone. They're ranked by how well each option fits the job your money needs to do.
For accessible safety, use an easy-access savings account, a suitable Cash ISA or potentially Premium Bonds. You keep money for essential spending, contract gaps and tax obligations here. A contractor with variable income often needs more liquidity than someone receiving a predictable salary, especially during an IR35 transition or while waiting for a new assignment.
For tax-efficient growth with flexibility, a Stocks and Shares ISA is often the central option. The wrapper can hold diversified funds or other eligible investments, while withdrawals remain possible. Remember that withdrawing money doesn't restore your allowance unless the ISA is flexible and the provider offers that feature under HMRC's withdrawal rules.
For retirement-focused wealth building, consider a pension or SIPP once you can leave the money invested for later life. Tax relief can make pension contributions attractive, but restricted access means they shouldn't replace your emergency reserve. Check your earnings, existing contributions and relevant allowances before paying in.
For diversified market exposure, broad investment funds, global equity funds, bond funds and carefully selected REITs can spread risk across assets. Direct shares and P2P lending may have a place, but they demand stronger research and a clear understanding of potential losses. Don't confuse a higher possible return with a better fit.
A practical sequence for contractors
- Calculate essential expenses: Establish what you need to maintain your household and business during a gap.
- Reserve tax and near-term costs: Separate money owed to HMRC or needed for known commitments.
- Choose the wrapper: Decide whether access points towards an ISA or the retirement purpose supports a pension.
- Set your risk level: Consider how you'd react if the investment fell and when you could recover.
- Select diversified holdings: Compare funds, bonds, shares or property exposure only after choosing the account.
- Compare fees: Review platform charges, fund costs, dealing fees and transfer conditions.
- Review annually: Revisit the plan when your contracts, income, tax position or retirement goals change.
Cash shouldn't be dismissed because it may produce less long-term growth. Bank of England material recorded Bank Rate at 3.75% by mid-2026, while independent UK savings data put average instant-access accounts at about 2.11% in July 2026, below the reported inflation rate in this savings and inflation comparison. The useful question is whether that cash is buying necessary flexibility.
Investment adoption remains relatively limited. Fewer than half of UK adults hold an ISA, and around 21 million adults had some ISA assets in 2023/24 according to the UK ISA research paper. That doesn't mean everyone should invest immediately. It does show why a clear, UK-specific sequence matters.
Tax rules, pension rules and investment products can change. Check current HMRC and FCA information, and seek regulated financial advice if your situation involves complex tax, pension or investment decisions.
UmbrellaCompany.com helps contractors compare umbrella companies and find guidance on IR35, payroll and working arrangements. Visit the UmbrellaCompany.com website when you're reviewing how your contracting setup fits alongside your £10,000 financial plan.
Umbrella Company helps contractors and freelancers compare trusted umbrella companies based on their role, pay and IR35 support needs, with practical guidance to make the choice clearer. Visit Umbrella Company to compare providers and access contractor-focused guidance before you commit your money elsewhere.


