


Your first contract often feels like a win right up until the admin starts. The client asks whether you'll invoice through your own company or use an umbrella. Your recruiter mentions IR35. You start looking at VAT, expenses, bookkeeping, payslips, dividends, and suddenly the day rate isn't the only thing that matters.
That's where good accounting for contractors makes a real difference. It helps you choose the right setup, avoid tax mistakes, keep clear records, and understand why the money in your bank account doesn't always match the profit on paper.
For many UK contractors, these choices sit inside a much bigger operational environment. In construction alone, UK construction output was estimated at £38.9 billion in quarterly GDP terms in Q1 2024, and there were about 355,000 construction businesses in the UK in 2024, which shows how common project-based contractor work is across a fragmented market where accurate job-based accounting matters (Elliott Davis on construction contractor accounting methods).
Your Guide to Contractor Accounting
You've landed a contract, agreed a rate, and now you need a financial setup that is solidly functional for your operations. That means more than picking the option that sounds most tax efficient. You need to know who pays you, who deducts tax, what records you must keep, and how much admin you're willing to handle each month.
If you're new to contracting, the easiest way to think about it is this. You're choosing between a simpler payment route and a more hands-on business route. Both can be right. The best option depends on your contract terms, your IR35 position, and how much control you want over your finances.
A useful starting point is learning how to become a contractor in the UK, because your accounting setup sits alongside practical decisions such as choosing clients, agreeing rates, and understanding payment terms.
What contractor accounting really covers
Accounting for contractors usually includes:
- Getting paid correctly, whether through PAYE under an umbrella or through invoices raised by your own company
- Tracking tax properly, including Income Tax, National Insurance, Corporation Tax and VAT where relevant
- Keeping records organised, so invoices, receipts, contracts and payslips are easy to find
- Understanding profit versus cash, because money earned on paper and money received in the bank can move at different times
- Making compliant choices, especially when IR35 affects how your contract is taxed
Practical rule: If you can't explain how your next payment reaches your bank account, your accounting setup isn't clear enough yet.
Where contractors usually get stuck
Most confusion starts with three questions:
- Should I use an umbrella company or a limited company?
- Does IR35 change the answer?
- What can I claim, record, or register for?
Those answers become much easier once you separate the tax rules from the business structure. That's what we'll do next.
The Two Main Paths Umbrella vs Limited Company
Your first big accounting decision is structural. Are you working as an employee of an umbrella company, or are you running your own limited company?
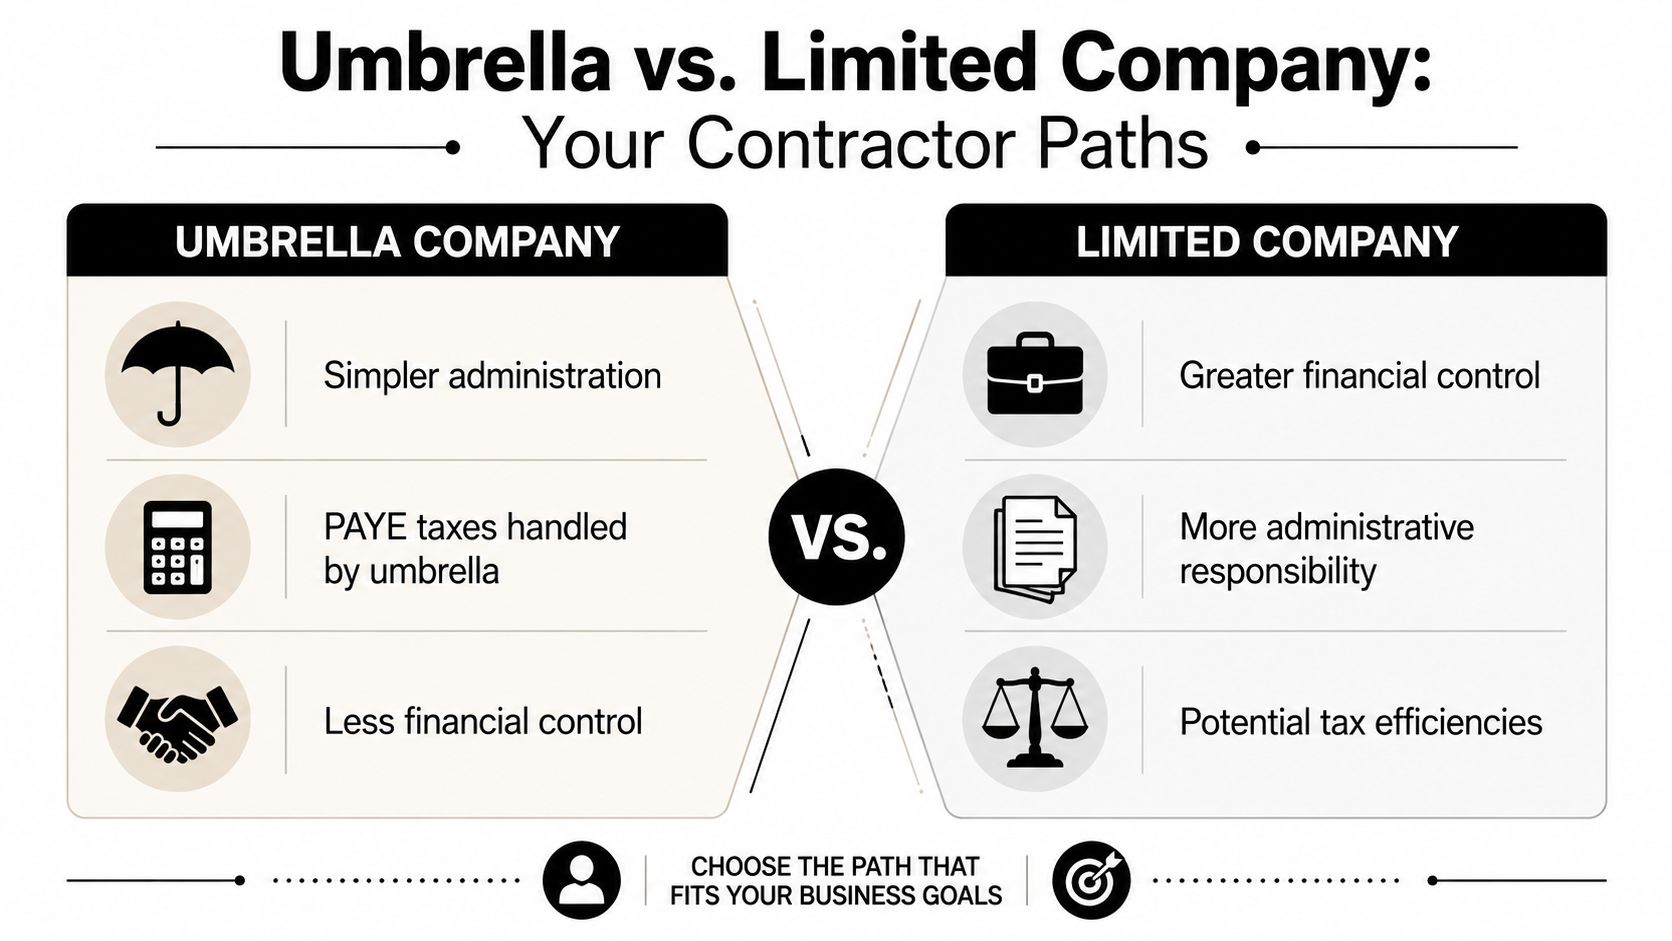
These two routes can look similar from the outside because you still do contract work for a client. But the money, tax treatment and admin are very different.
How an umbrella company works
With an umbrella company, you submit your timesheet or approved hours. The umbrella receives the funds and pays you through PAYE.
That means the umbrella handles payroll calculations, payslips, tax deductions and most of the routine admin tied to employment. For many contractors, that simplicity is the main benefit.
An umbrella route usually suits people who want:
- Less paperwork, because payroll and routine deductions are managed for you
- A straightforward process, especially when starting out
- Employment-style administration, including payslips and statutory payroll handling
- A practical option for inside IR35 work, where PAYE treatment already shapes the contract
The trade-off is control. You don't run the payment structure in the same way you would through your own company.
How a limited company works
A limited company is a separate legal entity. That's the key idea to understand.
You and the business are connected, but they are not the same thing. The company gets paid. The company pays its costs. You then take money from the company in the correct way, such as salary or dividends if appropriate.
Consider this:
| Question | Umbrella company | Limited company |
|---|---|---|
| Who receives the contract income? | The umbrella | Your company |
| Who runs payroll? | The umbrella | You or your accountant/software |
| Who keeps company accounts? | The umbrella for payroll records | You as director, with support if needed |
| Who has more control over timing and structure? | The umbrella | You |
A limited company usually appeals if you want:
- Greater control, because you run the business bank account and payment flow
- A clearer business identity, especially if you work with multiple clients
- Flexibility in company management, subject to the relevant tax rules
- A platform for growth, if contracting may turn into a wider business
A limited company gives you more levers to pull, but it also gives you more responsibilities to manage.
The practical difference day to day
Under an umbrella, your routine is mostly about timesheets, payslips and checking deductions.
Under a limited company, your routine expands. You'll usually need to raise invoices, keep receipts, reconcile the bank account, track taxes due, and maintain proper separation between personal and business spending.
Neither route is automatically better. One is simpler. The other offers more control. The right choice depends heavily on IR35, which is where contractor accounting decisions become much more precise.
IR35 The Deciding Factor for Your Finances
If there's one rule set that shapes contractor accounting more than any other, it's IR35, also known as the off-payroll working rules.
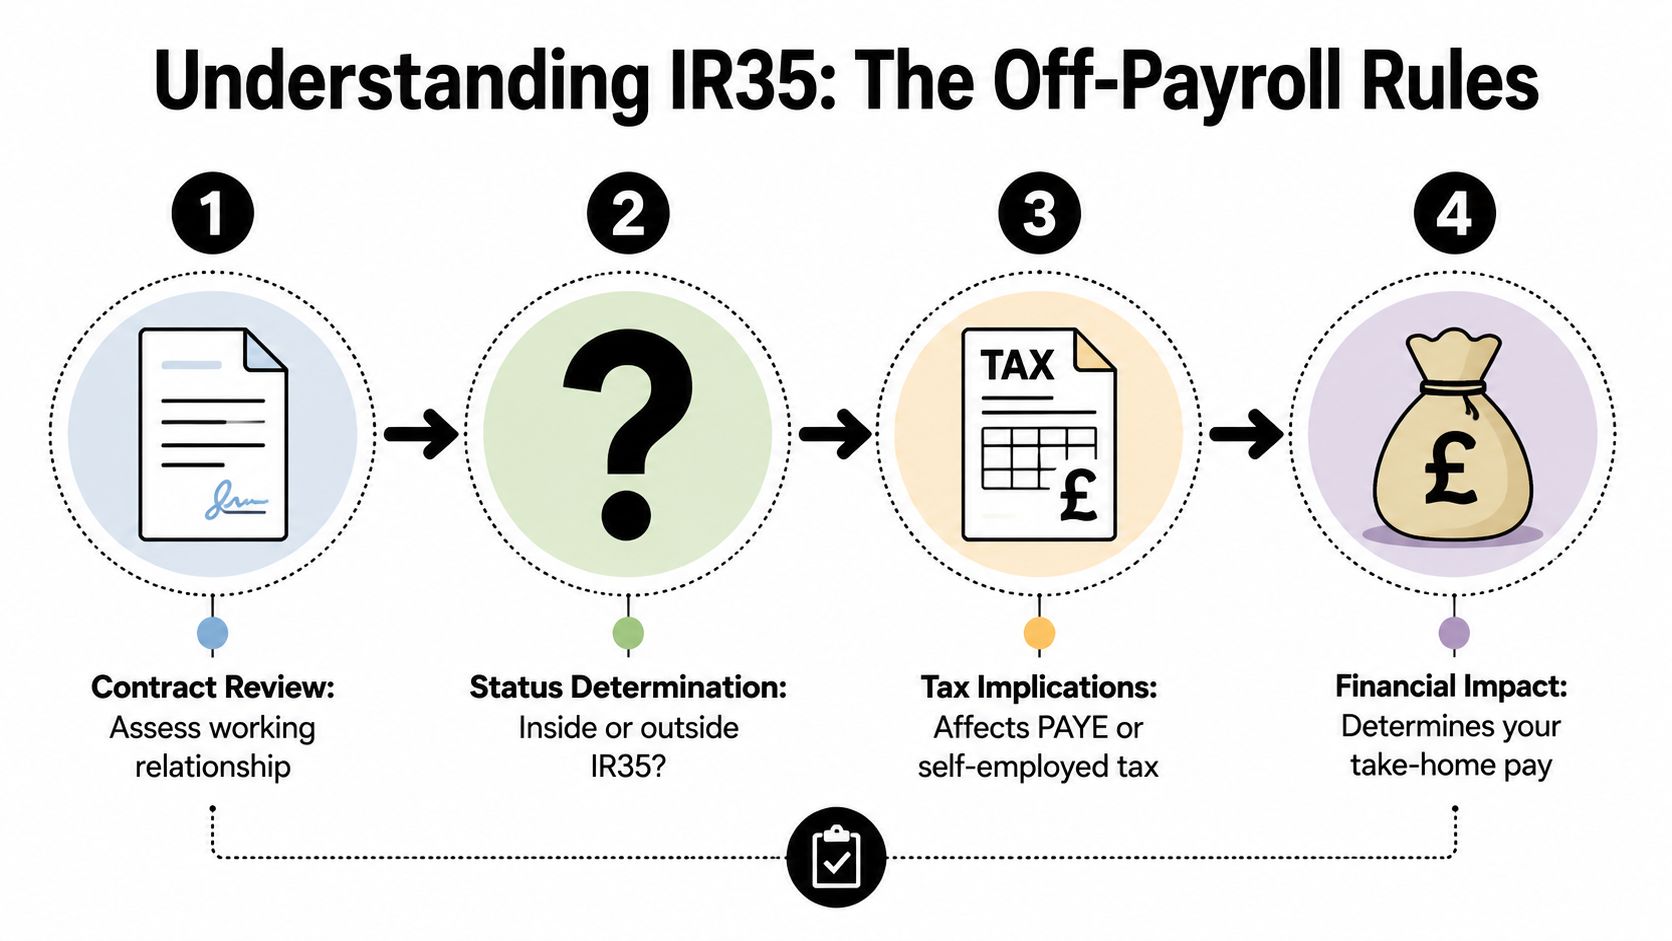
These rules were introduced for the public sector in April 2017 and extended to the private sector from 6 April 2021. HMRC reported that the reforms were expected to raise around £3.8 billion over the period 2020-21 to 2024-25, which shows how important status decisions are for tax compliance (HMRC discussion of off-payroll reforms).
If you need a deeper overview, this guide to IR35 for contractors helps frame the rule in practical terms.
What IR35 means in plain English
IR35 asks a simple question with big financial consequences.
If this intermediary were removed, would the worker look more like an employee for tax purposes?
If the answer is yes, the engagement may fall inside IR35. If not, it may sit outside IR35.
Inside IR35 does not automatically mean you become a permanent employee in the usual HR sense. It means the income is taxed more like employment income for that contract.
Inside IR35 and outside IR35
The easiest way to think about the difference is to compare the tax outcome.
Inside IR35
If a role is inside IR35:
- PAYE treatment applies to the engagement income
- Tax and National Insurance become central deductions
- The limited company route often loses much of its advantage for that contract
- An umbrella can be the cleaner admin choice, because payroll is already part of the arrangement
Outside IR35
If a role is outside IR35:
- You have more freedom in how you operate
- A limited company can make more sense, because you're running a genuine business-to-business engagement
- Bookkeeping matters more, because you're responsible for company records and tax filings
- Contract terms and working practices both matter, not just the words in the contract
Key point: IR35 is not a branding exercise. Calling yourself a contractor doesn't decide your status. The real working relationship does.
Why clients and contractors both need records
IR35 creates paperwork pressure on everyone in the chain. Contractors, fee-payers and clients need clear records of engagement terms, payment treatment and deductions where relevant.
That's why accounting for contractors isn't just about year-end tax returns. It's also about keeping an audit trail. If the contract changes, if the work pattern shifts, or if the payment route changes, your records need to show what happened and why.
A simple decision checkpoint
Ask these questions before choosing your route:
- Has the client confirmed the IR35 status?
- Will you be paid through payroll or by invoice?
- Do the working practices match an independent contractor model?
- Are you prepared to run company admin if the role is outside IR35?
If the role is inside IR35, simplicity usually matters more than elaborate planning. If it's outside IR35, company structure and bookkeeping become much more relevant.
Managing Your Money Allowable Expenses and VAT
Once your structure is clear, the next job is handling everyday money properly. Through this process, many contractors either stay organised and confident, or lose track of receipts, VAT, deadlines and cash flow.
Allowable expenses are not the same for everyone
The biggest mistake contractors make is assuming all expenses work the same way under every setup. They don't.
If you operate through your own limited company, you generally have more scope to record business costs, provided they are for business use. If you work through an umbrella, the rules are typically much tighter because you're being paid as an employee through payroll.
A simple test helps here. Ask whether the cost exists because of your business activity, and whether you can show that clearly with records.
Examples that contractors often review with their accountant include:
- Equipment and tools, such as a laptop or software subscription used for contract work
- Professional costs, including accountancy, insurance or relevant subscriptions
- Travel and accommodation, where the trip is business-related and the tax treatment supports it
- Training, where it relates properly to your current business activity rather than a personal career change
If you relocate temporarily for work, practical costs can build up quickly. Contractors who need short-term accommodation near a project may find specialist options such as housing for relocating professionals useful when planning legitimate business travel and temporary stays.
Keep the receipt, note the business reason, and record it promptly. An expense with no evidence is hard to defend later.
VAT in simple terms
VAT is a tax added to many goods and services. If you run a limited company, VAT may become part of your accounting depending on your circumstances and turnover.
Even before registration becomes necessary, contractors often ask whether voluntary registration could make sense. The answer depends on your client base, your costs and how much admin you're happy to take on.
A good first step is understanding the current VAT registration threshold in the UK, because that tells you when registration may stop being optional.
A practical VAT checklist
Use this as a quick sense-check:
- Who are your clients? If they are VAT-registered businesses, VAT may be less of a commercial issue in pricing discussions.
- What do you buy? If your company has regular VAT-bearing business costs, registration may affect recovery.
- How tidy are your records? VAT adds filing and record-keeping obligations, so weak bookkeeping becomes more risky.
- How stable is your billing? Irregular invoicing can make tax planning feel messy if you don't track it closely.
Why revenue timing can confuse contractors
For longer or staged work, accounting doesn't always follow the same rhythm as cash. Revenue recognition under IFRS 15-style frameworks follows a five-step contract model: identify the contract, identify performance obligations, determine transaction price, allocate the price, and recognise revenue as obligations are satisfied (NetSuite on construction accounting and revenue recognition).
That matters because your accounts may show income earned before all the cash has reached your bank, or vice versa. Contractors often feel this most strongly when invoices are delayed, work is delivered in phases, or a client approval process slows payment.
A Worked Example Umbrella vs Limited Company Pay
A worked example helps, but there's an important limit here. We should not pretend there's one universal take-home pay figure for every contractor on the same day rate.
Why not? Because the final result depends on several moving parts, including the umbrella margin, tax code, pension choices, timing of payments, company costs, salary strategy, dividends, accountancy fees, and whether the contract is inside or outside IR35.
So instead of inventing figures, let's use Alex, a fictional contractor on a £500 day rate, and focus on how the money flows in each route.
Scenario one inside IR35 through an umbrella
Alex takes a contract that sits inside IR35. The umbrella receives the contract income and processes pay through payroll.
That means Alex's pay path usually looks like this:
| Item | Scenario 1: Inside IR35 (Umbrella) | Scenario 2: Outside IR35 (Limited Co.) |
|---|---|---|
| Contract income | Paid to the umbrella | Paid to Alex's company |
| Payment processing | Umbrella runs PAYE payroll | Company invoices client |
| Main deductions before personal pay | Umbrella margin and payroll-related costs may affect the assignment rate before net pay is reached | Company costs, tax provisions and director payment choices shape what Alex can take |
| Personal taxation route | Salary-style pay through PAYE | Combination depends on company strategy and tax rules |
| Admin burden | Lower day-to-day admin for Alex | Higher admin, with bookkeeping and filing responsibilities |
| Best fit | Often more practical for inside IR35 roles | Often more suitable for outside IR35 roles |
Alex receives a payslip. Tax is deducted at source. National Insurance is part of the payroll process. The main benefit here is clarity and simplicity. Alex doesn't need to manage company accounts for this contract route in the same way a director would.
Scenario two outside IR35 through a limited company
Now assume Alex takes a separate outside IR35 contract and trades through a limited company.
The company raises invoices. The client pays the company. Alex then decides, with proper professional support, how to draw funds from the company in a compliant and tax-aware way.
That means Alex now has to manage:
- Sales invoices, so income is billed correctly
- Business costs, which need to be recorded and evidenced
- Tax provisions, because not every pound in the company bank account belongs to Alex personally
- Director payments, which need to be handled properly rather than casually transferring money out
The company bank balance is not your personal spendable balance. That single misunderstanding causes a lot of contractor stress.
What this example actually shows
The point of the comparison isn't that one route always produces a bigger number. The key lesson is that IR35 determines the shape of the calculation.
For inside IR35 work, the umbrella route often matches the tax treatment more naturally and reduces admin.
For outside IR35 work, a limited company can give Alex more control, but only if Alex is willing to keep proper records, plan for tax, and treat the company as a separate entity.
Bookkeeping Best Practices and Software Choices
Bookkeeping sounds dull until you need an invoice urgently, can't find a receipt, or realise your bank balance doesn't explain your tax bill. Then it becomes one of the most valuable habits in your business.
For contractors, good bookkeeping does three jobs at once. It supports compliance, it keeps day-to-day admin under control, and it helps you make better decisions with real numbers rather than guesswork.
Why profit and cash are not the same
A common issue for contractors is the gap between reported profit and cash flow. That often happens because revenue is recognised at a different time from when cash is received, especially where change orders, retainage or underbilled work are involved (CMiC on construction accounting basics and advanced concepts).
That idea matters even outside large construction projects. In everyday contractor terms, you can finish work this month, issue an invoice, and still wait for payment. On paper, the income may already matter. In your bank account, it hasn't arrived yet.
Bookkeeping habits that keep contractors safe
Use a simple operating rhythm.
- Separate accounts clearly. If you have a limited company, keep business spending out of your personal account as far as possible.
- Record transactions weekly. Waiting until quarter end usually means missed receipts and patchy memory.
- Match invoices to payments. Reconcile what you billed against what arrived.
- Store documents digitally. Save contracts, invoices, receipts and statements in one organised system.
- Set aside tax money early. Don't treat future tax liabilities as spare cash.
For contractors dealing with project-style work, cost tracking by job can also be useful. If you want a practical example of how project-based cost control works, this guide on managing remodeling project costs shows why allocating costs properly can improve visibility.
What to look for in software
You don't need the flashiest software. You need software that reduces mistakes and gives you clean records.
A sensible shortlist should include:
- Bank feeds, so transactions import automatically
- Receipt capture, so you can store expense evidence quickly
- Invoice creation, with clear customer records
- VAT support, if registration applies
- MTD compatibility, so the software supports UK digital filing requirements
- Reporting tools, especially cash flow and profit views
If you're comparing options, a guide to the best invoicing software for contractors can help you focus on features that matter in real contractor workflows.
Good software doesn't replace judgement. It gives your judgement better information.
A simple monthly review
At least once a month, check:
| Review area | What to ask |
|---|---|
| Invoices | Have all completed pieces of work been billed? |
| Payments | Which invoices are still outstanding? |
| Expenses | Is every business cost supported by a receipt or record? |
| Tax | Have you set money aside for upcoming liabilities? |
| Cash flow | Does the bank balance support the next few weeks of business activity? |
That short review often does more for financial control than a long annual catch-up.
Making the Right Choice for Your Contracting Career
A contractor can take two identical day rates and end up with two very different working lives. One has fewer admin tasks and a predictable routine. The other has more responsibility, but also more room to build a business that can grow beyond the next contract.
That is the real decision at this stage.
Your accounting setup should match the career you want over the next few years, not just the contract you signed this month. A good choice gives you a payment structure that fits your risk level, your time, and your plans. A poor choice creates friction every time you invoice, review tax, or decide whether to take on new clients.
A useful way to decide is to ask three questions in order.
First, how do you want to work day to day? If you want employment-style regularity, with payroll and fewer moving parts, choose the route that keeps administration light. If you want to run your own business, make decisions as a director, and shape how money flows through the company, choose the route that gives you that control.
Second, what are you building? Some contractors want contracting to feel like a stable income stream between other life priorities. Others want to turn specialist skills into a business with a name, a reputation, and a pipeline of clients. In that second case, your company structure connects to branding, pricing, and how clients see you. Resources such as Northpoint Web on contractor marketing can help you think about that wider business picture.
Third, how much responsibility are you ready to carry? Running a limited company works like owning the control panel as well as doing the work. You get more buttons to press, but you also need to watch the readings. If that sounds appealing, the extra admin can support your long-term goals. If it sounds like a distraction from client delivery, a simpler arrangement may be the better fit for this phase of your career.
The best decision framework is simple. Choose the setup that fits your current contract, supports the way you want to work, and still makes sense if your goals expand. That is how contractor accounting stops being a tax chore and starts becoming part of your career strategy.
If you've decided the umbrella route is the right fit for your next contract, Umbrella Company can help you compare providers, understand your options, and get set up with more confidence.


